


Sensata Technologies Holding (ST) is back in focus after announcing brake force sensors that support electromechanical braking in electric vehicles, a shift from hydraulic systems that hinges on precise, real-time clamping force measurement.
The new brake force sensor announcement lands after a mixed run for Sensata Technologies Holding, with the share price up 17.08% year to date but down 12.17% over 90 days, while total shareholder return over the past 12 months is 30.19%. This suggests that longer term optimism has outweighed recent volatility.
Scan other braking and EV hardware specialists moving on similar themes with our curated 92 robotics and automation stocks for sensor rich automation and control plays.
The recent swing in Sensata Technologies Holding, with a 30.19% total return over 12 months but a 12.17% decline over 90 days, raises a simple question: Is the meaningful upside already captured, or does the current valuation still leave room ahead?
Most Popular Narrative: 23% Undervalued
The prevailing valuation narrative pegs Sensata Technologies Holding at a fair value of about $52.73, compared with the last close at $40.85. This points to a wide gap that hinges on how convincingly management can convert its electrification and specialty sensing pipeline into future earnings.
Ongoing strategic focus on applications for electrified powertrains (including electrical protection and tire pressure monitoring systems) across global automotive and NEV markets increases content-per-vehicle, expanding Sensata's addressable market and supporting topline and earnings growth as electrification accelerates worldwide.
See why 7 investors see Sensata Technologies Holding as 23% undervalued.
Result: Fair Value of $52.73 (UNDERVALUED)
Still, the Sensata Technologies Holding story frays quickly if Chinese EV customers push harder on pricing, or if sensor tech commoditisation forces heavier R&D spend to stay competitive.
Find out about the key risks to this Sensata Technologies Holding narrative.
Another View: Sensata Technologies Holding Looks Expensive On Earnings
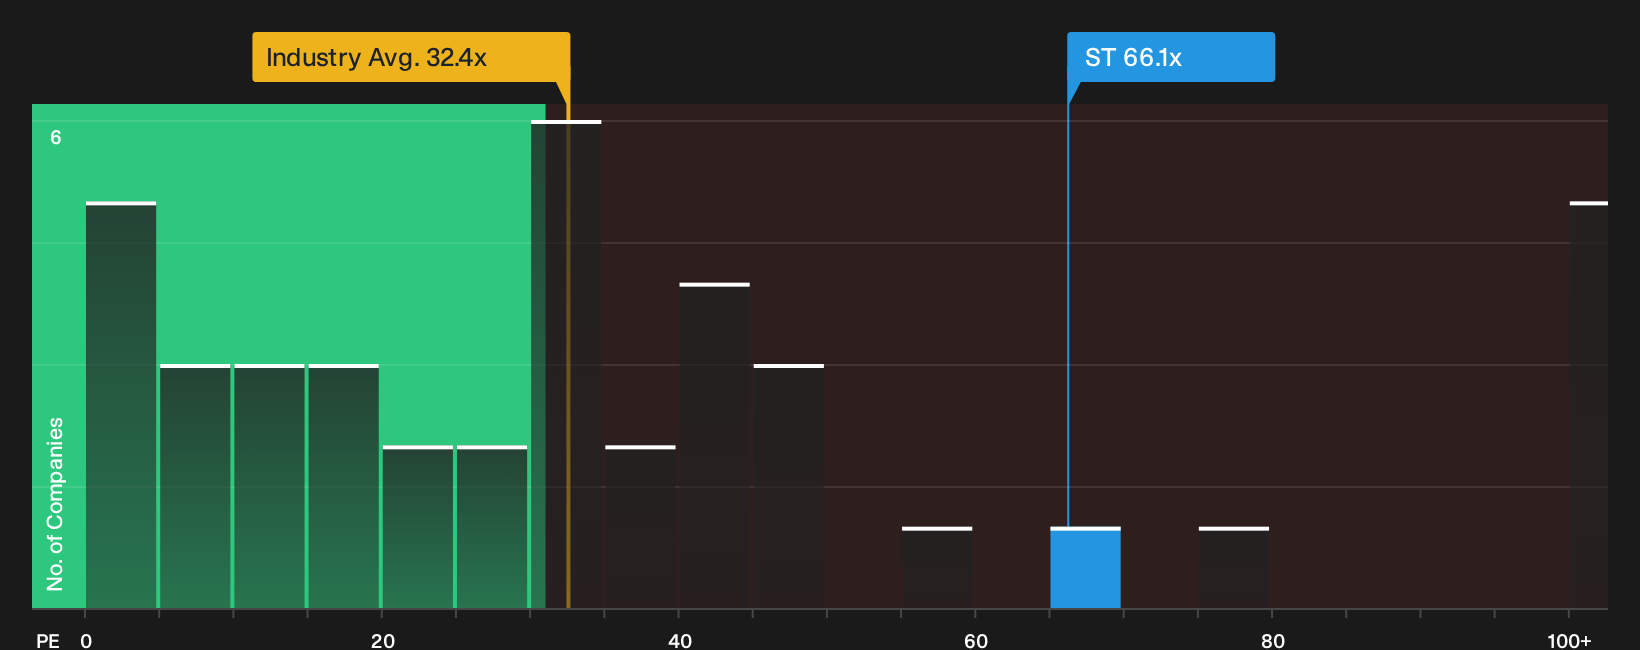
The SWS DCF model points to upside for Sensata Technologies Holding, yet the simple earnings multiple tells a tougher story. The stock trades on a P/E of 66.1x versus a fair ratio of 29x and a US Electrical industry average of 31.7x. That gap suggests investors are paying a rich price for the current profit base, so how comfortable are you with that kind of valuation risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sensata Technologies Holding can feel confusing, so move quickly, review the full data set, weigh both the downsides and upsides, and then check the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Sensata Technologies Holding?
If Sensata Technologies Holding has sparked fresh questions about pricing and quality, you can use that curiosity to scan other opportunities with strong fundamentals and clear risk profiles.
- Consider steady compounding potential by reviewing companies with resilient balance sheets and clean fundamentals through our list of solid balance sheet and fundamentals (25 results).
- Explore potential mispriced opportunities by checking companies that combine quality metrics with attractive valuations using our 35 high quality undervalued stocks.
- Review your income strategy by assessing companies with higher yields and payout metrics inside our 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com