


- A10 Networks has introduced the A10 AI Gateway, a security platform aimed at protecting traffic between AI agents, applications, and large language models, responding to tighter regulatory attention on digital resilience and incident response.
- The new gateway directly targets the operational gap between AI heavy workloads and existing security controls, which could affect how A10 Networks allocates capital, prioritizes product investment, and manages regulatory compliance demands.
- We will now assess how A10 Networks' investment narrative could shift as regulators highlight digital resilience around its new AI Gateway.
Scan how other AI security and infrastructure plays measure up to A10 Networks by reviewing our hand picked 55 AI infrastructure stocks in parallel with this new AI Gateway launch.
A10 Networks Investment Narrative Recap
To own A10 Networks you need to believe that secure, low latency networking for AI heavy workloads can remain a durable problem that customers keep prioritizing. The A10 AI Gateway launch plugs directly into that story, but the near term hinge still feels operational. Execution on product rollouts and AI focused security offerings looks more important than any single launch headline.
The biggest swing factor right now is how concentrated revenue is around one AI infrastructure customer that contributes roughly 37% of sales. That concentration risk does not change because of the AI Gateway announcement. Supply chain pressure on memory components remains another practical overhang that could keep gross margins under strain.
The new A10 AI Gateway ties closely to regulators pushing harder on digital resilience and incident response for financial and critical infrastructure traffic. This product speaks directly to that requirement by managing and securing flows between AI agents, banking applications, and large language models, which puts A10 Networks squarely in the operational hot zone for compliance heavy buyers.
For you as an investor, the key question is whether this launch helps broaden the customer base beyond the largest AI infrastructure account and supports the existing mix shift toward security led offerings that already represent about 72% of revenue. If A10 Networks uses the Gateway to deepen wallet share with enterprises in the Americas, that could gradually offset some concentration and supply chain stress.
A10 Networks' current analyst narrative points to revenues of $428.0 million and earnings of $77.3 million by 2029, based on an implied 11.3% yearly revenue growth rate and a move in earnings from $43.0 million today. This means an increase of about 80% in profit levels over that period.
Discover why A10 Networks' fair value indicates a 49% potential upside to its current price that may not last much longer.
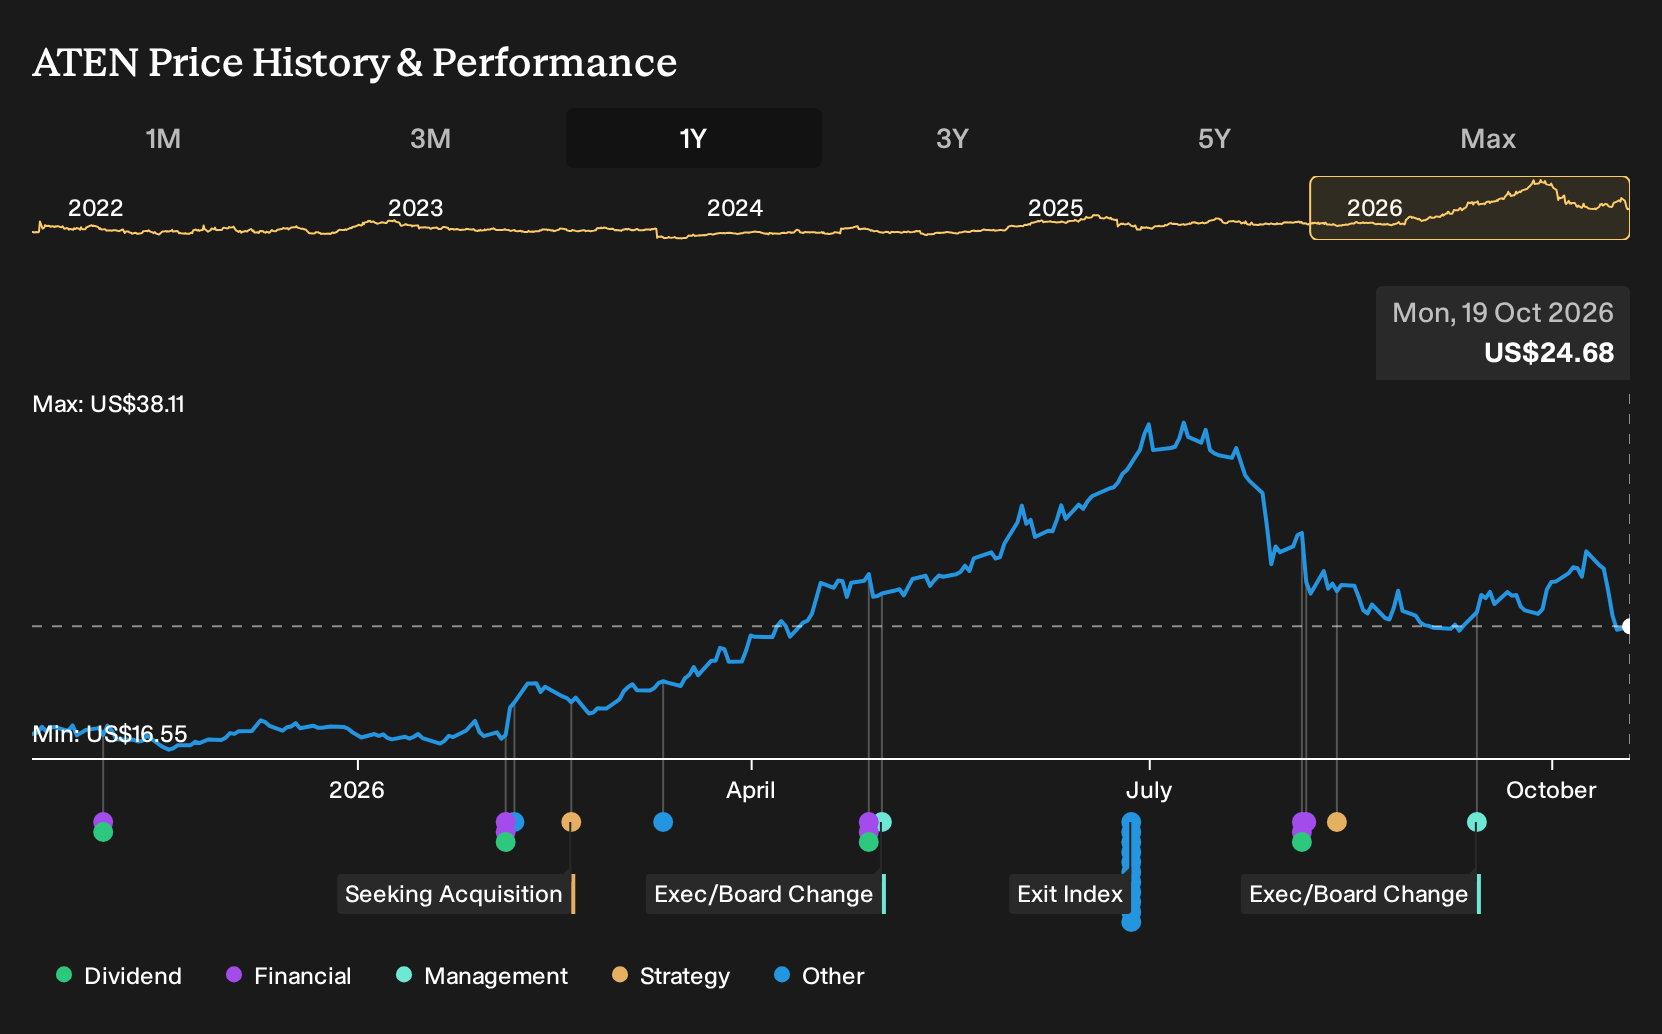
Exploring Other Perspectives
One alternate view on A10 Networks leans hard into optimism around AI security spending. The most bullish analysts were already modeling about $424.3 million in revenue and $87.5 million in earnings by 2029, compared with the consensus $428.0 million and $77.3 million. Both forecasts pre date the AI Gateway news, so you may see those narratives shift.
Explore 2 other A10 Networks fair value estimates, including one that suggests as much as 49% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your A10 Networks research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for A10 Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A10 Networks' overall financial health at a glance.
Looking for more investment ideas beyond A10 Networks?
If the A10 Networks story has sharpened your thinking about risk, rewards, and concentration, it can help to compare that framework against a wider set of opportunities using the Simply Wall St Screener.
- If you want potential upside with tight budgets in mind, scan a curated group of 12 elite penny stocks with strong financials that already clear higher financial quality bars.
- For investors who care most about paying a reasonable price for resilient fundamentals, sift through a 35 high quality undervalued stocks that combines stronger cash flows with sturdier balance sheets.
- If capital preservation and a smoother ride matter more to you than headline growth, start with a 32 resilient stocks with low risk scores that focuses on businesses with lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com