


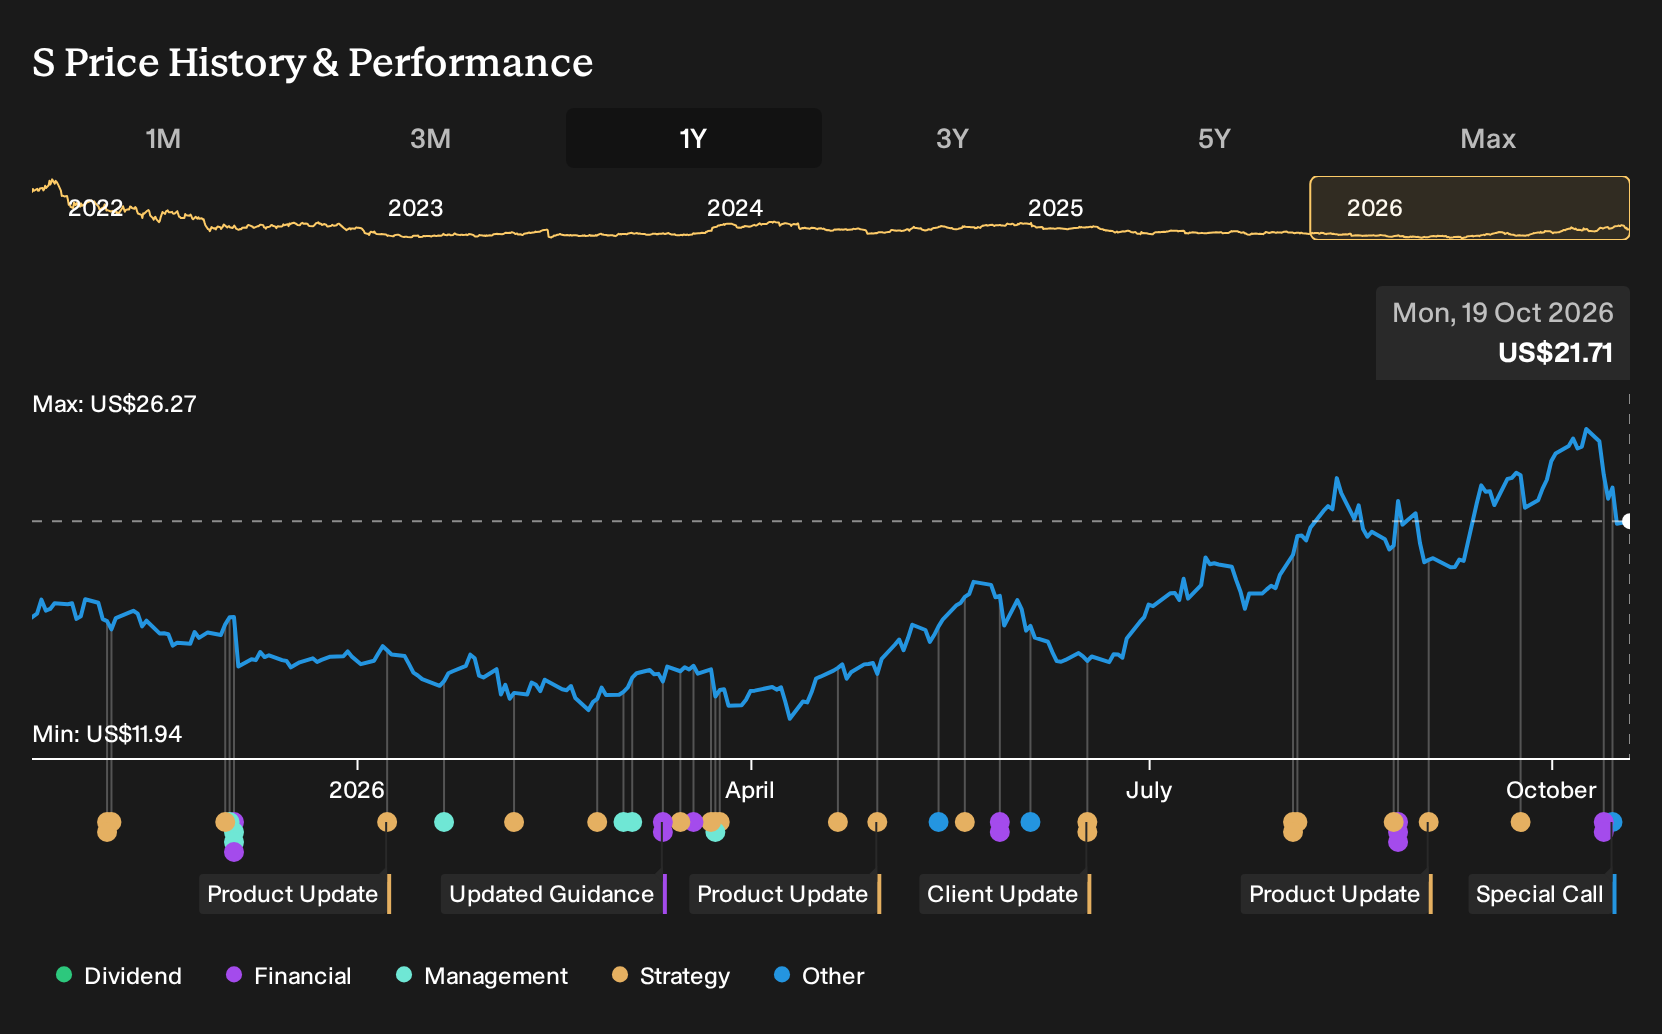
- SentinelOne recently issued and completed US$1.25b in senior unsecured zero coupon convertible notes due October 1, 2031 under Rule 144A, with the securities priced at 100% of principal.
- The large zero coupon convertible structure points to SentinelOne prioritising liquidity and balance sheet flexibility while accepting future equity dilution risk instead of near term cash interest costs.
- We will now look at how SentinelOne's investment narrative could shift in light of the sizeable zero coupon convertible financing.
Scan SentinelOne alongside other balance sheet focused stories by reviewing our hand picked list of solid balance sheet and fundamentals (1 results) that are shaping the next wave of defensively financed growth stocks.
SentinelOne Investment Narrative Recap
To own SentinelOne, you need to believe its AI driven Singularity platform can keep winning security budgets while the business works through years of reported losses. The zero coupon converts add liquidity and flexibility without new cash interest, which can support ongoing R&D, cloud, identity and data security expansion if execution on product integration stays tight.
The near term catalyst still sits in sustained revenue growth and proof that operating losses can narrow over time. The biggest risk remains that heavy investment and reliance on large partners pressure margins, while deal timing, international complexity and industry consolidation introduce lumpier growth and tougher competitive pricing.
The fresh US$1.25b zero coupon senior unsecured convertible notes due 2031 are the key update around this story. This structure increases funding sourced from external borrowing, which is classified as higher risk funding, and it brings potential future dilution rather than immediate interest expense, so your focus shifts to how efficiently SentinelOne turns this capital into product and go to market progress.
That scale of balance sheet firepower will sit beside an unprofitable profile, where analysts expect continued losses over the next three years and net income currently sits at a loss of US$340.1m on US$1.1b of revenue. Execution on multi product adoption, partner momentum and cost discipline now matters more because incremental missteps compound both earnings risk and eventual dilution from the convertible notes.
SentinelOne's narrative projects US$1.8b revenue and US$213.5m earnings by 2029. This is based on an assumption of 18.3% yearly revenue growth and an earnings improvement of about US$553.6m from a current loss of US$340.1m.
Uncover why SentinelOne's fair value indicates a 12% potential upside to its current price. This opportunity could narrow quickly.
Exploring Other Perspectives
For SentinelOne, the sharpest contrast comes from the bearish focus on how hard it might be to turn record remaining performance obligations into actual revenue. Those lower ranked analysts were only assuming about 17.3% yearly top line growth to roughly US$1.8b and US$208.3m earnings by 2029, which is already cautious. They have not factored in the zero coupon converts yet, so you should expect some of these narratives to shift. Use this to test your own view and explore how different the story can look when expectations move a few turns lower on the P/E math.
Explore 3 other SentinelOne fair value estimates, including one that suggests it could be worth just $24.25.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider independent research and judgment.
- A great starting point for your SentinelOne research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SentinelOne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SentinelOne's overall financial health at a glance.
Looking for more investment ideas beyond SentinelOne?
Once you have a view on SentinelOne, it can help to line it up against other opportunities that fit different risk and return profiles, so you can see where it truly belongs in your portfolio.
- If you want income resilience, scan a focused group of potential yield candidates through 8 dividend fortresses.
- For investors who care most about quality at a reasonable price, compare SentinelOne with a 35 high quality undervalued stocks that blend strong fundamentals with attractive valuations.
- When capital preservation is a priority, stress test your ideas against a 1 resilient stocks with low risk scores that have more defensive characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com