


Mycronic (OM:MYCR) drew fresh attention after announcing a client order in the US for two SLX mask writers worth between US$14 million and US$16 million, with delivery planned for the first quarter of 2028.
Recent trading tells a mixed story. The share price is up 38.6% year to date and the 1 year total shareholder return is 51.07%, yet the stock has declined 13.49% over 90 days and 11.13% over the past week. This suggests that momentum for Mycronic may be cooling in the short term, even as longer term holders have seen strong compounding over three and five years.
Scan how Mycronic’s latest mask writer order compares with other semiconductor equipment plays by reviewing the 92 robotics and automation stocks that are already pricing in next-cycle automation demand.
After a 51.07% 1 year return and a sharp pullback in recent weeks, Mycronic now sits in a grey zone. Is most of the easy upside already spent, or does the valuation still leave room ahead?
Most Popular Narrative: 7% Undervalued
On Simply Wall St’s most followed storyline, Mycronic’s fair value of SEK321.67 sits modestly above the last close at SEK300.20. This frames the recent pullback as a potential discount rather than a completed move.
Expansion along the semiconductor back end and advanced packaging chain, supported by acquisitions such as Cowin, Surfx, Vanguard and Hprobe and a focus on MRAM test and plasma cleaning, positions Mycronic to add new equipment lines that can support revenue and earnings power over time.
See why 10 investors see Mycronic as 7% undervalued.
Result: Fair Value of SEK321.67 (UNDERVALUED)
Still, if PCB Assembly Solutions fails to lift profitability or if newer Pattern Generators lines dilute margins, the Mycronic upside story could quickly look far more fragile.
Find out about the key risks to this Mycronic narrative.
Another View: Mycronic Looks Expensive On Earnings
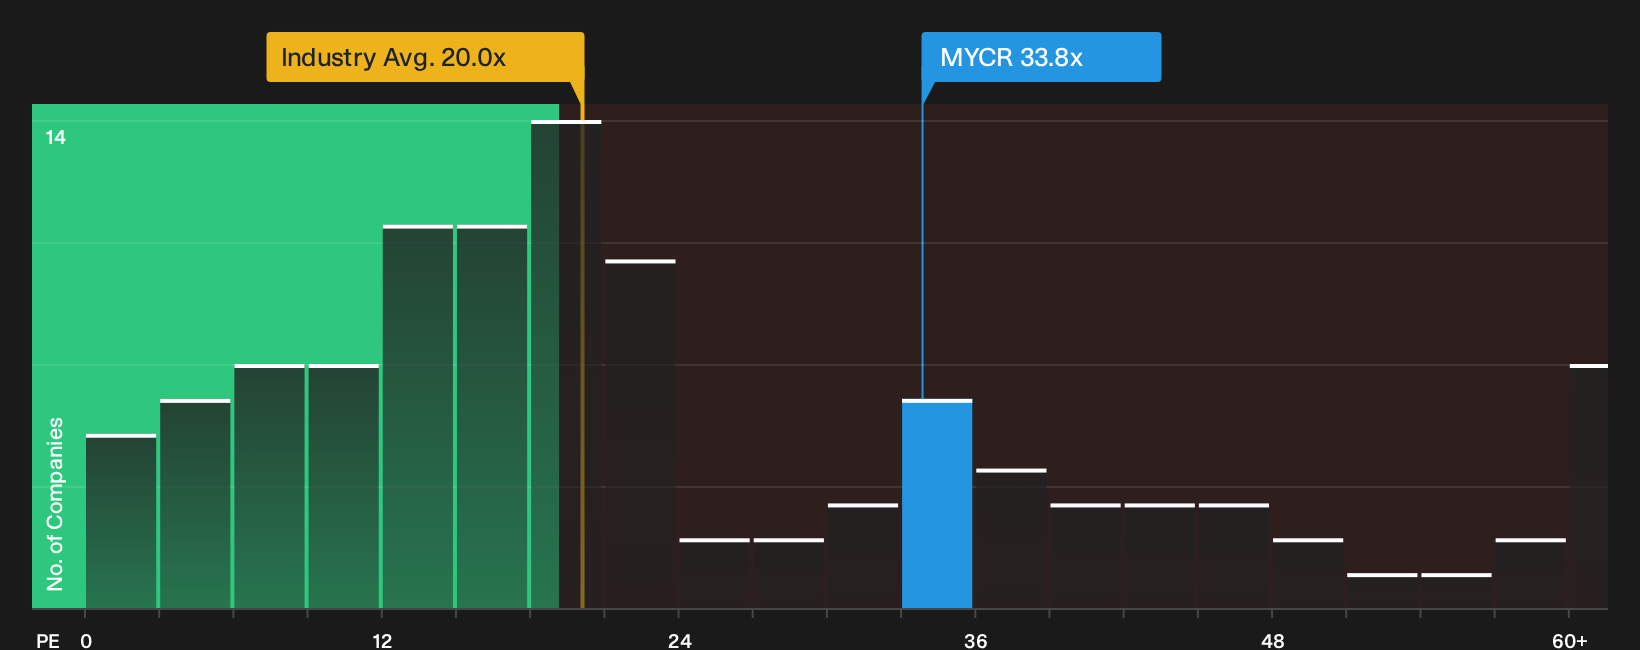
Look away from fair value models for a moment and focus on what investors are actually paying for Mycronic today. At a P/E of 33.8x versus a European Electronic industry average of 20.4x and a fair ratio of 26.9x, the stock carries a clear valuation premium that could compress if expectations ease.
That gap on earnings multiples raises a different question. Is the current price rewarding patience, or does it lean too hard on forecasts that may already be in the tag?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Mycronic can feel confusing, so consider reviewing the underlying data promptly and decide where you stand by checking the 2 key rewards.
Looking for more ideas beyond Mycronic?
If Mycronic has sharpened your focus, do not stop here. Fresh opportunities often sit just outside your current watchlist, and waiting can mean missing the next move.
- Target resilience in shaky markets by scanning a 230 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles.
- Hunt for mispriced potential and run a 199 high quality undervalued stocks to see which companies the market may be overlooking.
- Prioritise financial strength and cash discipline by filtering through a list of solid balance sheet and fundamentals (202 results) that keeps weak balance sheets off your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com