


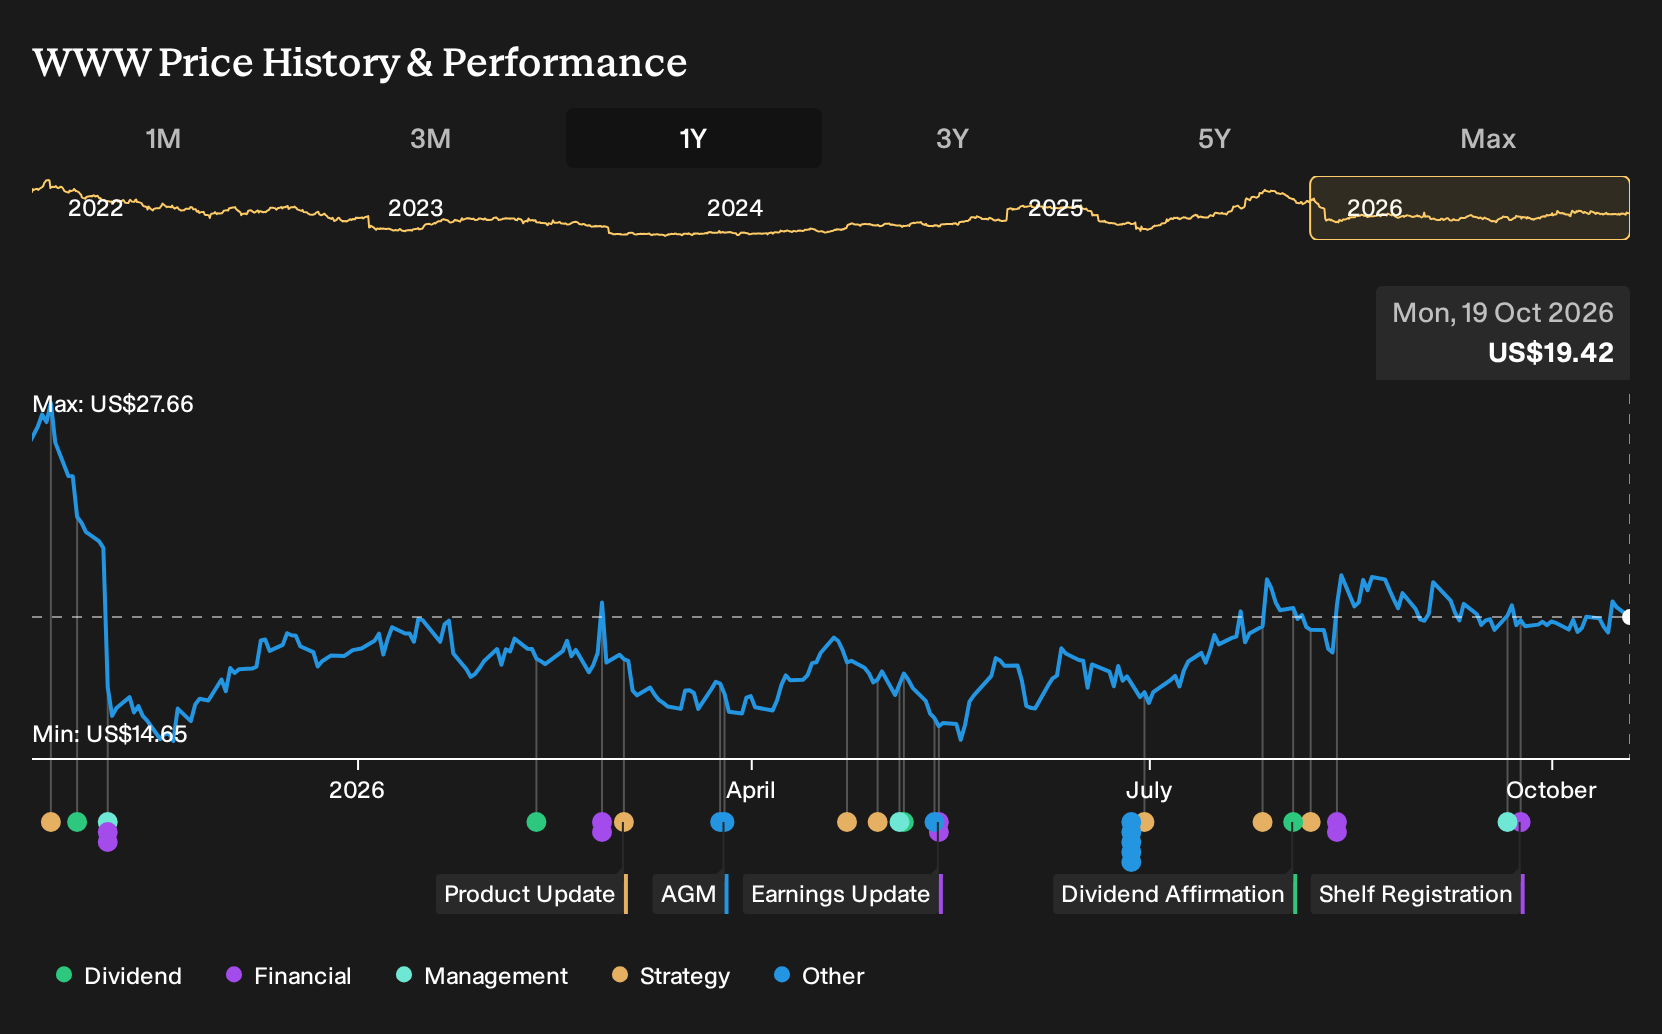
- Wolverine World Wide raised its outlook after reporting stronger recent revenue performance from key brands Merrell and Saucony, with management providing guidance that points to ongoing sales growth and better operating margins in the context of tariff and macro pressures.
- The sharper focus on higher performing labels within Wolverine World Wide's portfolio highlights how brand mix and category positioning can reshape the earnings profile even when broader consumer conditions remain challenging.
- We will now see how Wolverine World Wide's investment narrative could be influenced by stronger Merrell and Saucony momentum and guidance.
Compare Wolverine World Wide's brand-driven recovery with other consumer stocks showing resilient demand using the curated 35 high quality undervalued stocks list.
Wolverine World Wide Investment Narrative Recap
To own Wolverine World Wide, you need to believe the portfolio can keep leaning into Merrell and Saucony strength while repairing weaker labels, all under a high debt load. The raised outlook tied to those two banners points to a business trying to stabilize earnings quality after a period of softer revenue and free cash flow trends.
The key near term swing factor is whether momentum in outdoor and running offsets wholesale channel risk as retail partners consolidate and reorder more cautiously. The biggest risk is that higher SG&A and marketing to support the brands run into slower demand or heavier promotions, which could stall the recent margin recovery.
The clearest tie to this story is management’s updated guidance, which now assumes continued sales growth and better operating margins helped by Merrell and Saucony. That outlook directly connects to earlier efforts to streamline the portfolio and improve sourcing, logistics, and inventory discipline across Wolverine World Wide.
For you, the question is execution. The business still leans heavily on wholesale distribution and carries meaningful debt, so any stumble on brand demand, tariff costs, or price realization could pressure earnings again. If Saucony and Merrell hold their current trajectory, that guidance becomes a key reference point for how durable the recovery really is.
Wolverine World Wide's current analyst narrative points to revenues of US$2.3b and earnings of US$183.1 million by 2029. This implies forecast revenue growth of 5.5% per year and an earnings increase of about US$77.5 million from current earnings of US$105.6 million.
Uncover how Wolverine World Wide's fair value indicates a 25% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate take on Wolverine World Wide leans hard into Saucony and Merrell as a catalyst. The most optimistic analysts were already penciling in 6.2% annual revenue growth and earnings of about US$183.8 million by 2029. You can now ask whether this fresh guidance strengthens that upbeat view or forces those forecasts to be revisited.
Explore 3 other Wolverine World Wide fair value estimates, including one that suggests up to 63% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Wolverine World Wide research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wolverine World Wide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wolverine World Wide's overall financial health at a glance.
Looking For More Investment Ideas Beyond Wolverine World Wide?
If the Wolverine World Wide story has you thinking about portfolio upgrades, it can help to line it up against other companies with different risk and return profiles using the Simply Wall St Screener.
- For investors who want quality on sale, compare Wolverine World Wide with a broader group of resilient businesses trading below their estimated worth using the 35 high quality undervalued stocks.
- If capital preservation matters as much as upside, filter for companies with steadier fundamentals and lower risk profiles through the 32 resilient stocks with low risk scores.
- For readers looking for under-followed opportunities, scan a curated universe of lesser-known companies with solid fundamentals using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com