


Strategic Gaming Management’s acquisition of Sunland Park Racetrack & Casino and the related sale leaseback of the property to Gaming and Leisure Properties (GLPI) puts fresh attention on how this real estate owner structures cash flow with gaming tenants.
Against that backdrop, Gaming and Leisure Properties’ share price of US$38.82 reflects a year where short-term momentum has softened, with the 90-day share price return down 12.78% and the 1-year total shareholder return down 7.50%. At the same time, the 3-year and 5-year total shareholder returns of 5.66% and 9.14% point to a steadier long-run record.
Scan how Gaming and Leisure Properties compares with other real estate operators by reviewing a curated set of list of solid balance sheet and fundamentals (25 results) that also lean on steady rental cash flows.
Gaming and Leisure Properties has a long-term record of collecting rent from gaming operators on triple net terms. After the Sunland Park deal and a softer share price, is that resilience already fully reflected in US$38.82 or not yet?
Price-to-Earnings of 11.7x: Is it justified?
Gaming and Leisure Properties changes hands at a P/E of 11.7x, while our DCF work and peer checks both suggest the stock may be priced below what its cash flows and earnings profile imply.
The P/E ratio compares the current share price to annual earnings per share. For a real estate owner like Gaming and Leisure Properties that leans on contracted rental income, this measure gives a quick sense of how much investors are paying for each dollar of profit generated from its US$1.7b investment property portfolio.
On this yardstick, the gap is wide. The business is described as "good value" against multiple reference points, with its 11.7x P/E level well below the North American Specialized REITs industry average of 25.8x and also below a 19.1x peer average. The internal fair P/E estimate of 32.2x is far higher again. This points to a level the market could move towards if sentiment around Gaming and Leisure Properties’ earnings and balance sheet risk changed materially.
Explore the SWS fair ratio for Gaming and Leisure Properties.
Result: Price-to-Earnings of 11.7x (UNDERVALUED)
Still, Gaming and Leisure Properties faces real pressure points, including tenant concentration in gaming and any shift in regulation that could challenge rental coverage and deal activity.
Find out about the key risks to this Gaming and Leisure Properties narrative.
Another view on Gaming and Leisure Properties’ value
The earlier P/E work suggests Gaming and Leisure Properties looks inexpensive. A second lens, the SWS DCF model, goes further. It estimates future cash flows support a value of $98.82 per share, well above the current $38.82 price, which points to a deeper undervaluation signal.
That kind of gap cuts both ways for investors. It can mark potential upside if the cash flow profile holds, or it can highlight how sensitive valuation is to changes in assumptions about rent coverage, refinancing and deal activity. The real question is whether you trust the cash flows that sit underneath the model.
Look into how the SWS DCF model arrives at its fair value.
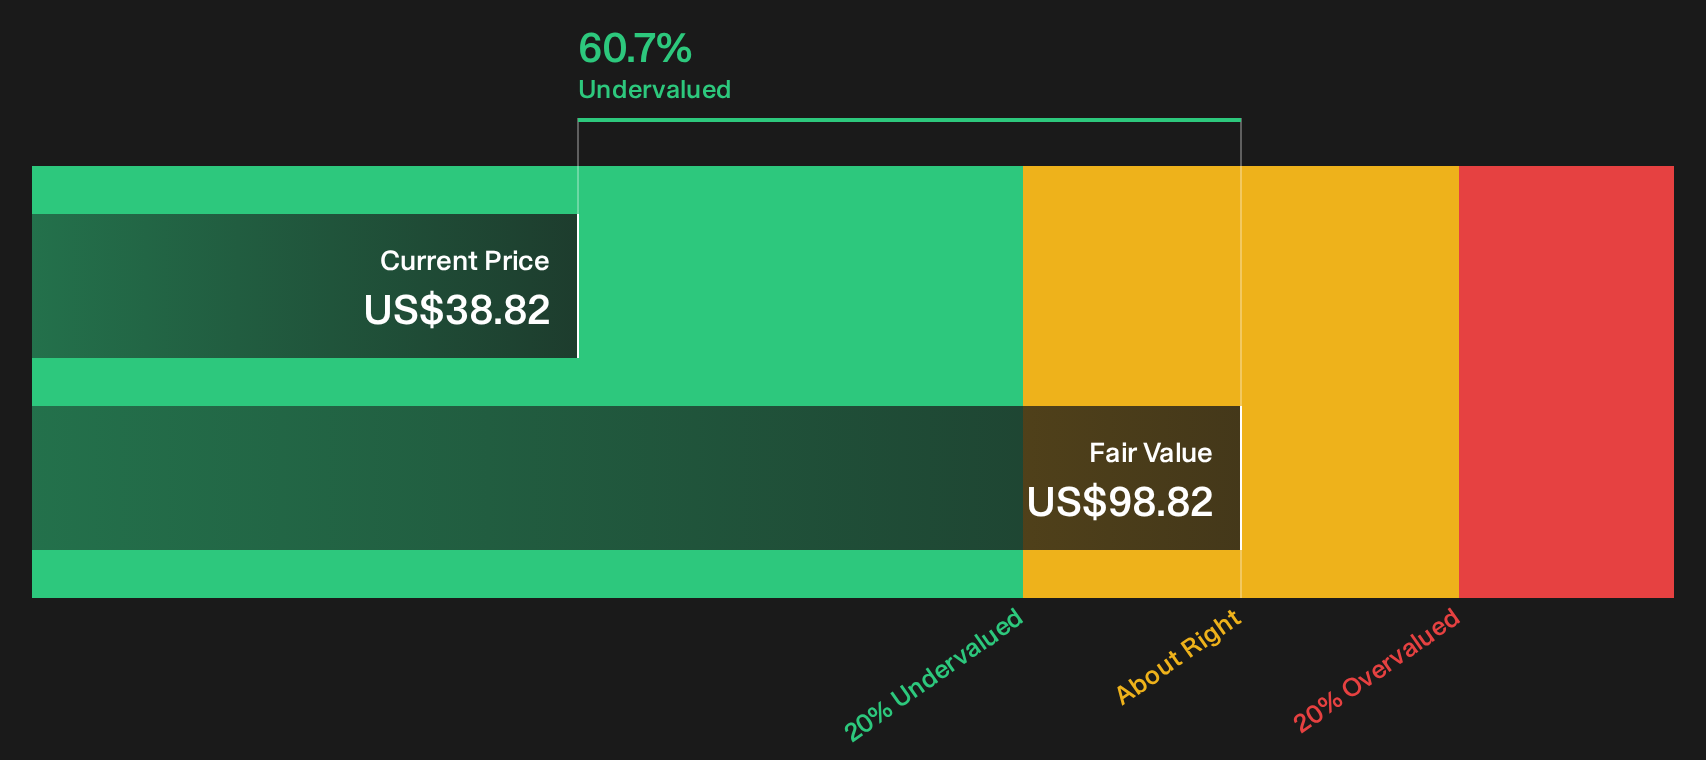
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Gaming and Leisure Properties for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Gaming and Leisure Properties so far. If you want to act before sentiment shifts again, consider weighing the concerns against the potential upside by reviewing the 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond Gaming and Leisure Properties?
If you stop at Gaming and Leisure Properties, you risk missing other opportunities that fit your style, your risk tolerance, and your income goals.
- Target potential mispriced opportunities by scanning a focused list of 35 high quality undervalued stocks that pair solid fundamentals with appealing entry points.
- Build a steadier income stream by zeroing in on 8 dividend fortresses that combine higher yields with resilient business models.
- Protect your downside by starting with 32 resilient stocks with low risk scores that screen for stronger balance sheets and more controlled risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com