


Twist Bioscience has seen its share price move sharply over recent years, which puts a spotlight on a simple question for you as an investor. Is the current valuation of the stock supported by the sales the business is generating today and what the market expects those revenues to become?
- Over the past 3 years, Twist Bioscience has delivered a very large share price gain of around 7x. This raises the stakes on whether the underlying sales justify that kind of move.
- The company is highlighted as a key player in the growing biofoundry-as-a-service market. This can shape how investors think about its potential revenue trajectory and the price placed on each dollar of sales.
- Your read on Twist Bioscience is one view; the desks covering it have another. See what analysts think Twist Bioscience's shares could be worth.
The issue now is whether the stock price around US$139.77 is aligned with the company’s sales when judged against a Fair Ratio benchmark.
If you are weighing Twist Bioscience against other ways to play this theme, it can help to compare it with 33 healthcare AI stocks.
Does Twist Bioscience Look Pricey on Sales?
P/S fits Twist Bioscience because the business is still loss making and investors are effectively paying for revenue and the promise of future cash flows rather than current profits.
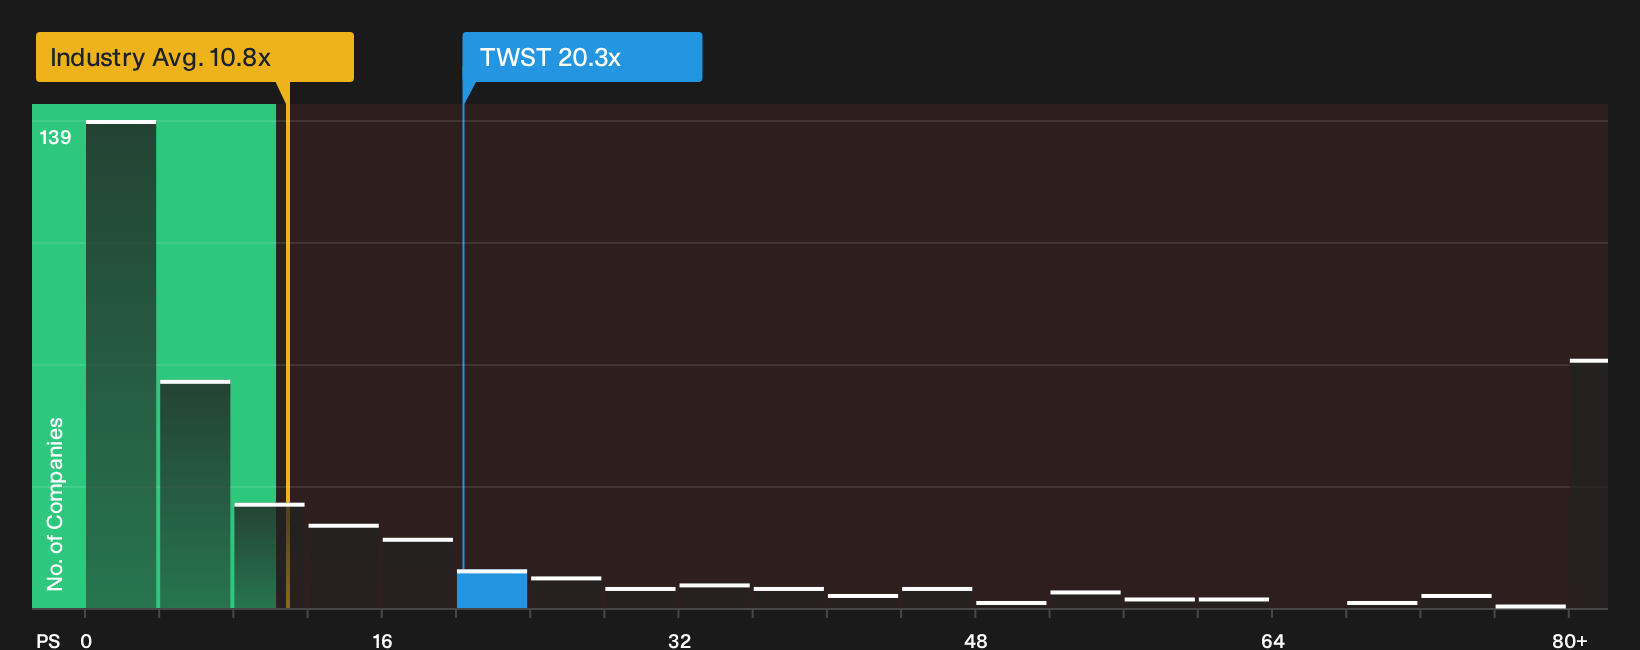
On this lens, the stock trades on a P/S ratio of about 20.3x, which is much higher than the Biotechs industry average of roughly 10.8x and also above the peer group around 12.8x. The Fair Ratio, which reflects what might be paid for each dollar of sales given Twist Bioscience’s growth profile, profitability path, size and risk, sits below the current P/S so the shares screen overvalued on this framework. Because the biofoundry as a service market is being highlighted for rapid expansion and AI automation, the current premium P/S suggests investors are already paying up heavily for that story.
For you as a shareholder or potential buyer, that gap between the present 20.3x sales multiple and the benchmark raises the bar for how much future revenue quality and scale Twist Bioscience needs to deliver for the share price to look justified on this single metric. Explore the numbers behind Twist Bioscience's P/S valuation.
The Twist Bioscience Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for Twist Bioscience leaves off. They spell out which combinations of future growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. Each narrative anchors a fair value estimate to a particular story about Twist Bioscience's potential catalysts and key risks, so you can see over time which version of events is actually unfolding.
Community views on Twist Bioscience split between those who see AI driven demand and margin progress as underappreciated and those who think the current premium already bakes in too much success.
Bull case: 15% undervalued
"Diversification across multiple end markets and geographies, coupled with strong underlying industry trends like AI-driven drug discovery and global genomics market expansion, provides resilience against market cycles..."
Discover why this Narrative puts Twist Bioscience at 15% undervalued.
Bear case: 111% overvalued
"The increasing commoditization of DNA synthesis and next-generation sequencing services, driven by rapid advancements in AI-driven protein design and DNA manufacturing, threatens to erode Twist Bioscience's technological differentiation..."
Explore why this Narrative puts Twist Bioscience at 111% overvalued.
One more Twist Bioscience signal worth checking before you move on
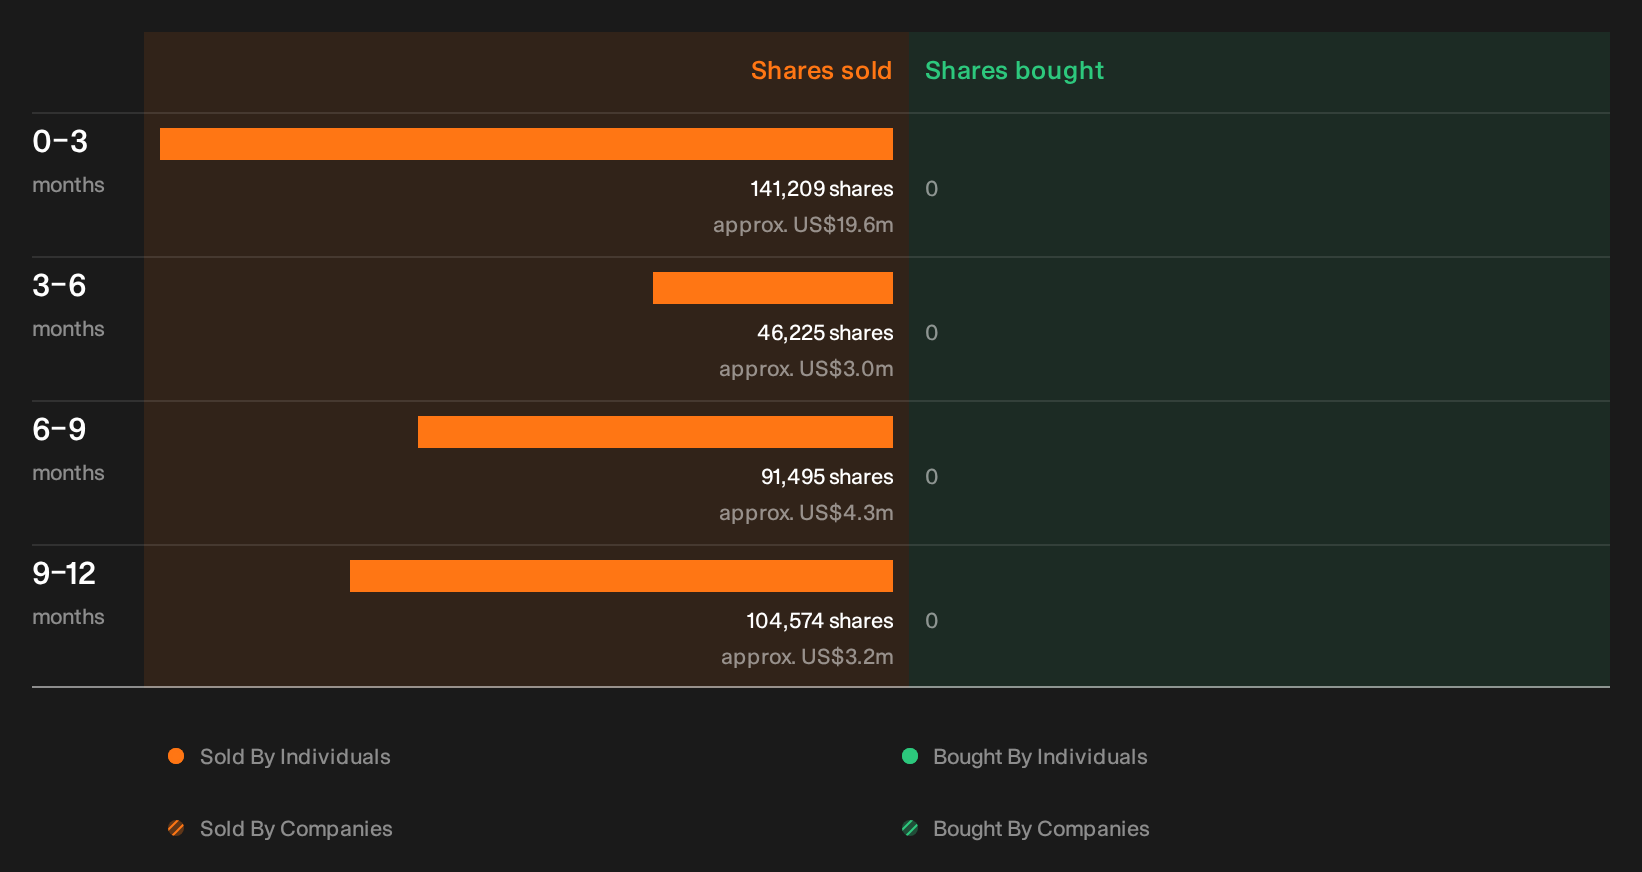
Price tags and growth stories tell only part of it, because recent trading by people inside Twist Bioscience has been flagged by our checks and the specific sellers, sizes and possible read through are still for you to review. See the recent insider selling flagged for Twist Bioscience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com