


- PayPal Holdings (NasdaqGS: PYPL) is again the focus of takeover chatter after a new unconfirmed acquisition report on 20 October 2026.
- The reported suitor is described as a major West Coast technology group that is said to be weighing an all stock offer.
- Any all equity proposal would give PayPal investors exposure to the buyer's shares rather than a cash payout for their holdings.
- This fresh all stock acquisition rumor around PayPal only tells part of the story on the business and its risks. Our analysis turns up 1 major warning sign for PayPal Holdings as well.
Broader interest in large payments platforms points to a wider theme in digital finance that many investors explore through 35 high quality undervalued stocks.
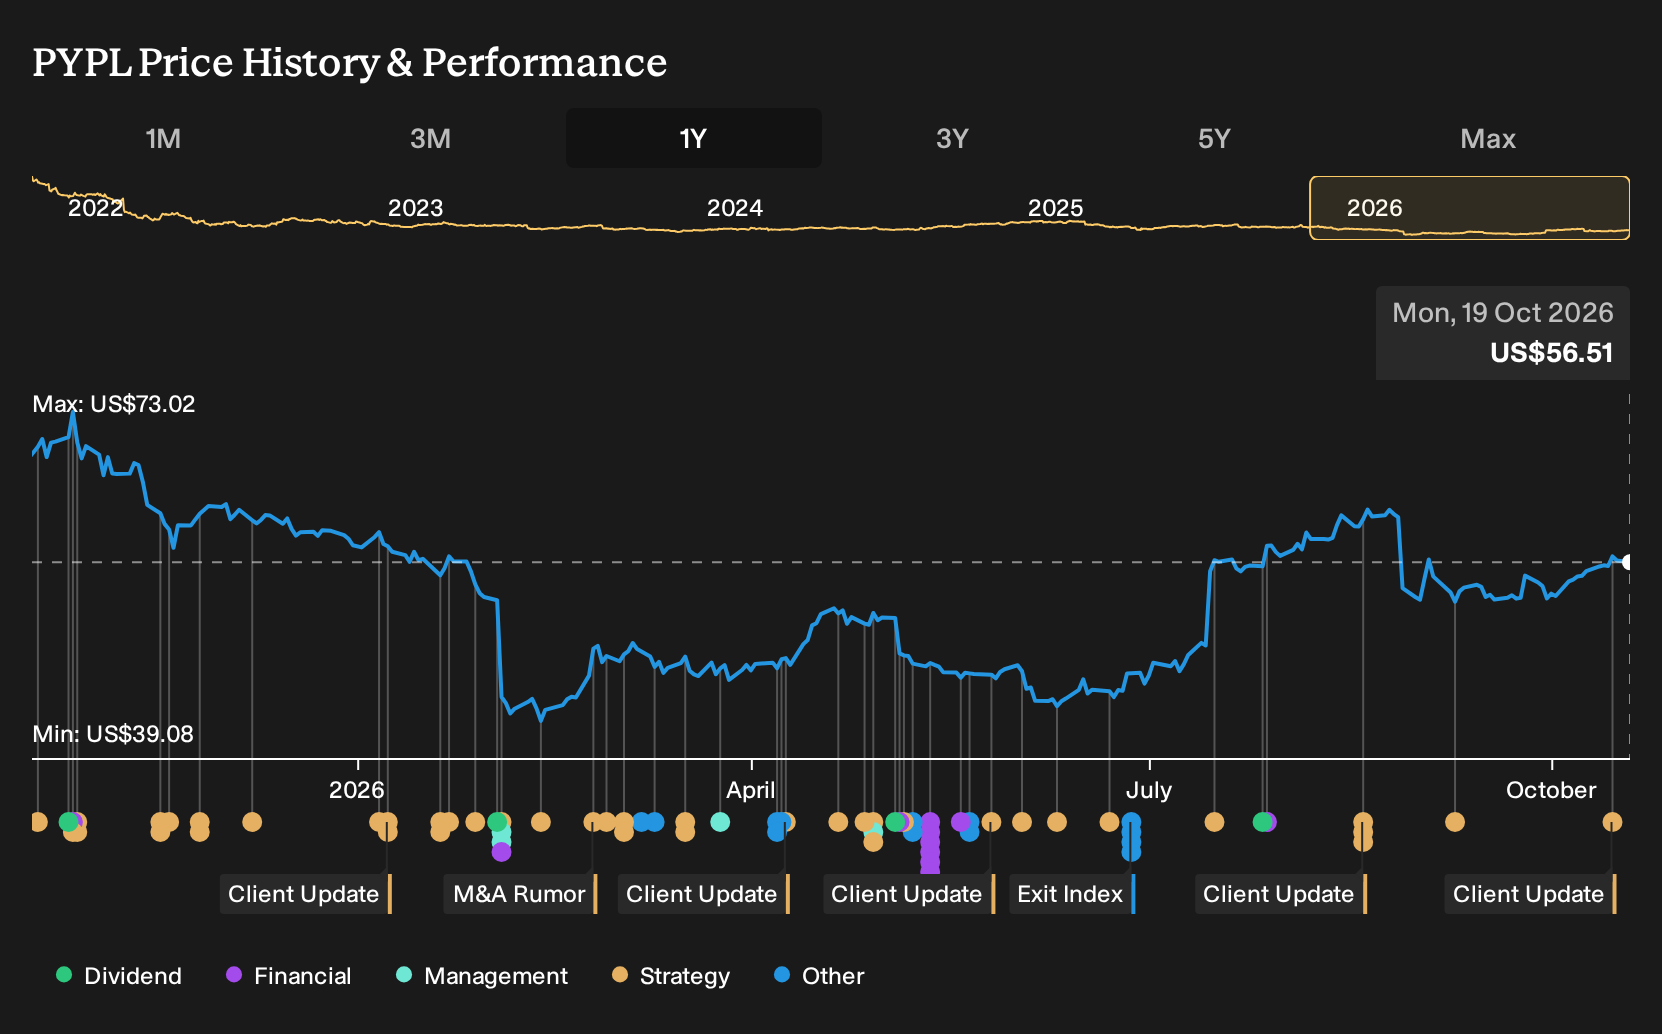
PayPal Holdings runs a global payments platform that connects consumers and merchants, so any potential buyer is not just looking at a US$48.3b diversified financial company, but at infrastructure that sits inside thousands of online checkouts and digital wallets worldwide.
See which insiders are buying and selling PayPal Holdings following this latest news.
What renewed PayPal takeover chatter really flags for investors
For PayPal Holdings investors, the latest talk of an all stock approach reads more like a sentiment check than a reset of the Narrative. Interest from a large West Coast tech buyer would underline that third parties still see value in PayPal’s payments rails, data and newer services, even while one broker recently downgraded the shares and analysts on average expect earnings to edge down over the next three years. The bigger question for you is whether a potential suitor is reacting to the same mix shift that the existing Narrative focuses on, where financial services, Venmo, Braintree and agentic commerce deals like Glance play a larger role than legacy branded checkout.
See how these catalysts shape PayPal Holdings' path to a $56.92 fair value.
The cleanest way to track whether this renewed interest lines up with fundamentals is to watch the Q3 2026 earnings release on 27 October and focus on one thing: management’s update on transaction margin mix and progress toward the US$1.5b cost savings program that underpins the current analyst view on PayPal.
One important PayPal Holdings question this article has not answered
Everything here has focused on what PayPal Holdings looks like today, yet analyst models already sketch where this business could be several years from now, and that path is the missing piece. See where analysts expect PayPal Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com