


Recent Price Performance And Business Scale
Hermès International Société en commandite par actions (ENXTPA:RMS) has seen mixed recent performance, with the share price close to €1,337 after a small daily move and a modest gain over the past week.
Over the past month the stock has inched higher, while the past 3 months show a decline of about 20%. Over the year to date and past year, returns have also moved lower, contrasting with a modest gain over 5 years.
The group reports annual revenue of about €16.1b and net income of roughly €4.5b, supported by annual revenue and profit growth rates in the mid to high single digits based on the latest figures provided.
Hermès International Société en commandite par actions generates sales across several regions, with the Asia Pacific region excluding Japan contributing the largest share, followed by the Americas, Europe excluding France, France, Japan, and the Middle East.
- Asia Pacific excluding Japan revenue of €6,661m
- Americas revenue of €3,205m
- Europe excluding France revenue of €2,439m
- France revenue of €1,588m
- Japan revenue of €1,574m
- Middle East and other regions revenue of €665m
The business trades with a market value of about €140b, which sets a high bar for expectations and makes the quality and durability of its earnings stream an important focus for investors assessing Hermès International Société en commandite par actions today.
Hermès International Société en commandite par actions has seen momentum fade, with a 90 day share price return that declined about 20% and a year to date share price return that fell roughly 36%, while the 1 year total shareholder return also declined about 39%.
Scan how Hermès International Société en commandite par actions compares with other consumer stocks that have pulled back yet still show solid fundamentals using our hand picked 199 high quality undervalued stocks as a starting universe.
Hermès International Société en commandite par actions combines a powerful brand and sizeable earnings base with a share price that has pulled back sharply. Does that recent slide leave the stock attractively valued or still expensive?
Most Popular Narrative: 35% Undervalued
Hermès International Société en commandite par actions closed at €1,337, while the most followed narrative sets fair value at €2,067.13, so the key question is whether the long term expansion plan and cash position can justify that gap.
The company’s heavy investment cycle to at least 2026, with operating capex of about €1.2b in 2025 and a guided €1b in 2026 for workshops and large flagship stores, creates room for higher contribution from underrepresented métiers such as tableware and watches, which can shift mix and support earnings and cash flow per share as these assets mature.
See why 4 investors see Hermès International Société en commandite par actions as 35% undervalued.
Result: Fair Value of €2,067.13 (UNDERVALUED)
Still, this bullish Hermès International Société en commandite par actions story depends on risks staying contained, including conflict driven Middle East sales volatility and any sustained slump in high margin tourist spending across Europe.
Find out about the key risks to this Hermès International Société en commandite par actions narrative.
Another View: What Multiples Say About Hermès International Société en commandite par actions
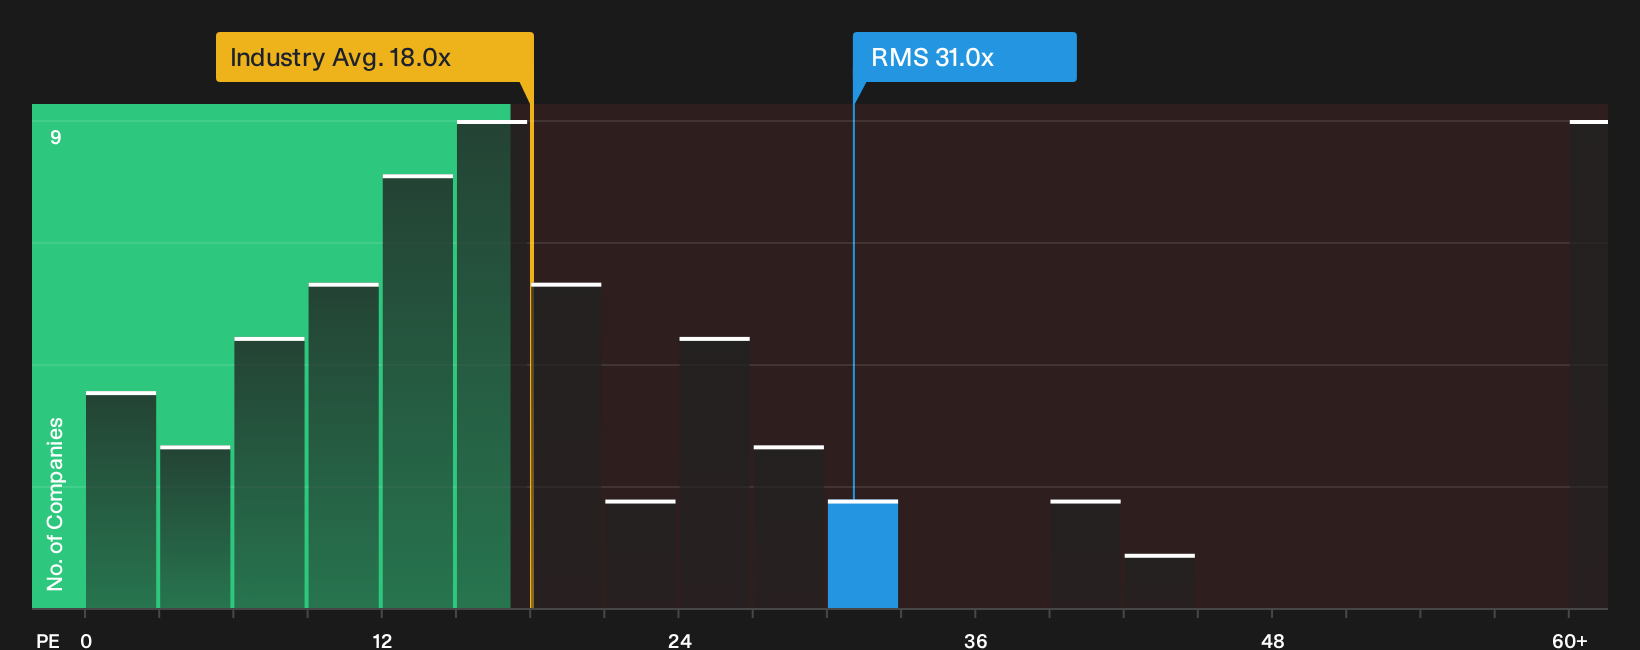
The bullish fair value of €2,067.13 leans heavily on optimistic analyst forecasts. A different lens uses the current P/E of 31x. That is richer than both European Luxury at 18x and peers at 26.3x, and also above a fair ratio of 19x. This points to valuation risk if sentiment cools.
For investors weighing that premium, the key question is whether Hermès International Société en commandite par actions can deliver enough earnings progress to justify paying such a marked step up in multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Hermès International Société en commandite par actions story feels mixed to you, that is the point; the debate is live and real. Take a closer look at what the current optimism is based on by reviewing the 3 key rewards.
Looking For More Investment Ideas Beyond Hermès International Société en commandite par actions?
If Hermès International Société en commandite par actions leaves you on the fence, use this moment to widen your watchlist and pressure test your next moves.
- Target resilient potential by scanning companies that combine strong fundamentals with solid balance sheets through our focused list of solid balance sheet and fundamentals (202 results).
- Hunt for mispriced quality and see which businesses screen as compelling on cash flow and balance sheet strength with the 199 high quality undervalued stocks.
- Spot future market favorites early by filtering for financially sound stocks that still fly under most radars using the 613 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com