


Resonac Holdings (TSE:4004) is back in focus after management outlined a plan to direct more than half of operating cash flow into growth areas, particularly semiconductor materials and new capacity.
That cash allocation plan lands at a sensitive moment for the share price. Resonac Holdings has pulled back sharply in the last week, with the 1-day share price return down 10.8% and the 7-day share price return down 14.6%. At the same time, the year-to-date share price return is 105.5% and the 1-year total shareholder return is 140.7%, which points to strong longer term momentum even as near term sentiment cools around how much growth is already reflected in the current ¥13,875 level.
Scan companies pursuing similar cash heavy expansion as Resonac Holdings by reviewing the hand picked 55 AI infrastructure stocks powering chip manufacturing and data center build outs.
Bulls see Resonac Holdings using that cash engine to compound value in higher margin semiconductor materials. Bears see a sharp run up that leaves little cushion. Which case do the current valuation markers lean toward next?
Most Popular Narrative: 50% Undervalued
Resonac Holdings closed at ¥13,875 while the most referenced narrative anchors fair value at ¥28,000. The debate now centers on whether earnings quality and portfolio reshaping can bridge that gap.
The projected swing in the Chemicals segment from a core operating loss of JPY 5.5 billion in 2025 to an expected JPY 8 billion profit in 2026, driven by higher graphite electrode volumes and rationalization, could add a fresh earnings contributor that is not yet reflected in how investors value Resonac Holdings’ non semiconductor businesses.
See why 2 investors see Resonac Holdings as 50% undervalued.
Result: Fair Value of ¥28,000 (UNDERVALUED)
Still, the bullish story for Resonac Holdings can unravel quickly if restructuring sparks more large one off losses or if elevated leverage restricts reinvestment into semiconductor materials.
Find out about the key risks to this Resonac Holdings narrative.
Another View: What Multiples Say About Resonac Holdings
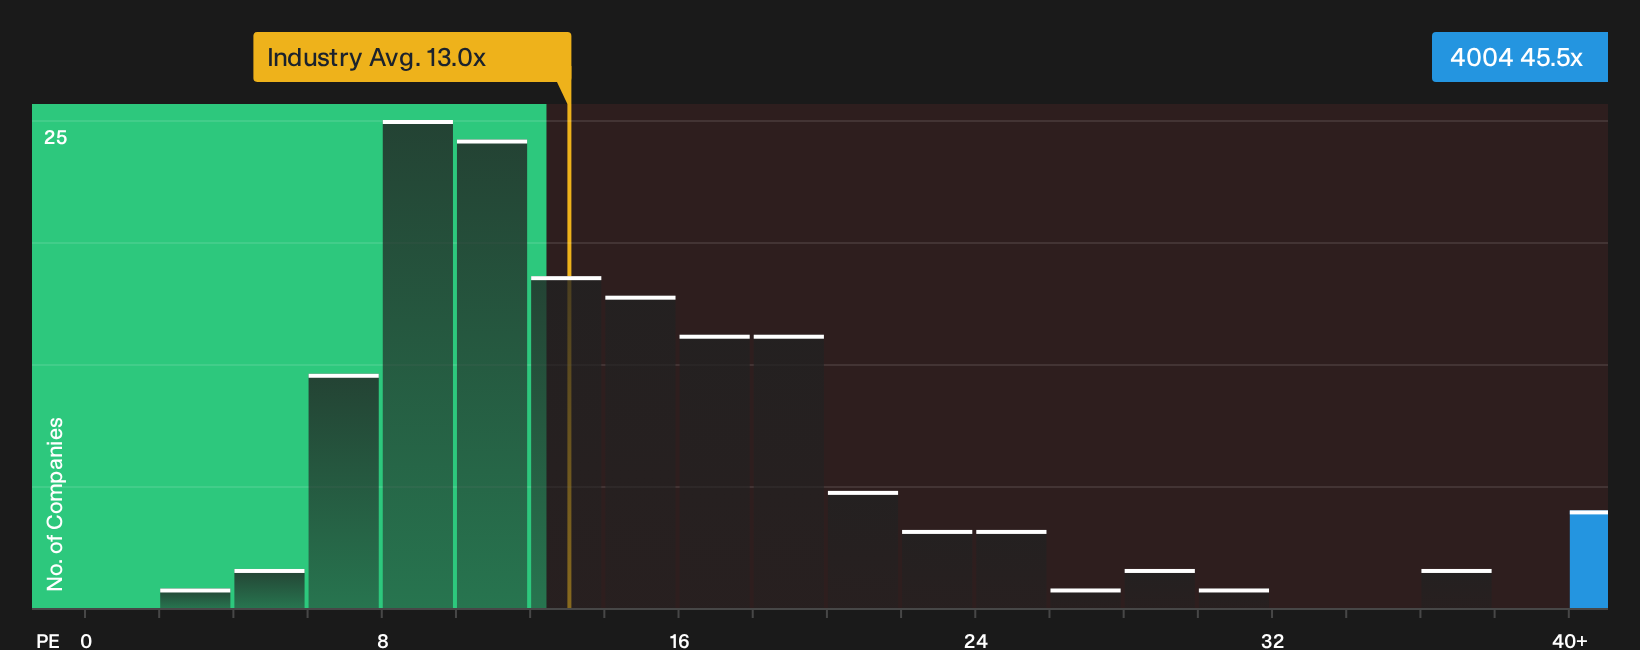
Resonac Holdings screens as cheap on a fair value estimate, yet its 45.5x P/E is more than double both the peer average of 20.8x and the JP Chemicals industry at 13x. The fair ratio sits lower at 28.3x, which raises a simple question for investors: Is this a margin story or a valuation stretch waiting to compress?
For a closer look at how that earnings multiple stacks up against history and peers, and what that might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages or clear opportunity? If you move quickly and review the full data for Resonac Holdings yourself, you can weigh the 1 or more highlighted risks against the 1 or more potential upsides by starting with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Resonac Holdings?
Resonac Holdings might already be on your screen, but your next strong idea could be sitting in plain sight if you widen the search with a few focused filters.
- Target resilient income by reviewing companies in the 30 dividend fortresses that aim to pair higher yields with balance sheets built to handle tougher conditions.
- Surface potential bargains early by scanning the 73 high quality undiscovered gems where solid fundamentals have not yet attracted broad market attention.
- Dial down portfolio volatility by filtering through the 20 resilient stocks with low risk scores and focus on businesses with steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com