


Quanta Services earnings setup and recent performance
Quanta Services (PWR) is back in focus after reporting strong second quarter 2026 results, highlighted by a record backlog of about $53b tied to power grid and infrastructure work.
The company is also approaching its third quarter 2026 report with an Earnings ESP of 2.66% and a Zacks Rank of 3, following four straight quarters of earnings beats that averaged a 17% surprise.
Recent trading has cooled after a strong run, with Quanta Services’ share price down 2.1% over the last day and 11% over the past week, yet still showing a 40.7% year to date share price return and a five year total shareholder return of 417.0%. This indicates sustained longer term momentum, even as shorter term moves suggest some investors are reassessing near term risk and growth expectations around its record backlog and upcoming earnings.
Scan beyond Quanta Services and review other grid and infrastructure plays on our curated 42 power grid technology and infrastructure stocks to see how this earnings setup compares.
After a sharp multi year climb and a recent pullback, Quanta Services now presents a simple question to new investors: Does this backlog heavy story still offer enough upside to justify the current valuation setup?
Most Popular Narrative: 13% Undervalued
Quanta Services closed at $618.41 while the most followed narrative pegs fair value at $710. That gap frames the bullish backlog story against a valuation that still assumes a long runway of projects tied to grid upgrades, data centers, and large-load infrastructure.
The long case is simple: Quanta sits at the intersection of several unusually durable spending waves: aging grid replacement, transmission expansion, utility hardening, manufacturing reshoring, renewable interconnection, and AI-driven power demand. The company’s scale, labor base, customer relationships, and expanding “total solutions” model make it one of the few contractors able to execute very large, complex programs.
See why 70 investors see Quanta Services as 13% undervalued.
Result: Fair Value of $710 (UNDERVALUED)
Still, the Quanta Services story can crack if large AI and grid projects are delayed, or if execution stumbles trigger a sharp reset in its premium multiple.
Find out about the key risks to this Quanta Services narrative.
Another view on Quanta Services valuation
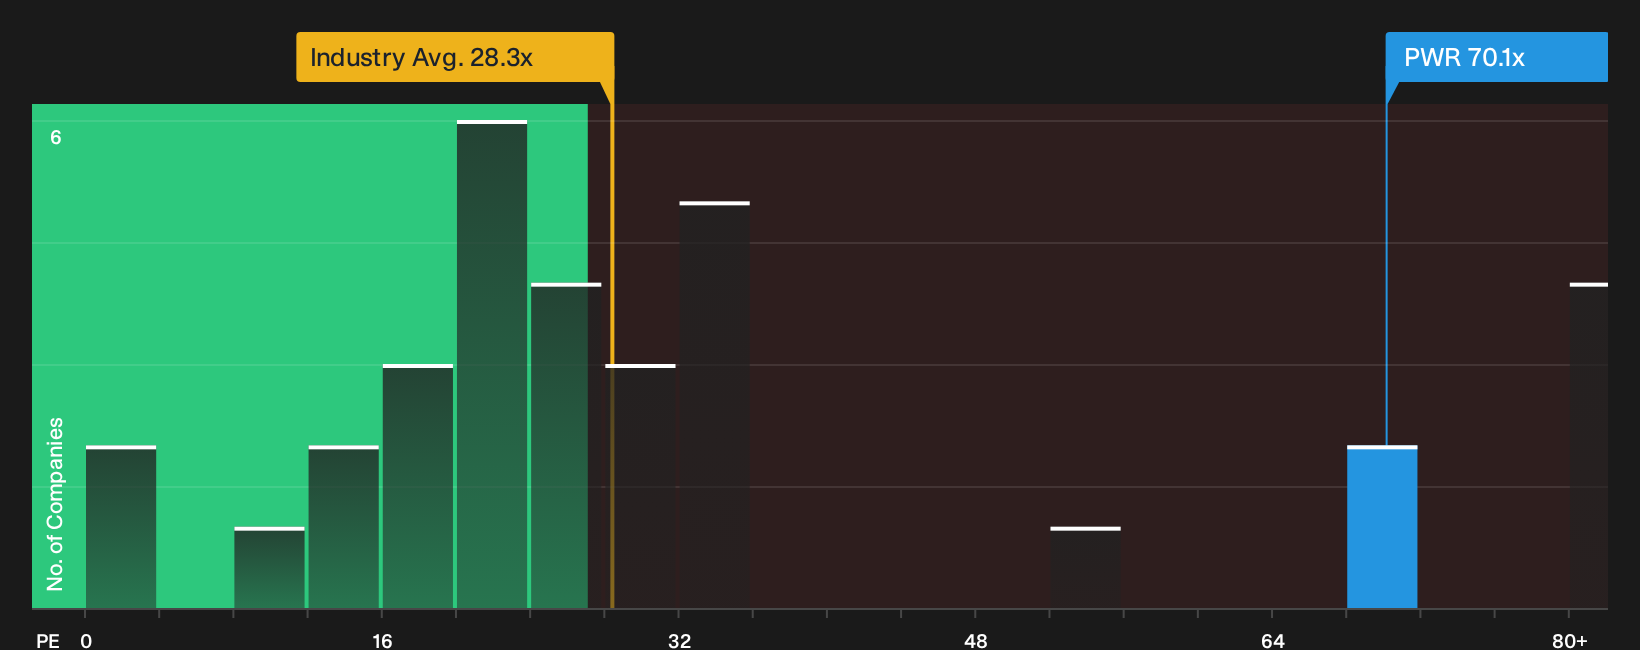
The first narrative pegs Quanta Services at $710 per share, yet its current P/E of 70.1x tells a very different story. The Construction industry sits at 28.3x, peers average 29.6x, and a fair ratio estimate is 38.3x. That gap points to meaningful valuation risk if sentiment cools.
For investors weighing that premium against the backlog story, the key question is whether Quanta Services is priced for too much perfection or whether the market is still underestimating how long this grid buildout can run before the multiple normalizes.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Quanta Services so far. If you care about both risk and reward, move quickly and test the numbers yourself with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Quanta Services?
Do not stop your research with Quanta Services. Broaden your watchlist with other targeted ideas sourced directly from the Simply Wall Street Screener.
- Target potential mispriced opportunities by scanning a curated pool of quality companies using the 35 high quality undervalued stocks.
- Strengthen your focus on capital preservation by filtering for businesses that score well on resilience and stability through the 32 resilient stocks with low risk scores.
- Spot under-the-radar prospects with solid fundamentals before they appear on everyone else's radar by using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com