


Meta Platforms has spent the past few years reshaping itself around artificial intelligence while its share price has moved sharply. This leaves a straightforward question for you as an investor: Is the current valuation of Meta stock adequately supported by the earnings the business is generating today and is expected to produce over time?
- Over the past 3 years, Meta has delivered a total shareholder return of 126.8%, so any view on the stock now largely comes down to whether that gain is in line with the earnings power behind it.
- Management has signalled a willingness to commit as much as US$200b to AI infrastructure and related projects, which can reshape expectations for future profit streams and the timing of cash flows that underpin what investors are prepared to pay for its earnings.
- There is a second opinion on Meta Platforms worth weighing. See what analysts think Meta Platforms's shares could be worth.
For investors, the debate is whether Meta's current share price, after that multi year run and heavy AI spending plans, still lines up with what its earnings justify.
If you are weighing Meta's AI spending against its earnings, it can help to compare that story with other large AI infrastructure and platform plays using the 55 AI infrastructure stocks.
Does Meta Platforms Look Undervalued on Earnings?
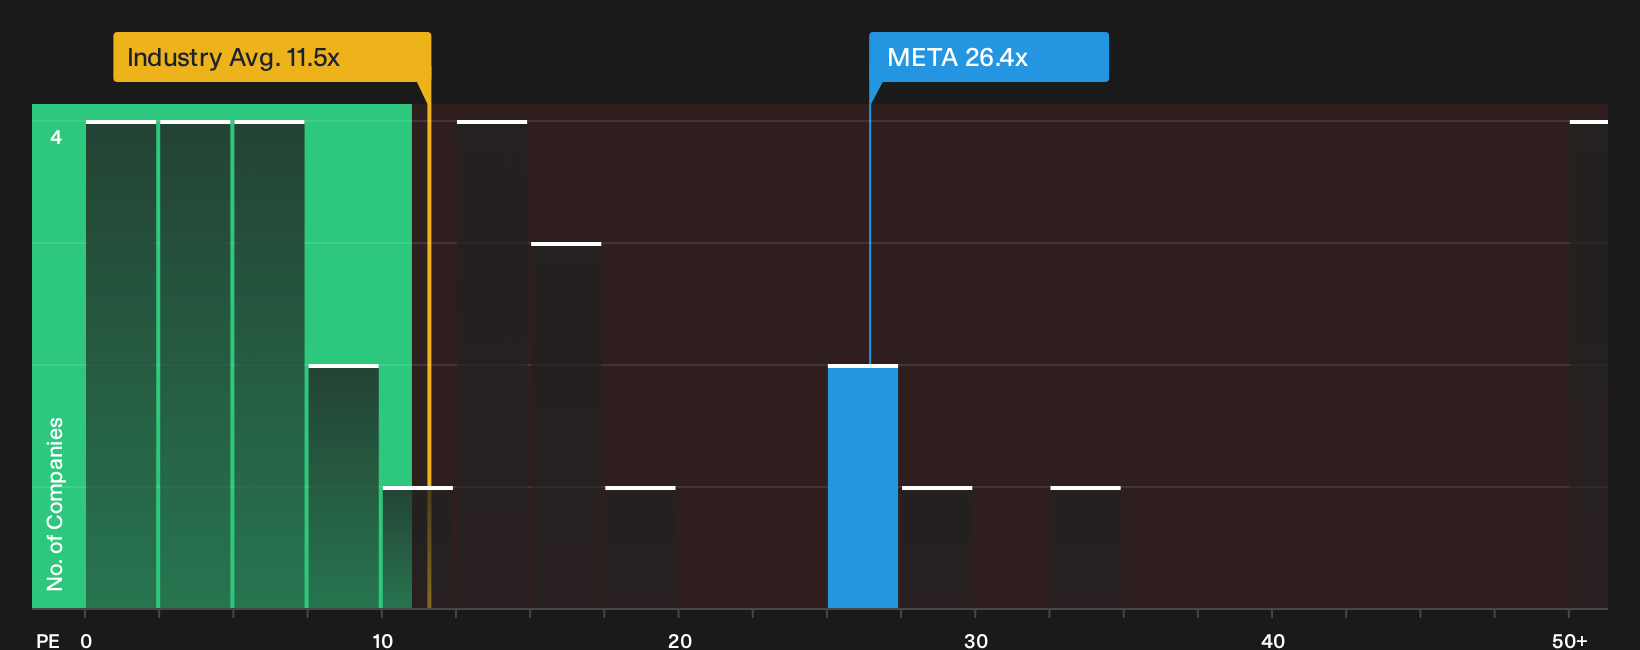
The P/E ratio fits Meta Platforms because earnings still anchor how investors price its ad and social media engine, even as AI spending ramps. Meta trades on a P/E of 26.4x, almost in line with the 26.7x peer average and materially higher than the 11.5x industry figure for Interactive Media and Services. That combination suggests the market is already treating Meta more like a large platform peer group than a typical sector player. It also indicates a clear earnings premium to the broader industry.
Because the P/E that would usually be expected for Meta given its size, margins, growth profile and risk comes out higher than today’s 26.4x, the model reads the stock as undervalued on this yardstick. Despite the plan to commit up to US$200b to AI infrastructure, which could weigh on reported profits in some periods, the current earnings multiple still screens below that tailored benchmark. Explore the numbers behind Meta Platforms's P/E valuation.
The Meta Platforms Narrative: What Would Justify Today's Price?
Simply Wall St Narratives extend the Meta Platforms valuation question by spelling out which future paths for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than it is today, and they sit on the Community page. Rather than a single P/E or model snapshot, each scenario lays out the assumptions sitting behind its own estimate so you can judge those against Meta Platforms' reported results over time.
On Meta Platforms, community views split between AI spend creating durable earnings power and AI spend stretching risk without enough cushion.
Bull case: 13% undervalued
"Meta Platforms foundational investments in AI infrastructure, including 2026 capital expenditure guided at US$130 to US$145b, a 1 GW data center venture and large contractual commitments for compute, are feeding into recommendation quality and ad performance..."
Discover why this Narrative puts Meta Platforms at 13% undervalued.
Bear case: 20% overvalued
"But you can't look at these numbers in isolation, because the man running the place has decided to set $135 billion on fire in 2026 to chase a technology that may or may not work..."
Explore why this Narrative puts Meta Platforms at 20% overvalued.
One more Meta Platforms check before you put the model away
There is one extra angle that can sharpen how you view Meta Platforms, which is what professional analysts think its earnings and cash flows could look like a few years from now. Explore where analysts expect Meta Platforms to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com