


In recent weeks, global markets have experienced notable shifts with major U.S. stock indexes closing mostly lower, driven by a sell-off in AI-related stocks and concerns over inflation pressures. This environment has prompted investors to seek opportunities in value-oriented and defensive segments, highlighting the potential of small-cap stocks as they navigate these dynamic conditions. In this context, identifying undiscovered gems with solid fundamentals becomes crucial for investors looking to capitalize on market rotations and emerging growth opportunities.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
| Bastide Le Confort Médical | 263.37% | 2.00% | -22.93% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
TSK Electrónica y Electricidad (BME:TSK)
Simply Wall St Value Rating: ★★★★★★
Overview: TSK Electrónica y Electricidad, S.A. specializes in infrastructure solutions for energy transition, digitalization, and critical raw material handling industries, with a market capitalization of approximately €766.64 million.
Operations: TSK generates revenue primarily from its Energy Transition and Digitalization segment, contributing €932.85 million, followed by the Handling & Mining segment at €118.66 million. The company has a market capitalization of approximately €766.64 million.
Trading at 68.6% below its estimated fair value, TSK Electrónica y Electricidad seems undervalued. The company's debt to equity ratio has impressively reduced from 343.1% to 85.3% over five years, indicating improved financial health. With a significant one-off gain of €15M impacting recent results and earnings growth of 111% outpacing the industry average, TSK shows strong profitability potential. Recent half-year results highlight sales of €479M and net income soaring to €44M from just €2.8M previously, reflecting robust performance improvements. Additionally, TSK's inclusion in the S&P Global BMI Index suggests growing recognition in the market.

HD Hyundai Energy SolutionsLtd (KOSE:A322000)
Simply Wall St Value Rating: ★★★★★★
Overview: HD Hyundai Energy Solutions Co., Ltd. specializes in the production of solar cells and modules with a market capitalization of ₩1.42 trillion.
Operations: The company generates revenue primarily from its Green Energy Business, amounting to ₩598.62 billion.
HD Hyundai Energy Solutions, a relatively smaller player in the energy sector, has shown impressive financial strides. Over the past year, its earnings surged by 333%, outpacing the Semiconductor industry's growth of 71.9%. The company seems to be trading at a good value, being 50.2% below its estimated fair value. Despite recent volatility in share price over three months, it maintains high-quality earnings and has more cash than total debt. Recent results indicate net income of KRW 30 billion for Q2 2026 compared to KRW 11 billion last year, with basic EPS rising from KRW 1,017 to KRW 2,745.

Nikkiso (TSE:6376)
Simply Wall St Value Rating: ★★★★★☆
Overview: Nikkiso Co., Ltd. operates globally in the industrial, aerospace, and medical sectors with a market capitalization of ¥220.24 billion.
Operations: Nikkiso generates revenue primarily from its industrial sector, contributing ¥153.20 billion, and its medical sector, adding ¥80.65 billion. The company's net profit margin provides insight into its profitability across these sectors.
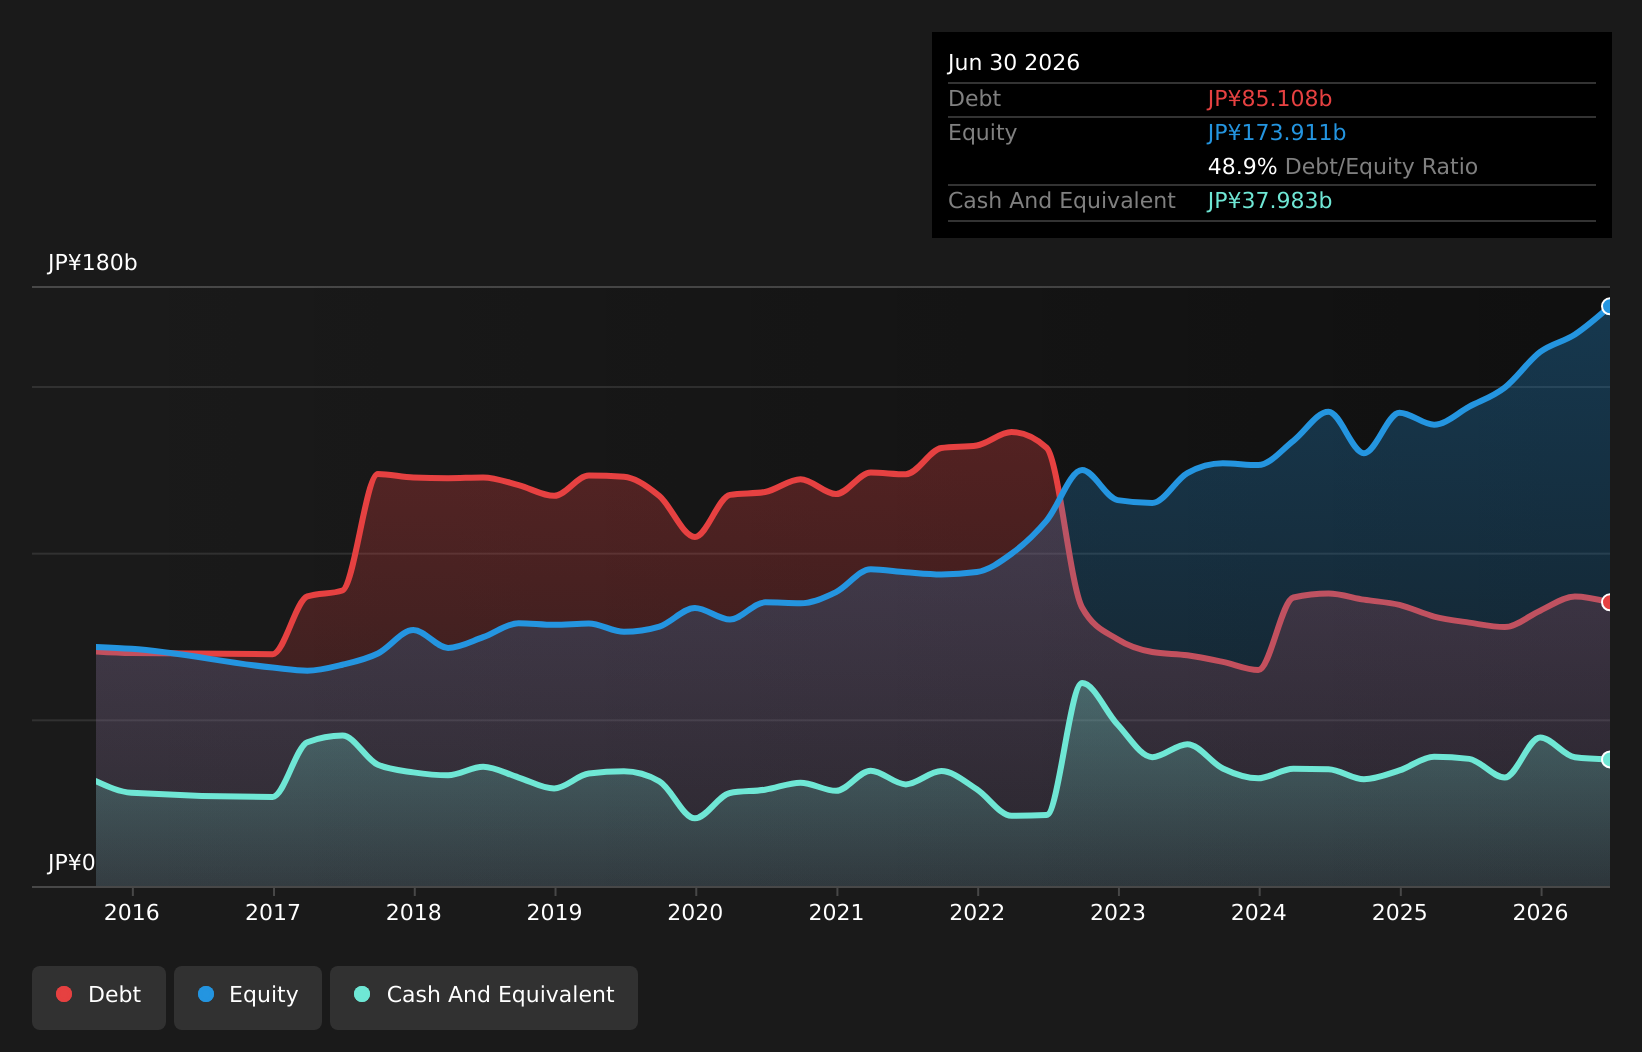
Nikkiso, a company operating in the machinery sector, has shown impressive earnings growth of 144.9% over the past year, significantly outpacing the industry average of 26%. The firm appears to be trading at a compelling value, with its stock priced 66.1% below estimated fair value. Despite this growth, Nikkiso's free cash flow remains negative; however, their net debt to equity ratio has improved from 131.2% to a satisfactory 48.9% over five years. Recent announcements highlight an upward revision in revenue forecasts for fiscal year-end December 2026 and increased dividends from ¥22 to ¥30 per share annually.
Where To Now?
- Unlock more gems! Our Global Undiscovered Gems With Strong Fundamentals screener has unearthed 179 more companies for you to explore.Click here to unveil our expertly curated list of 182 Global Undiscovered Gems With Strong Fundamentals.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com