


- CECO Environmental is being highlighted for benefiting from strong industrial demand for air pollution control, supported by a sizable backlog tied to large natural gas power generation projects and broader emissions regulation.
- An additional angle is how CECO Environmental’s long dated contracted work across power, gas infrastructure and industrial sectors may give the business unusually extended revenue visibility compared with many short cycle equipment peers.
- This article will now explore how CECO Environmental’s industry demand and sizable project backlog could reshape the existing investment narrative.
Scan beyond CECO Environmental and line up other industrial players tied to emissions control and infrastructure spending by using our hand picked list of solid balance sheet and fundamentals (25 results).
CECO Environmental Investment Narrative Recap
To own CECO Environmental, you need to be comfortable with a project-driven story that leans on long-duration contracts in power generation, gas infrastructure, and broader industrial air and water work. The recent focus on strong industrial demand does not fundamentally change that. The main near-term swing factor still looks like how smoothly the record backlog converts into revenue and cash.
On the risk side, the moving pieces have not materially shifted. Execution on large natural gas projects, delays around industrial water work in the Middle East, and the true leverage profile, given reliance on external borrowing rather than customer deposits, remain key pressure points that could weaken the current narrative if they develop unfavorably.
With no fresh company announcements filed alongside this news, the reference point investors keep circling back to is the earlier disclosure of record Q2 2026 orders of US$799 million and a US$1.82 billion backlog that extends through 2029 and 2030. That data supports the idea of unusually long revenue visibility for an equipment-focused industrial group.
For potential catalysts, that same order book across power, gas, and industrial projects is what connects most directly to the current discussion of strong pollution control demand. The key question is whether CECO Environmental can convert that backlog efficiently while integrating Thermon, managing a net income loss of US$30.6 million on US$903.2 million of revenue, and keeping debt service from weighing too heavily on future earnings potential.
CECO Environmental's current narrative points to forecast revenue of US$2.5b and earnings of US$358.9 million by 2029. This assumes revenue growth of 41.0% per year and an earnings swing of roughly US$389.5 million from a net loss of US$30.6 million today to the 2029 consensus figure.
Uncover why CECO Environmental's fair value indicates a 95% potential upside to its current price before enthusiasm around that discount starts to fade.
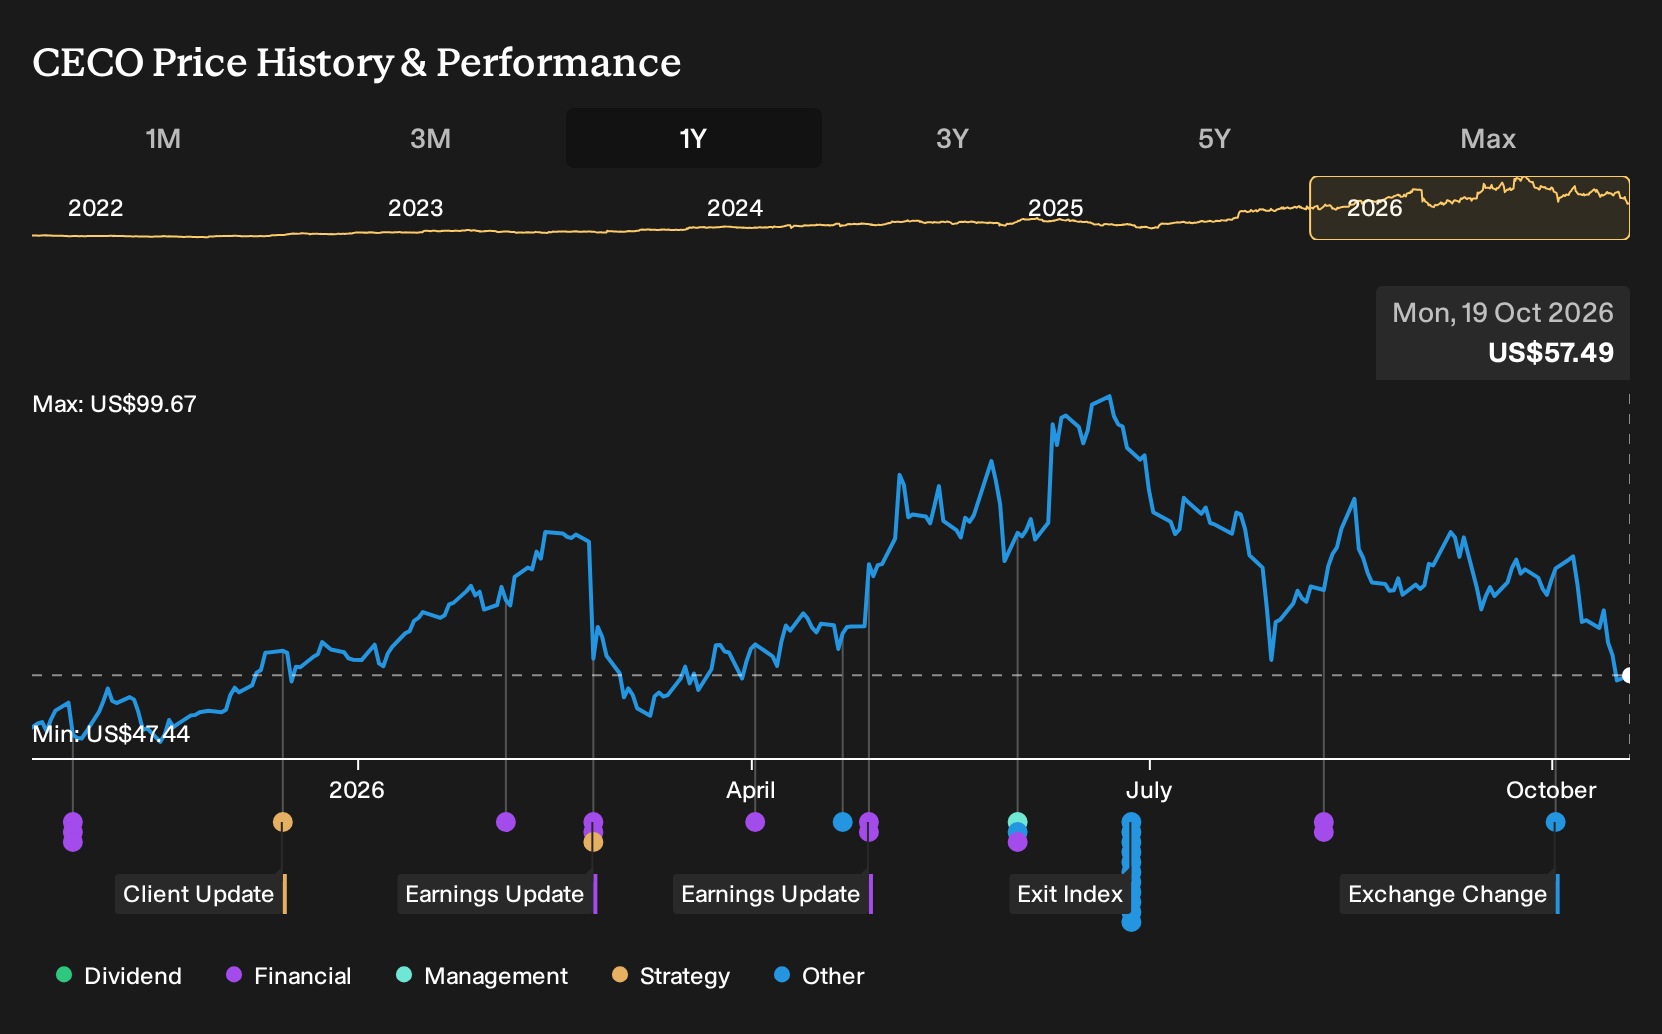
Exploring Other Perspectives
One alternate angle around CECO Environmental focuses less on backlog size and more on how far bullish analysts were stretching expectations before this news. That group was working off revenue of about US$2.3b and earnings of US$284.1 million by 2029. You can treat this optimism as one bookend and test your own view against it.
Explore 3 other CECO Environmental fair value estimates, including one that suggests as much as 126% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CECO Environmental research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CECO Environmental. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CECO Environmental's overall financial health at a glance.
Looking for more investment ideas beyond CECO Environmental?
Once you have a view on CECO Environmental, it can help to widen the lens and compare it with other businesses that fit different risk, income, and balance sheet profiles. The Simply Wall St Screener is built for exactly that kind of side by side work.
- If you want potential income along with capital growth, start by reviewing companies in the 8 dividend fortresses that may offer substantial yield backed by their current fundamentals.
- For readers who care most about balance sheet strength and financial resilience, filter for businesses in the list of solid balance sheet and fundamentals (25 results) to see which ones currently screen well on debt, liquidity, and cash flow coverage.
- If the goal is to find less crowded opportunities, scan through the 20 high quality undiscovered gems where smaller, less followed stocks with solid metrics are grouped in one place.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com