


- In the past week, Erez Asset Management LLC released a public presentation on UMH Properties, Inc. that was circulated via social media, following a recent shareholder and analyst call with the company.
- The presentation applies an outside investor’s lens to UMH Properties’ manufactured housing footprint and capital needs, which could refine the focus on acquisition pacing, leverage, and returns on ongoing community upgrades.
- This article examines how UMH Properties' investment narrative is affected by Erez Asset Management's socially amplified presentation on the business.
Scan how activism pressure on UMH Properties compares with peers and see which manufactured housing and real estate operators land in the 32 resilient stocks with low risk scores.
UMH Properties Investment Narrative Recap
To own UMH Properties, you need to believe the manufactured housing platform can keep converting strong underlying demand and regulatory support into steady rent, fee, and sales income without stretching the balance sheet too far. The short term swing factor is whether management can fund community upgrades and selective expansion without pushing interest costs higher, given earnings already do not fully cover interest payments.
The biggest operational risk today is the capital intensity of the model. UMH has relied on higher risk external borrowing and also carries a dividend that is not covered by earnings, which tightens financial flexibility. The Erez presentation raises questions on leverage and capital allocation but does not, by itself, change these core business drivers.
The recent shareholder and analyst call is the clearest operational reference point for this activism. Management acknowledged a heavy need for capital, historically around US$120 million to US$150 million each year plus acquisitions, and a shift away from new equity issuance toward more debt funding. For you, that flags interest coverage and refinancing terms as live issues, not abstractions.
Viewed next to the Erez Asset Management presentation, that call becomes a focal point for how UMH Properties executes from here. The investment case leans on occupancy, regulatory support, and further community investments, yet the balance sheet already carries interest obligations that earnings do not fully cover. Execution now is about pacing growth, prioritising higher return projects, and keeping funding risk from crowding out those catalysts.
What The UMH Properties Analyst Forecasts Assume
UMH Properties' consensus roadmap points to revenues of US$330.1 million and earnings of US$19.7 million by 2029. That profile is based on analysts assuming 7.5% yearly revenue growth and an earnings increase of about US$10.9 million from current earnings of US$8.8 million.
Uncover why UMH Properties' fair value indicates a 29% potential upside to its current price before momentum around that gap shifts.
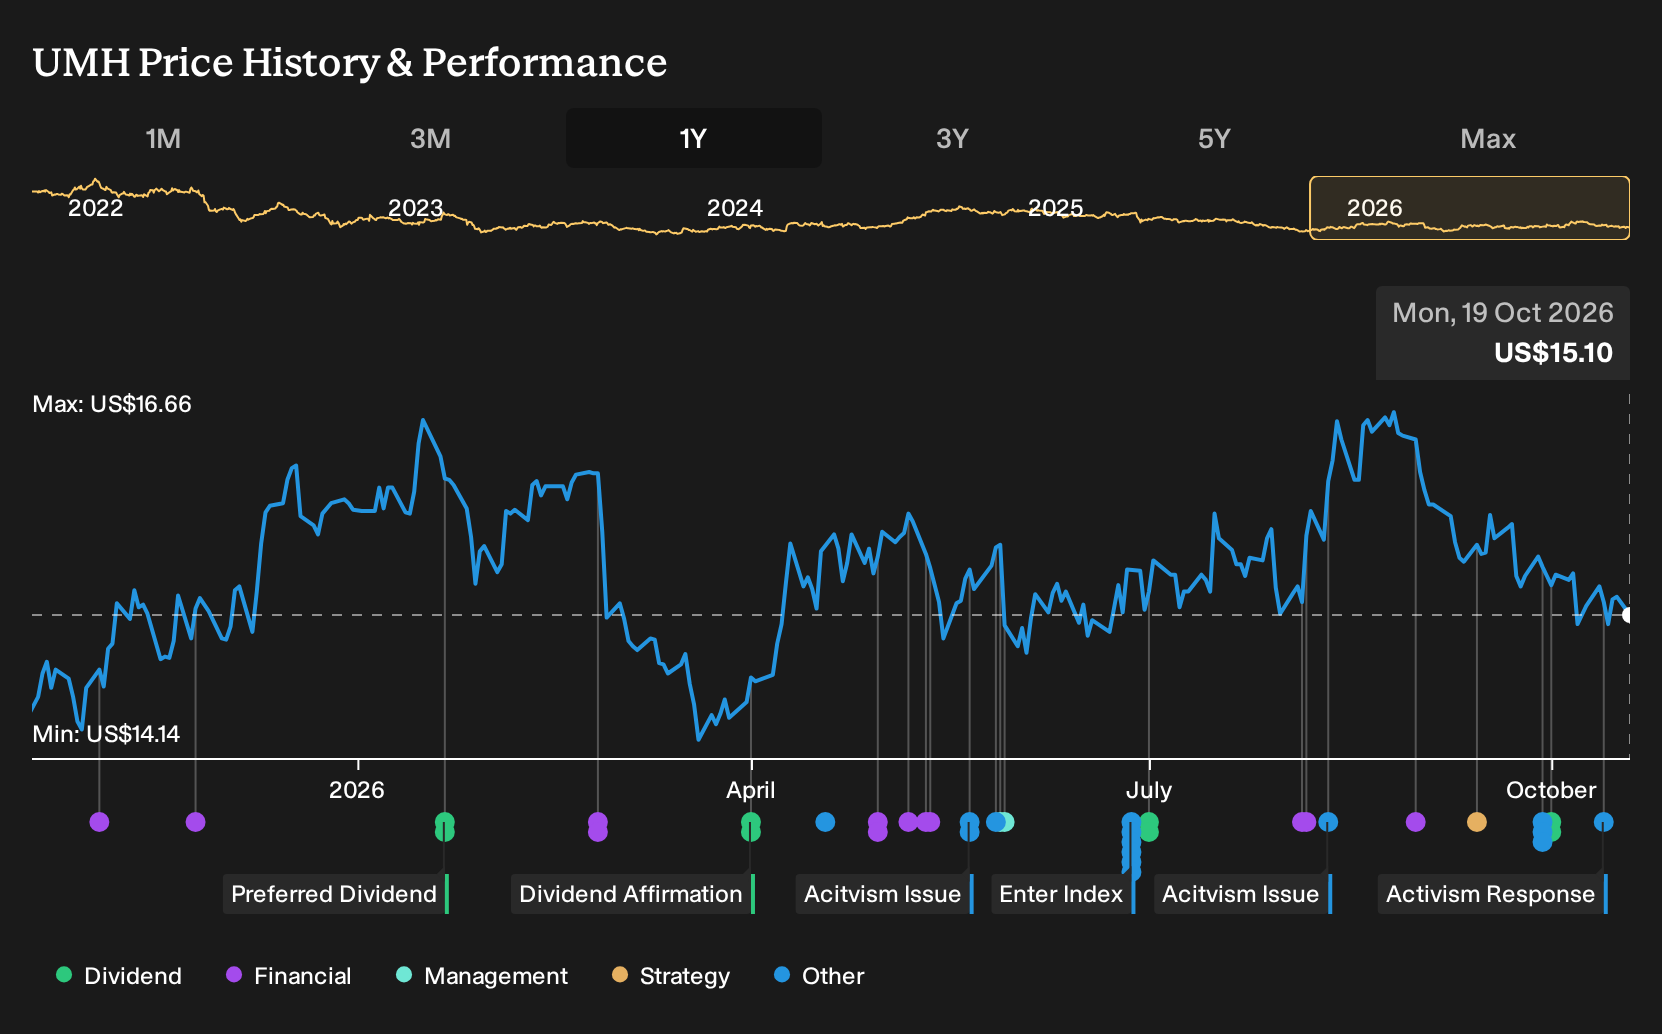
Exploring Other Perspectives
One alternate storyline around UMH Properties focuses squarely on margin pressure rather than revenue growth. The most bearish analysts, writing before this Erez activism burst into view, were pencilling in about US$333.8 million of revenue and only US$7.3 million of earnings by 2029. That is far more cautious than consensus. Use this activism moment to compare both narratives and decide which assumptions appear more realistic to you.
Explore 2 other UMH Properties fair value estimates, including one that suggests it could be worth just $18.88!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your UMH Properties research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UMH Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMH Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond UMH Properties?
Once you have a view on UMH Properties, it can help to compare that thesis with other listed businesses that match the kind of balance sheet strength, income profile, or upside potential you are hunting for.
- If you want potential upside with some downside protection, scan a curated 32 resilient stocks with low risk scores that score well on resilience.
- For investors hunting for mispriced quality, review a focused 35 high quality undervalued stocks that combines strong fundamentals with attractive pricing.
- Income focused readers who care about consistency can weigh payout ideas sourced from a targeted 8 dividend fortresses built around higher yielding companies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com