


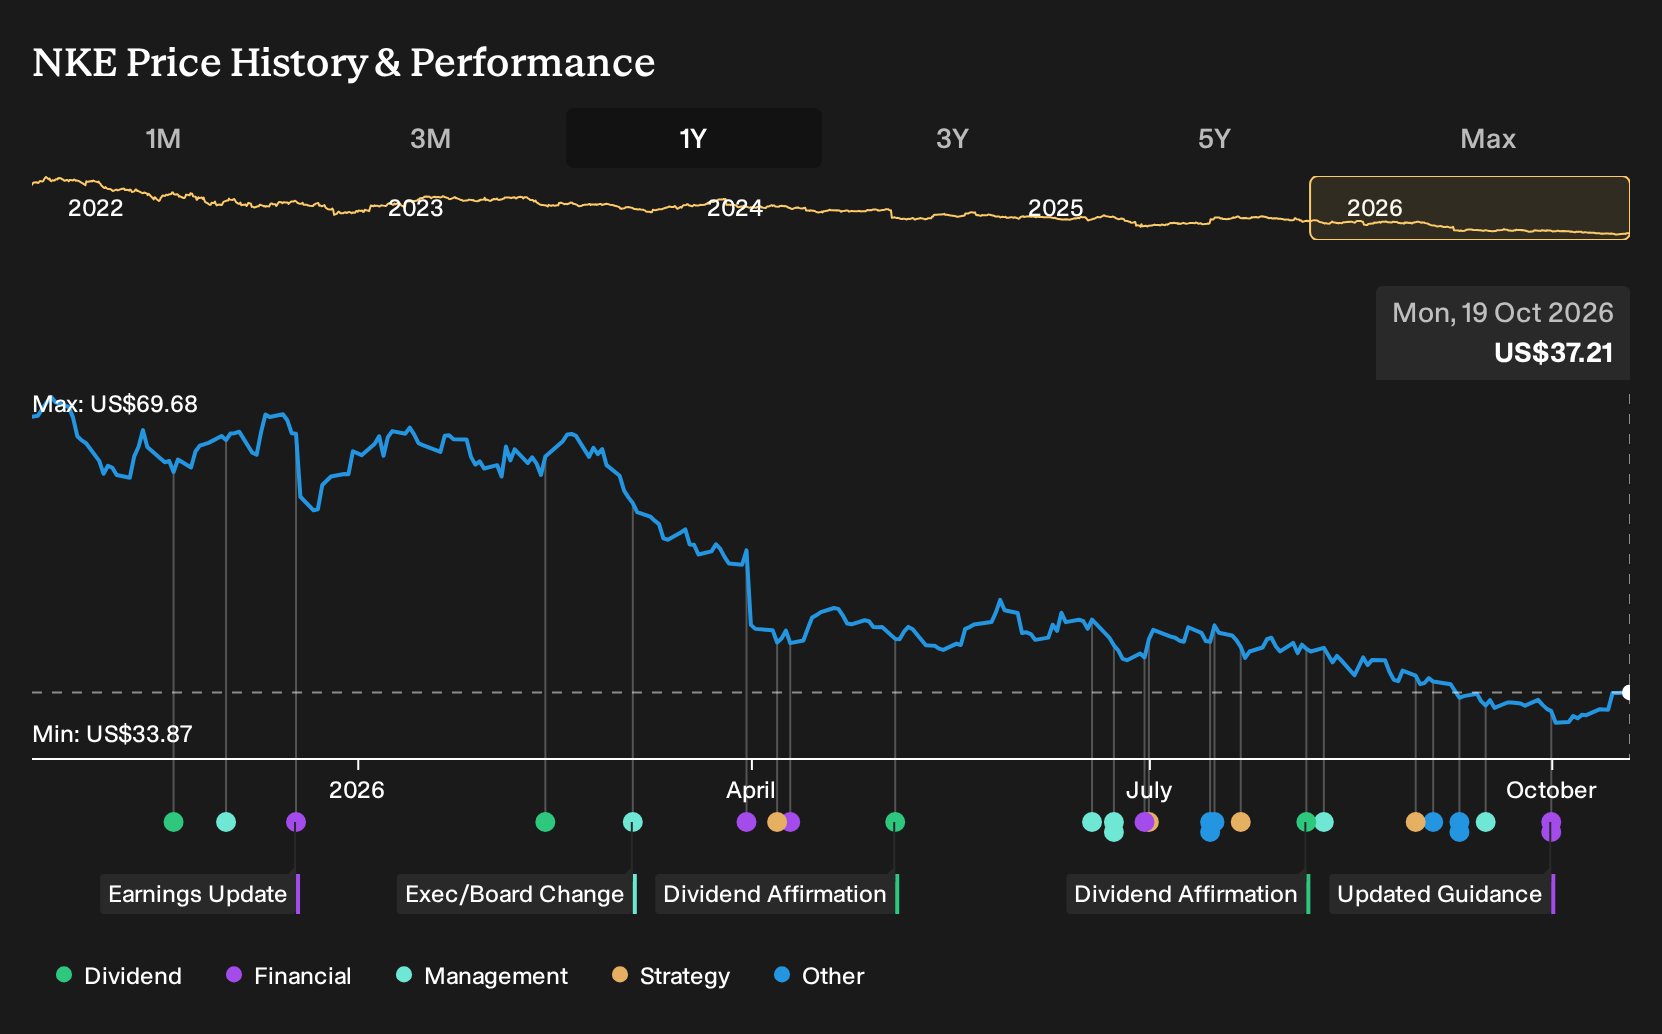
If you only skimmed the headlines about Nike clearing inventory and resetting its product mix, it might have sounded like the worst was already behind it. Investors who held NIKE over the past year are down 43.2%, including dividends. That loss landed even as the latest quarterly report showed roughly flat net margin, with revenue and profit both softer. If you were weighing a fresh position back in October 2025, what clues were already on the table about this reset going wrong?
The easy part of this move is behind NIKE. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Two Nike Narratives Investors Had To Weigh
The shares cost US$67.37 at the start of the period, and anyone looking at Nike then saw two very different stories sitting behind that quote.
On the bullish side, one view said the reset could work. That narrative pointed to a Fair Value of US$79.76, the price those assumptions implied, built on 3.1% annual revenue growth and profit margins reaching 8.3% within three years as sport performance products and NIKE Digital cleanup took hold.
The bearish camp focused on a Fair Value of US$38, based on a belief that revenue could decline 0.7% a year and margins drift to 6.9% as Chinese tariffs, higher sourcing costs, and weaker demand reduced Nike’s earnings power.
What The Evidence Did To The Nike Argument
The clearest data point came from Nike’s Q1 2027 report, where revenue slipped from US$11,720m to US$11,213m while net income also eased and net margin only edged from 6.2% to 6.3%. That combination challenged the bullish reset story and leaned toward the cautious case that expected pressure on both sales and profitability.
The lesson is simple. When a turnaround pitch leans on higher margins, track whether net margin moves meaningfully rather than just directionally, and compare that shift to any change in revenue.
What Nike’s Lower Price Now Asks You To Believe
Today Nike trades at US$37.21, well below where recent holders bought in. The featured Narrative still places its Fair Value above that quote, built on the idea that a strong brand and cost efficiency matter more than the reset missteps.
The key question for you is whether Nike can keep using scale, pricing power, and direct sales to support that higher Fair Value.
"With a strong balance sheet, continuous innovation, and a growing direct-to-consumer strategy, Nike is positioned to navigate competitive pressures and pursue long-term shareholder value as part of a diversified investment portfolio."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 41% below our estimate - helps clients address AI, utility risk and chemical safety through specialist consulting.
- Company 2 - 45% below our estimate - turns a strong backlog of tech-heavy data center and modular projects into installation work.
- Company 3 - 33% below our estimate - provides higher-cost gold production exposure with long-life reserves across several mining regions.
That is three of the list. See all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com