


With no single headline event driving attention, interest in Bank First (BFC) today centers on how its recent share performance and financial profile compare for investors tracking regional banks.
Recent trading has been softer, with the 1 month share price return down 4.1% and the latest move taking Bank First to $146.01. However, the year to date share price gain of 21.0% and a 5 year total shareholder return of 134.8% point to momentum that has been building over a longer stretch as investors reassess both its growth profile and perceived risk.
Scan regional bank momentum such as Bank First and compare its profile against a hand-picked 32 resilient stocks with low risk scores that balance growth, profitability, and more conservative risk scores.
After a strong multi year run and a softer recent pullback, Bank First now sits at $146.01. The question for investors is whether it makes more sense to commit capital at this level or wait for a cheaper entry as the valuation picture comes into focus next.
Price-to-Earnings of 20.1x: Is it justified?
Valuation is tight for Bank First, with the shares trading on a P/E of 20.1x that sits above several reference points and leaves little room for missteps at $146.01.
The P/E ratio compares what you pay per share to the earnings that Bank First generates. A higher figure means investors are willing to pay more for each dollar of profit. For regional banks this often reflects expectations around future earnings growth, perceived balance sheet strength, or a cleaner earnings profile.
Here the market is assigning Bank First a P/E of 20.1x, while the estimated fair P/E sits slightly lower at 19.7x. That gap is small, yet it still reflects a valuation level that leans rich rather than cheap. Earnings quality is flagged as high and profit growth over the past year is described as faster than its own 5-year average, which can help explain why some investors are prepared to pay up.
The stretch becomes clearer once you compare Bank First to reference groups. The P/E of 20.1x is described as expensive versus the wider US Banks industry average of 11.5x and also versus a peer average of 17.3x. Both comparisons point to a premium that the market could reassess if sentiment toward regional lenders or Bank First specifically cools.
Explore the SWS fair ratio for Bank First.
Result: Price-to-Earnings of 20.1x (OVERVALUED)
Still, any cooling in regional bank sentiment, or a shift in how investors view Bank First's premium P/E, could quickly challenge the recent momentum story.
Find out about the key risks to this Bank First narrative.
Another View: What The Cash Flows Say About Bank First
A different lens tells a similar story. Our DCF model points to a future cash flow value of $136.48 for Bank First, which sits below the current $146.01 share price and frames the stock as overvalued on this measure as well.
That gap is not massive. However, it suggests limited room for disappointment if growth or returns fall short of forecasts. For investors comparing tools, the question is whether you trust the earnings multiple or the cash flow model more for a regional lender like Bank First.
Look into how the SWS DCF model arrives at its fair value.
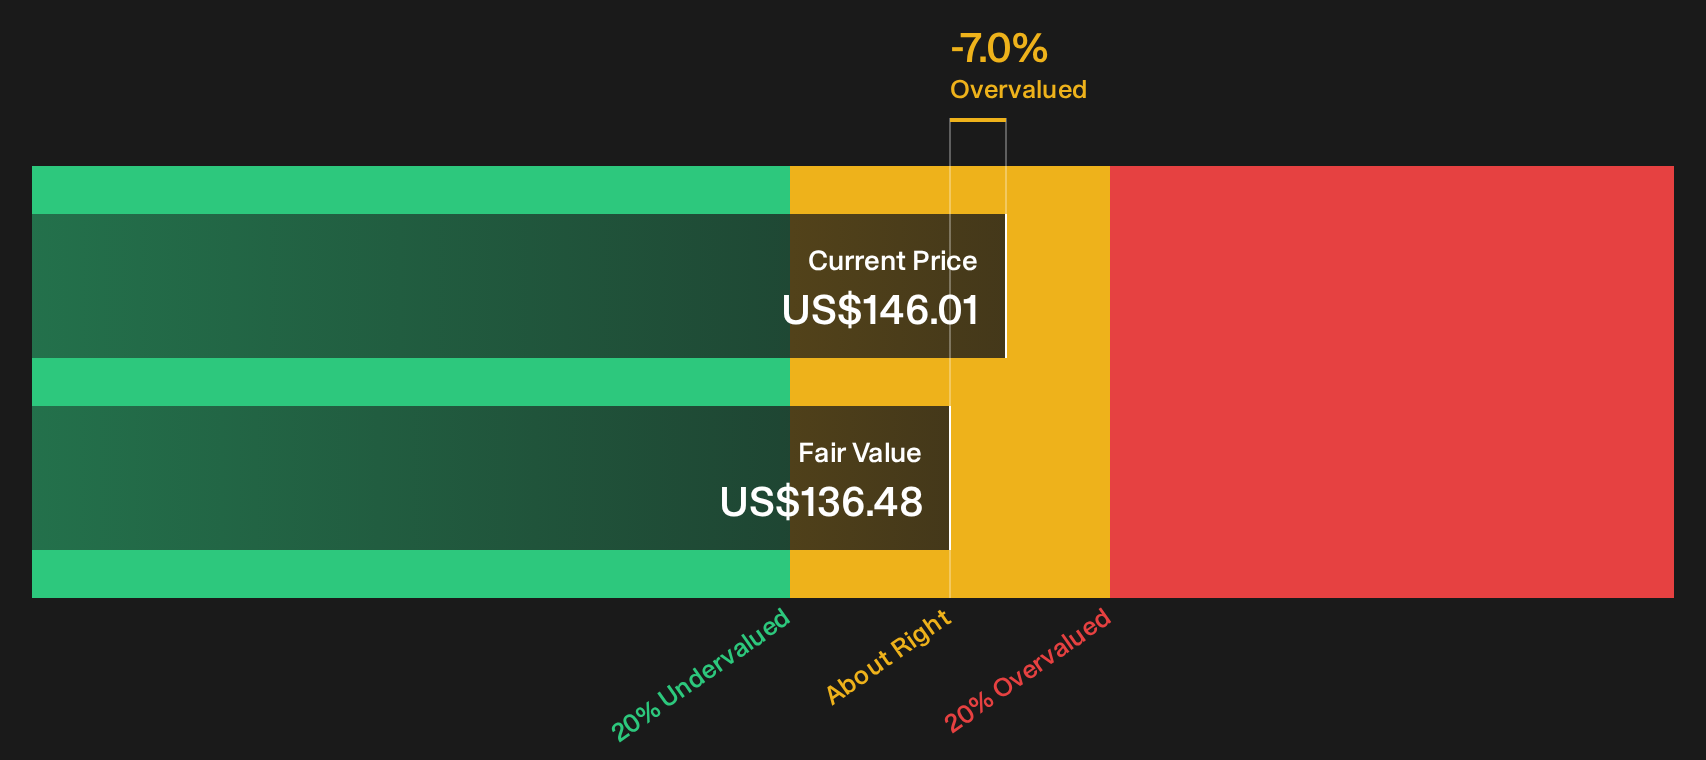
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank First for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Bank First's valuation and cash flows make this one a judgment call. Move quickly, pull up the full data set, and weigh both the upside and the red flags highlighted in the 3 key rewards and 1 important warning sign.
Looking for more Bank First investment ideas?
If you stop with Bank First, you only see part of the opportunity set. Use the Simply Wall St screener to quickly surface fresh, data driven ideas that match your goals.
- Target quality at a discount by scanning companies with strong fundamentals using the 35 high quality undervalued stocks.
- Strengthen your margin of safety and filter for companies with robust finances through the list of solid balance sheet and fundamentals (25 results).
- Lock in potential income ideas by reviewing a curated set of higher yielding payers via the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com