


Moody's (MCO) heads into its third quarter earnings on October 21 with expectations for steady credit ratings activity and ongoing demand for its Analytics services, against a backdrop of recent board and committee reshuffling.
Recent trading has been choppy for Moody's, with the share price easing 0.8% over the past day but still showing a 2.3% 7 day share price return and a modest 2.7% 30 day gain. The year to date share price return is down 3.6%, compared with a 1 year total shareholder return of 2.3% and a 3 year total shareholder return of 59.6% that reflects a much stronger longer run.
Spot opportunities beyond Moody's by scanning a curated 32 resilient stocks with low risk scores that reflects its risk-focused profile and may offer a steadier ride through credit and earnings cycles.Moody's now trades just below its recent highs after a long multi year climb, so the key question is whether to step in at US$481 or wait for a cheaper opportunity at the same earnings power.
Most Popular Narrative: 9% Undervalued
Moody's last closed at $481.26 while the most followed valuation storyline, according to OLetourneau, points to a fair value of $529. That gap puts the spotlight on how durable the ratings moat is and what actually drives the earnings power behind the ticker.
The toll booth on global debt. Any bond sold to regulated buyers needs a rating from a recognized agency, and Moody's is half of a duopoly whose position comes from a regulatory licence rather than product quality, which is why no third entrant has emerged in decades. AI can write the credit analysis but cannot issue the legal opinion a pension mandate requires. This can compress the cost base while leaving pricing power intact. Valued at 9,8 % growth. Watch: the moat is AI-proof but the earnings are AI-levered, and AI infrastructure is roughly 20 % of large issuance right now. The real tail risk is regulatory de-referencing of ratings, not technology.
See why 4 investors see Moody's as 9% undervalued.
Result: Fair Value of $529 (UNDERVALUED)
Still, the narrative can crack if regulators reduce the role of formal ratings, or if AI driven tools erode demand for premium Moody's opinions.
Find out about the key risks to this Moody's narrative.
Another View: Moody's Through The P/E Lens
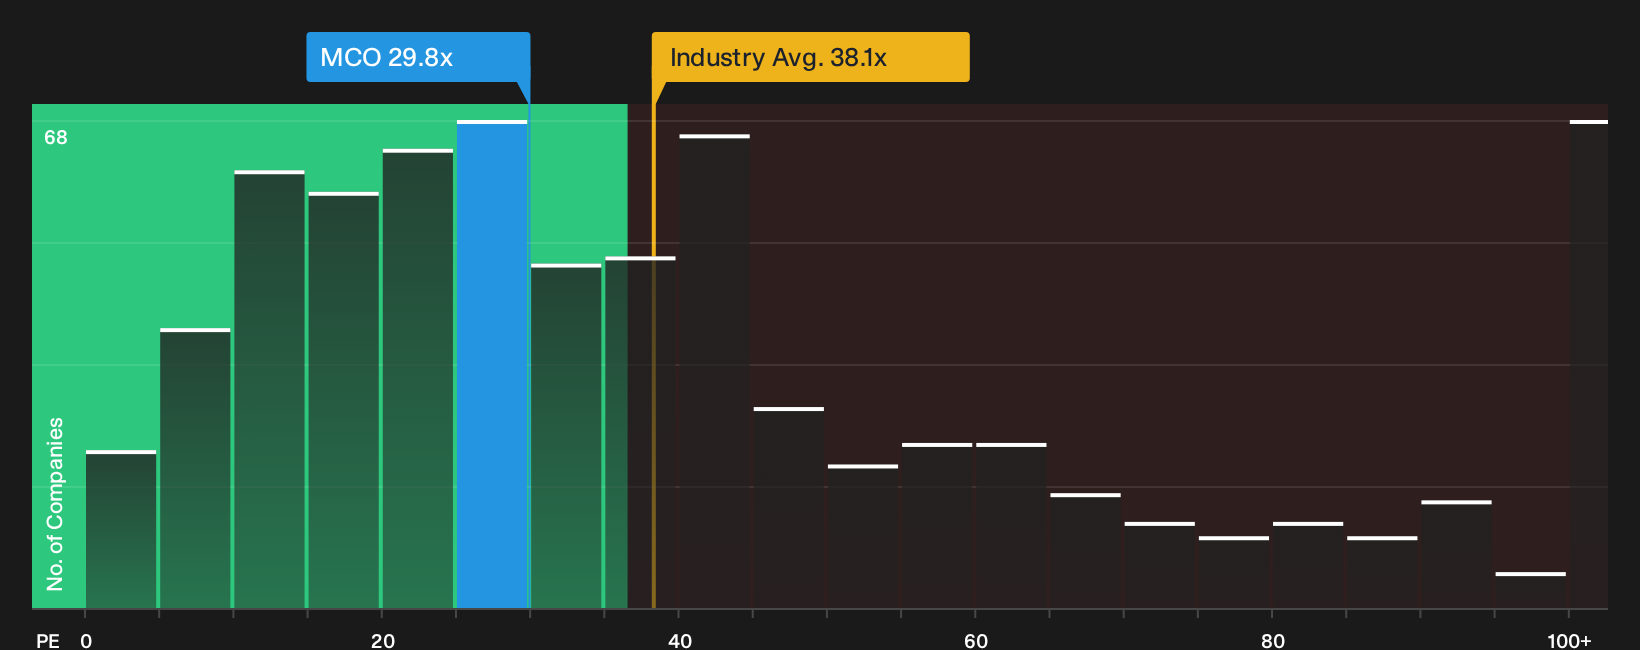
A second lens on Moody's comes from the current P/E of 29.8x. That is cheaper than the broader US Capital Markets group at 38.1x, yet richer than closer peers on 24.7x and well above a fair ratio of 15.6x. The gap hints at real execution risk if sentiment cools.
For a deeper look at how this pricing stacks up against earnings power, see what the numbers say about this price and find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the story so far. Use the data, weigh the upside against the red flags, then pressure test your own thesis with 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Moody's?
If you stop at Moody's, you might miss other opportunities that fit your approach. Use the Simply Wall St Screener to quickly surface ideas that match your risk, income, and value priorities before the next move.
- Target steady cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that puts financial resilience and fundamentals at the front of your process.
- Hunt for potential value setups by checking a curated pool of 35 high quality undervalued stocks that already screen for quality and pricing support.
- Build your income stream with a focused list of 8 dividend fortresses designed to highlight yields that may justify a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com