


Blue Owl Capital (OWL) has moved into the spotlight after teaming up with Meta on a US$27b joint venture to build a large scale data center funded through bond markets.
For context, Blue Owl Capital’s share price has fallen about 41% year to date, with the 1 year total shareholder return down roughly 42%. The modest 1 day share price gain of 1.24% after the Meta joint venture suggests that investors are reassessing the risk and reward trade off, but momentum over recent months still looks weak.
Spot emerging infrastructure plays that are part of the same AI buildout as Blue Owl Capital by scanning our curated 55 AI infrastructure stocks for potential bond-backed and asset-heavy opportunities.Blue Owl Capital now sits at the intersection of a sharp share price reset and a fresh US$27b Meta partnership that leans on bond markets. Does it make more sense to step in here or wait for cheaper terms?
Most Popular Narrative: 28.5% Undervalued
Against a last close of $8.96, the most widely followed narrative for Blue Owl Capital points to a fair value of about $12.53. This frames the Meta data center joint venture as part of a larger permanent capital and digital infrastructure story rather than a one off headline.
Exceptional long term opportunities in digital infrastructure, including a more than 140 data center footprint with about 15 to 15.3 gigawatts of capacity, a pipeline of over US$100b and the planned seeding of a US$6.5b data center REIT, are creating avenues for additional fundraising and deployment that can lift management fee revenue.
See why 60 investors see Blue Owl Capital as 28% undervalued.
Result: Fair Value of $12.53 (UNDERVALUED)
Still, the Blue Owl Capital story can shift quickly if capped withdrawals in key private credit funds persist or if legal action around the BDC unit escalates.
Find out about the key risks to this Blue Owl Capital narrative.
Another View: What Blue Owl Capital’s P/E Is Telling You
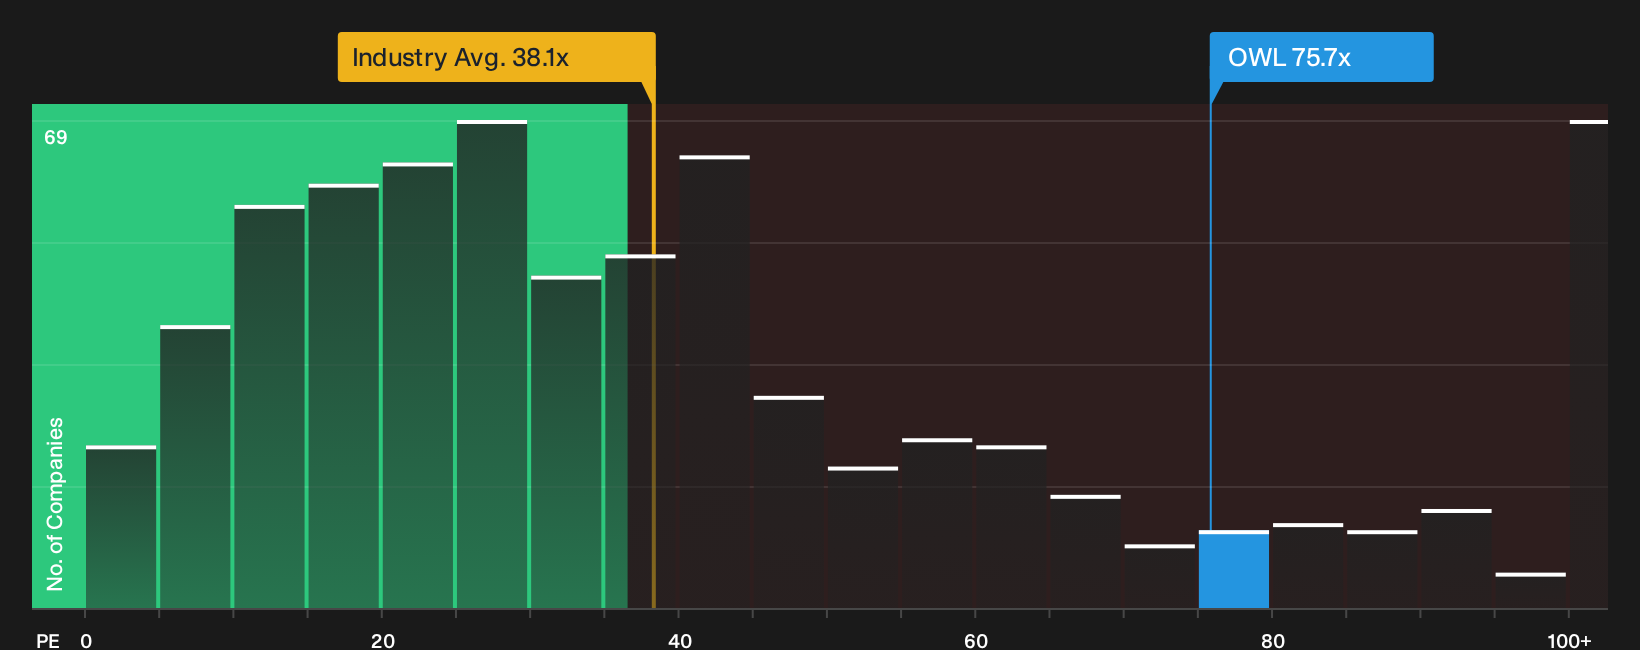
The first narrative paints Blue Owl Capital as about 28.5% undervalued on fair value. The P/E picture is less friendly. At roughly 75.7x earnings, OWL trades well above its fair ratio of 18.1x, the US Capital Markets sector on 38.1x, and peer average around 28.9x. That gap points to meaningful valuation risk if sentiment or earnings expectations cool. The key question is whether investors are really being paid enough to accept that kind of premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you are undecided on Blue Owl Capital after all this, or leaning strongly in one direction, then move quickly and pressure test your own thesis by weighing its 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Blue Owl Capital?
Do not stop your research at Blue Owl Capital. A broader watchlist can sharpen your judgment, highlight trade offs, and keep you from anchoring on a single storyline.
- Target potential mispricings by scanning a curated pool of quality candidates through the 35 high quality undervalued stocks.
- Focus on resilience and sleep better at night by filtering for companies with stronger finances using the 32 resilient stocks with low risk scores.
- Hunt for under-the-radar opportunities with robust fundamentals before the crowd notices by reviewing the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com