


- SM Energy has seen analysts lift earnings estimates, with current quarter expectations at $1.85 per share and consensus forecasts revised higher in recent weeks.
- The sharper earnings outlook highlights how SM Energy's cost base, asset mix and operating choices are feeding directly into stronger projected profitability.
- We will look at how SM Energy's investment narrative is influenced by these higher earnings estimates and rising analyst optimism.
Compare SM Energy's upgraded earnings story with a hand-picked 20 high quality undiscovered gems that analysts are paying attention to for similar revisions momentum.
SM Energy Investment Narrative Recap
For SM Energy, the core belief as a shareholder is that operational execution and cost discipline can keep turning its multi basin portfolio into solid cash generation, rather than chasing production volume at any price. The near term swing factor is how consistently those efficiency gains and synergy targets show up in quarterly earnings and free cash flow.
The biggest risk still sits on the balance sheet. Debt remains high in absolute terms, so a weaker commodity tape or any stumble in the drilling program could slow progress toward lower leverage. The latest earnings revisions improve sentiment, but they do not remove that funding and execution risk.
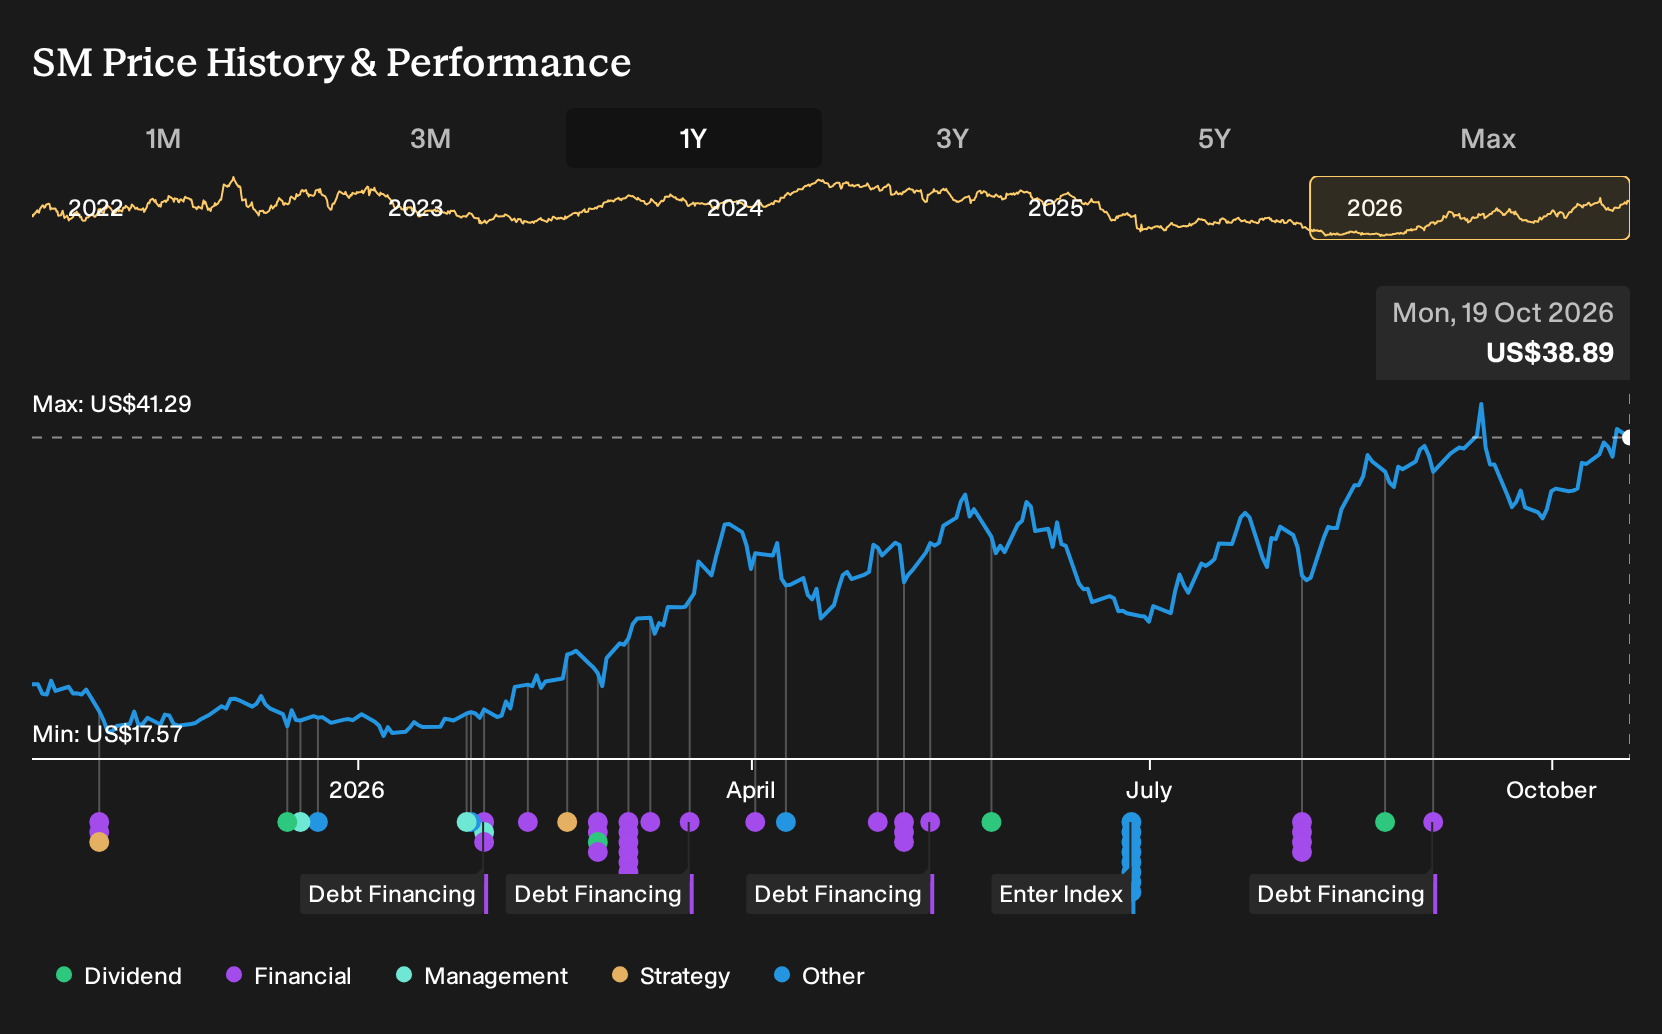
The recent lift in earnings expectations, including the US$1.85 per share estimate for the current quarter, directly links back to SM Energy’s operating plan. Analysts are effectively marking to market the impact of merger synergies, lower recurring G&A, and well cost savings such as 4 mile laterals and simul frac in the Uinta Basin.
Those same actions sit at the center of the near term catalysts. Faster completions, reduced drilling and completion costs, and no senior note maturities until mid 2028 give the business more room to push cash toward debt reduction. If that operational pace slows or cost savings fade, the revisions momentum highlighted in this news event could prove short lived.
What The Analyst Targets Assume For SM Energy
SM Energy's narrative projects US$7.4b revenue and US$1.8b earnings by 2029. This implies analysts are assuming 14.2% yearly revenue growth and an earnings increase of about US$800m from US$1.0b today.
Uncover why SM Energy's fair value indicates a 14% potential upside to its current price, which could narrow quickly if sentiment continues to track these earnings upgrades.
Exploring Other Perspectives
One alternate angle you might consider focuses on how optimistic the highest SM Energy analysts already were before this earnings revision story hit. They were sketching out US$8.6b of revenue and US$2.4b of earnings by 2029, far above the baseline. That optimism could shift again once this latest revisions news fully feeds into their models.
Explore 5 other SM Energy fair value estimates, including one that suggests potential upside of as much as 224% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SM Energy research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SM Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SM Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond SM Energy?
If SM Energy has sharpened your thinking and you want to pressure test that view against other opportunities, the Simply Wall St Screener can help you scan the market using the same kind of data driven lens.
- If you want potential value opportunities with quality fundamentals, start with a focused set of 35 high quality undervalued stocks that rank well on both balance sheet strength and cash generation.
- For investors who care about staying on the front foot with capital preservation, narrow the field to a 32 resilient stocks with low risk scores and compare how those businesses stack up on risk signals and earnings stability.
- When you want to concentrate on financially robust operators, use the list of solid balance sheet and fundamentals (25 results) as a jumping off point and benchmark their metrics against what you see at SM Energy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com