


Noble (NE) heads into its upcoming September quarter earnings report with a mixed setup, as investors weigh expectations for higher profit on lower revenue against shifting analyst forecasts and a positive Earnings ESP signal.
The share price tells the story of rising optimism around Noble. The stock has delivered a year-to-date share price return of 51.86%, is trading at $44.04, and that move lines up with a 1-year total shareholder return of 63.90% as investors weigh higher earnings expectations against recent estimate cuts.
Scan for other offshore and energy contractors showing similar earnings momentum and estimate revisions to Noble by checking the hand-picked list of solid balance sheet and fundamentals (25 results)
That kind of move in Noble can either signal investors are catching up to the underlying earnings power, or that sentiment has run ahead of the business. The valuation now has to answer that debate.
Most Popular Narrative: 8.6% Undervalued
Noble’s most followed valuation narrative pegs fair value at $48.18, which sits above the last close at $44.04 and presents the stock as modestly discounted rather than mispriced in either direction.
The main factor is Noble converting its multi-year, roughly $7.5b backlog and projected fleet reactivations into the EBITDA and free cash flow levels management has outlined for the second half of 2027, despite current operational issues, guidance cuts, and the Brazil-related investigation.
See why 70 investors see Noble as 9% undervalued.
Result: Fair Value of $48.18 (UNDERVALUED)
Still, Brazil related rig suspensions and the ongoing fraud investigation around those disclosures leave Noble’s backlog conversion and future legal costs as live swing factors.
Find out about the key risks to this Noble narrative.
Another View On Noble’s Valuation
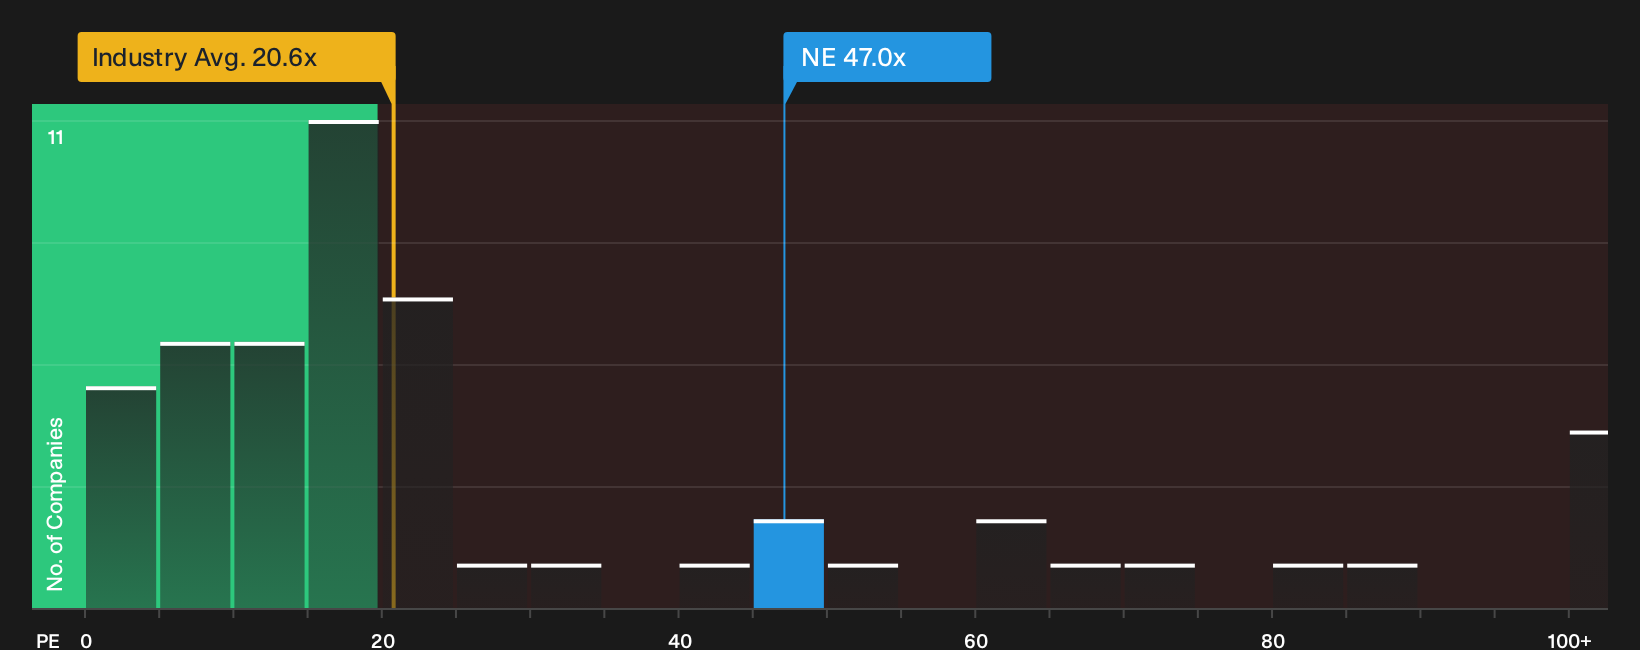
On earnings expectations and backlog, Noble looks modestly undervalued. On simple P/E math it looks expensive. The current P/E is 47x, above the US Energy Services average of 20.4x, a peer mark of 27.5x, and even the 46x fair ratio, which points to a thinner margin for error.
For a closer look at how that price lines up with the underlying numbers, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Noble is clearly split, with risks and rewards both on the table. Review the data quickly and weigh the 2 key rewards and 2 important warning signs.
Looking for more Noble-sized opportunities?
If you stop with Noble, you risk missing other mispriced ideas. Let the data surface fresh opportunities that match your goals before others move first.
- Target quality at a discount by scanning companies screened as 35 high quality undervalued stocks built on solid fundamentals instead of hype.
- Prioritise resilience by reviewing 32 resilient stocks with low risk scores that pair sturdier balance sheets with lower overall risk profiles.
- Get ahead of the crowd by checking 20 high quality undiscovered gems that combine strong financials with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com