


Franklin Electric (FELE) reshaped its leadership bench by appointing Luciana Amaro as Chief Human Resources Officer to oversee global HR and support long term growth plans across its water, energy, and distribution operations.
Franklin Electric’s recent leadership change comes as the share price sits at US$99.43, with a 30 day share price return of 4.1% but a 90 day share price decline of 4.3%, while the 3 year total shareholder return of 21.9% points to steadier longer term momentum.
Scan how Franklin Electric’s leadership-driven story stacks up against other industrials by reviewing our hand picked list of solid balance sheet and fundamentals (25 results) now capturing investor attention.
Franklin Electric looks like a solid industrial platform with global reach and fresh leadership on the people side. The real test for investors now is whether the US$99.43 share price still reflects fair value or a stretch.
Most Popular Narrative: 16% Undervalued
On the widely followed narrative, Franklin Electric’s fair value sits at $118.50 against the last close of $99.43. The valuation debate really hinges on whether its execution and capital allocation plans hold up.
The Value Acceleration Office and broader supply chain and restructuring efforts, which target more than $15 million of productivity in 2026 and over 100 basis points of annual margin uplift when fully ramped, are designed to support higher operating margins and earnings even if top line growth is moderate.
See why 2 investors see Franklin Electric as 16% undervalued.
Result: Fair Value of $118.50 (UNDERVALUED)
Still, the Franklin Electric story can break if productivity gains underwhelm or if weaker regions such as Brazil agriculture weigh more heavily on Water Systems demand.
Find out about the key risks to this Franklin Electric narrative.
Another View: Franklin Electric Through The P/E Lens
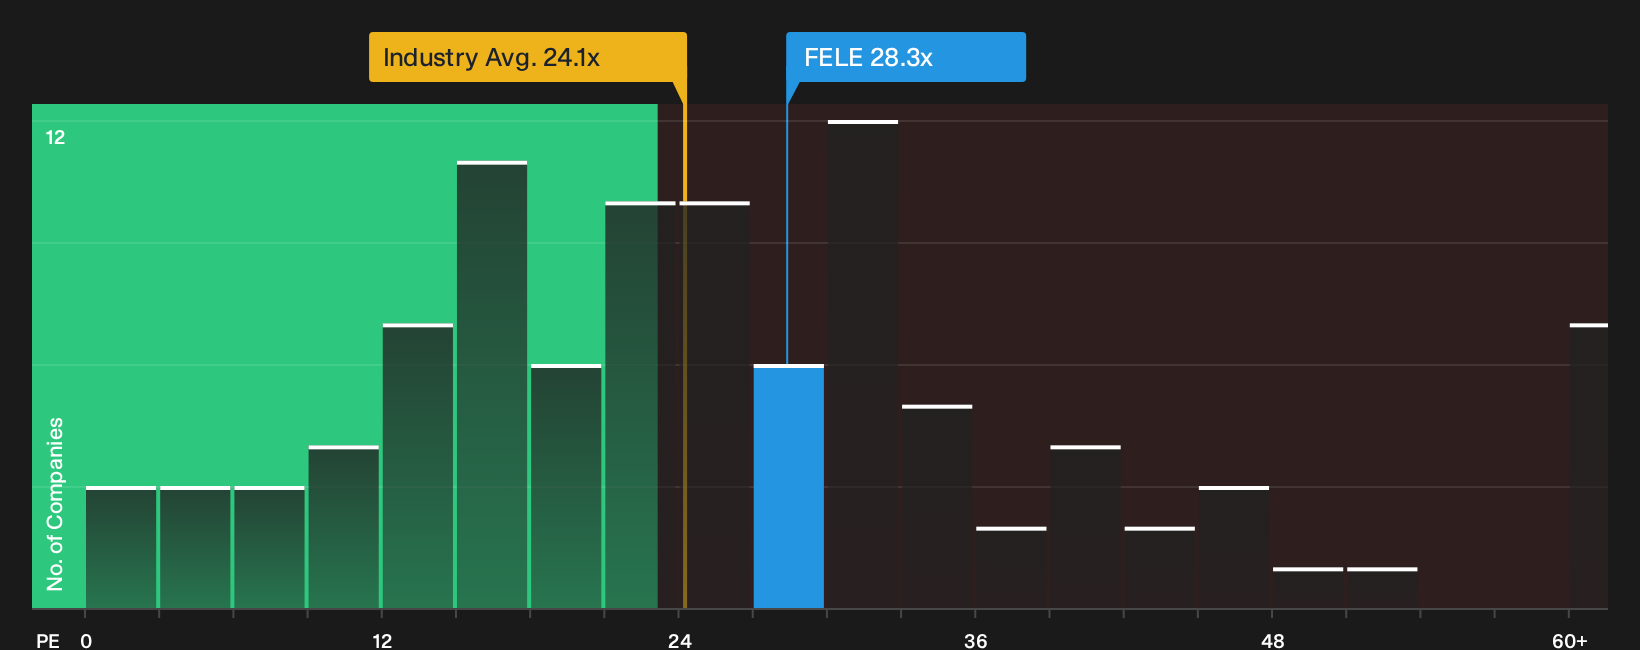
There is a different read on Franklin Electric when you step away from fair value models and just look at the P/E. The stock trades on about 28.3x earnings, above the US Machinery industry at 24.2x and above its own fair ratio of 26.2x. This points to a richer entry point and less room for disappointment if things go wrong.
That premium versus peers and the fair ratio suggests investors are already paying up for the Franklin Electric story. The question becomes whether you are comfortable underwriting that higher multiple if execution on productivity and growth stumbles.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Franklin Electric’s valuation and execution make this a moment to move fast, review the underlying data, and decide where you land on the trade off between risk and upside. To help frame that view, weigh both sides by reviewing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Franklin Electric?
If Franklin Electric has you thinking harder about pricing and risk, do not stop here. Broaden your watchlist now or you will miss other compelling setups.
- Chase sharper value by reviewing the 35 high quality undervalued stocks that combine solid fundamentals with prices that still lag underlying business quality.
- Secure your income stream by scanning the 8 dividend fortresses that pair higher yields with balance sheets built to handle tougher conditions.
- Dial down portfolio stress by focusing on the 32 resilient stocks with low risk scores that score well on financial strength and business resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com