


Dynatrace (DT) just reported it has reached Initial Implementation status for FedRAMP Class D High certification, a step that could broaden access to sensitive federal workloads and reshape how investors view its public sector exposure.
FedRAMP progress lands as Dynatrace trades at US$61.54, with a 30-day share price return of 11.61% and a 90-day gain of 43.62%. The 1-year total shareholder return of 22.79% and 5-year total shareholder return decline of 20.91% indicate recent momentum building off a weaker long-run base.
Scan how other AI-focused observability and infrastructure players line up against Dynatrace on cash flows and balance sheets with our hand-picked 55 AI infrastructure stocks.
After a 43.62% move over 90 days and fresh FedRAMP progress, Dynatrace now sits closer to published targets. Is the real opportunity still ahead or has most of the upside already been priced in?
Most Popular Narrative: 0% Undervalued
Dynatrace’s most followed valuation storyline pegs fair value at $61.74, almost in line with the recent $61.54 close. This puts the spotlight on execution rather than mispricing.
The move toward value based, consumption driven pricing continues with Dynatrace Platform Subscription contracts showing platform consumption growth well over 20% compared with ARR growth of about 16% to 17%, and a heavy DPS renewal mix expected in the second half of fiscal 2027, which can translate sustained consumption into higher net retention, ARR expansion, and operating leverage over time.
See why 52 investors see Dynatrace as 0% undervalued.
Result: Fair Value of $61.74 (ABOUT RIGHT)
Still, the Dynatrace story can break if revenue expectations keep getting trimmed or if the Arize deal delivers margin dilution without clear ARR traction.
Find out about the key risks to this Dynatrace narrative.
Another View: Dynatrace Through The P/E Lens
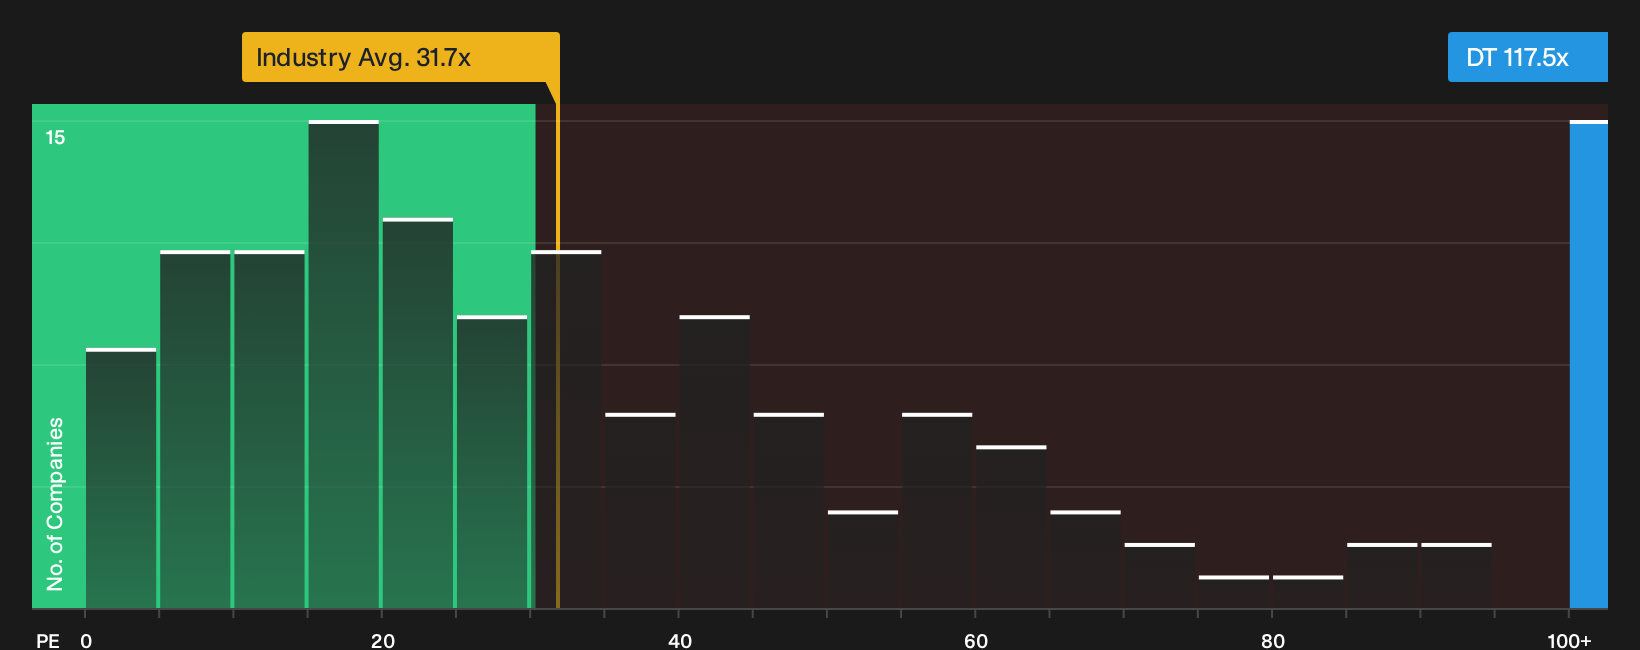
On price targets and fair value estimates, Dynatrace looks roughly in line with the market’s DCF driven story. On simple earnings multiples, it tells a very different one. The stock trades on a P/E of 117.5x versus 31.7x for the US Software group and a fair ratio of 45x. This points to a wide valuation gap that investors need to judge carefully. Is this a premium that current earnings can grow into, or a margin of risk if expectations slip?
For a closer look at how that earnings multiple stacks up against peers and the fair ratio, read through the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Dynatrace story presents mixed messages so far. Consider this a starting point and examine the numbers closely by weighing the 2 key rewards and 1 important warning sign
Looking for more Dynatrace‑style investment ideas?
Do not stop your research with Dynatrace. Broaden your watchlist with a few targeted screens that pinpoint very different types of opportunities investors often overlook.
- Hunt for potential upside in beaten down smaller stocks by scanning the 12 elite penny stocks with strong financials that still show financial strength rather than pure speculation.
- Target quality at a measured price by reviewing a 35 high quality undervalued stocks that filters for robust cash flows and balance sheets instead of hype.
- Prioritize resilience and capital preservation by working through a 32 resilient stocks with low risk scores that highlights companies with steadier fundamentals and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com