


Over the last 7 days, the United States market has experienced a slight decline of 1.8%, although it remains up by 11% over the past year with an anticipated annual earnings growth of 17%. In this context, identifying small-cap stocks with recent insider activity can provide valuable insights into potential opportunities that align well with current market conditions.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Bank of Marin Bancorp | NA | 6.9x | 35.56% | ★★★★★☆ |
| Enovis | NA | 0.5x | 40.56% | ★★★★★☆ |
| Bank of the James Financial Group | 10.6x | 2.4x | 28.71% | ★★★★☆☆ |
| Five Star Bancorp | 14.5x | 6.2x | 47.01% | ★★★☆☆☆ |
| Franklin Financial Services | 11.4x | 3.1x | -42.20% | ★★★☆☆☆ |
| Citizens Community Bancorp | 15.9x | 3.5x | 11.49% | ★★★☆☆☆ |
| Shore Bancshares | 11.3x | 3.3x | 36.88% | ★★★☆☆☆ |
| Tennant | 60.2x | 0.9x | 22.37% | ★★★☆☆☆ |
| Orion Group Holdings | 99.1x | 0.4x | 47.15% | ★★★☆☆☆ |
| Chain Bridge Bancorp | 12.0x | 4.9x | 48.74% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
SNDL (SNDL)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: SNDL is a diversified company engaged in liquor retail, cannabis retail, and cannabis operations with a market cap of CA$1.22 billion.
Operations: SNDL generates revenue primarily from liquor retail, cannabis retail, and cannabis operations. The company has seen a notable trend in its gross profit margin, which increased from -0.81863% in 2020 to 27.33% by the end of 2025. Operating expenses have been significant, with general and administrative costs being a major component over recent periods.
PE: -20.3x
SNDL, a company navigating the competitive cannabis industry, recently saw insider confidence as J. Mills acquired 50,000 shares for US$69,700 in October 2026. The company is actively seeking strategic investments and acquisitions to bolster its market position despite reporting a net loss of CAD 7.82 million in Q2 2026. SNDL completed significant share repurchases totaling CAD 32.73 million by June's end, reflecting efforts to enhance shareholder value amidst ongoing challenges with profitability and reliance on external funding sources.
- Click here and access our complete valuation analysis report to understand the dynamics of SNDL.
Examine SNDL's past performance report to understand how it has performed in the past.
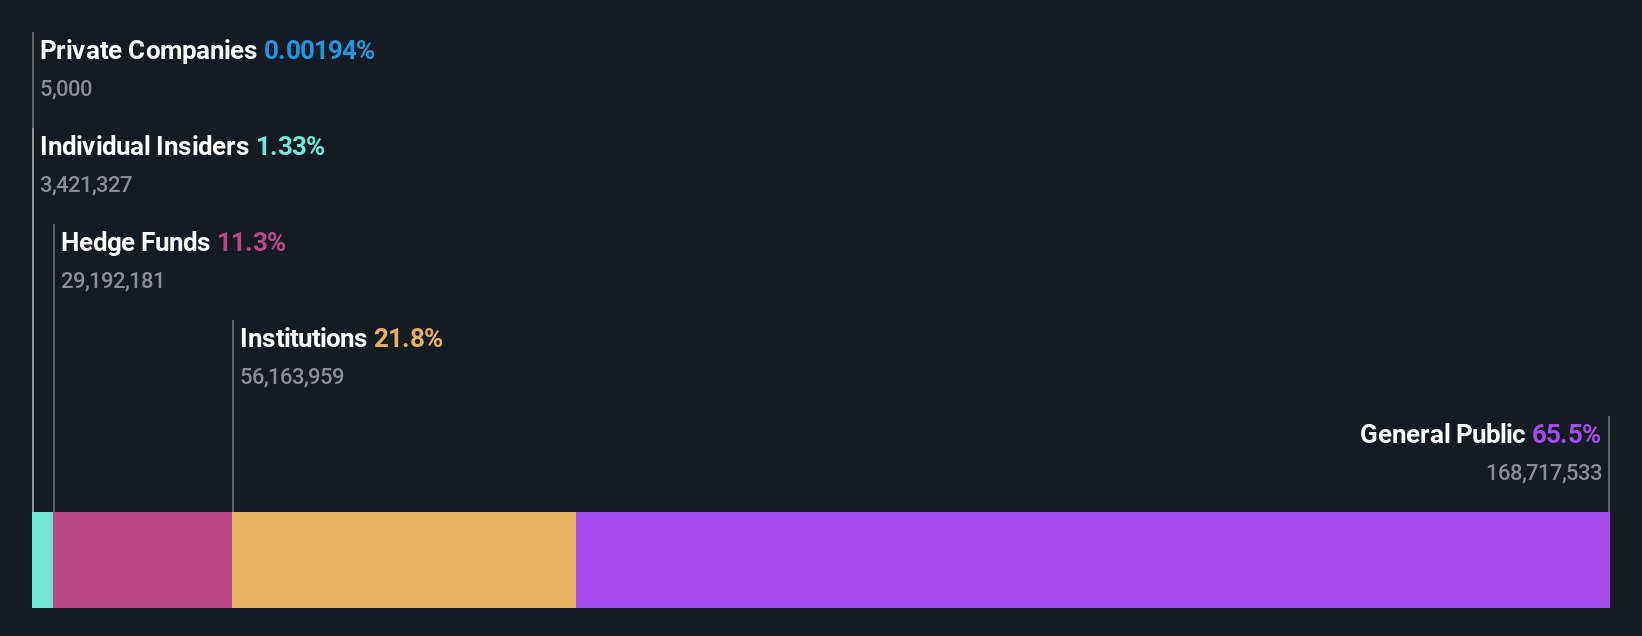
Bank of Marin Bancorp (BMRC)
Simply Wall St Value Rating: ★★★★★☆
Overview: Bank of Marin Bancorp operates as a community banking institution, providing a range of financial services primarily in California, with a market capitalization of approximately $0.37 billion.
Operations: The company generates revenue primarily from community banking activities. Operating expenses, dominated by general and administrative costs, have increased over time. The net income margin has shown variability, with recent periods reflecting negative values.
PE: -29.2x
Bank of Marin Bancorp, a smaller player in the banking sector, has shown promising financial improvements. In the second quarter of 2026, it reported net interest income of US$30.78 million and net income of US$9.25 million, bouncing back from a loss last year. Insider confidence is evident with share purchases over recent months. Added to the S&P Regional Banks Select Industry Index in September 2026, it continues its streak with an 85th consecutive quarterly dividend at US$0.25 per share, signaling stability amidst growth prospects projected at 66% annually.
- Dive into the specifics of Bank of Marin Bancorp here with our thorough valuation report.
Assess Bank of Marin Bancorp's past performance with our detailed historical performance reports.
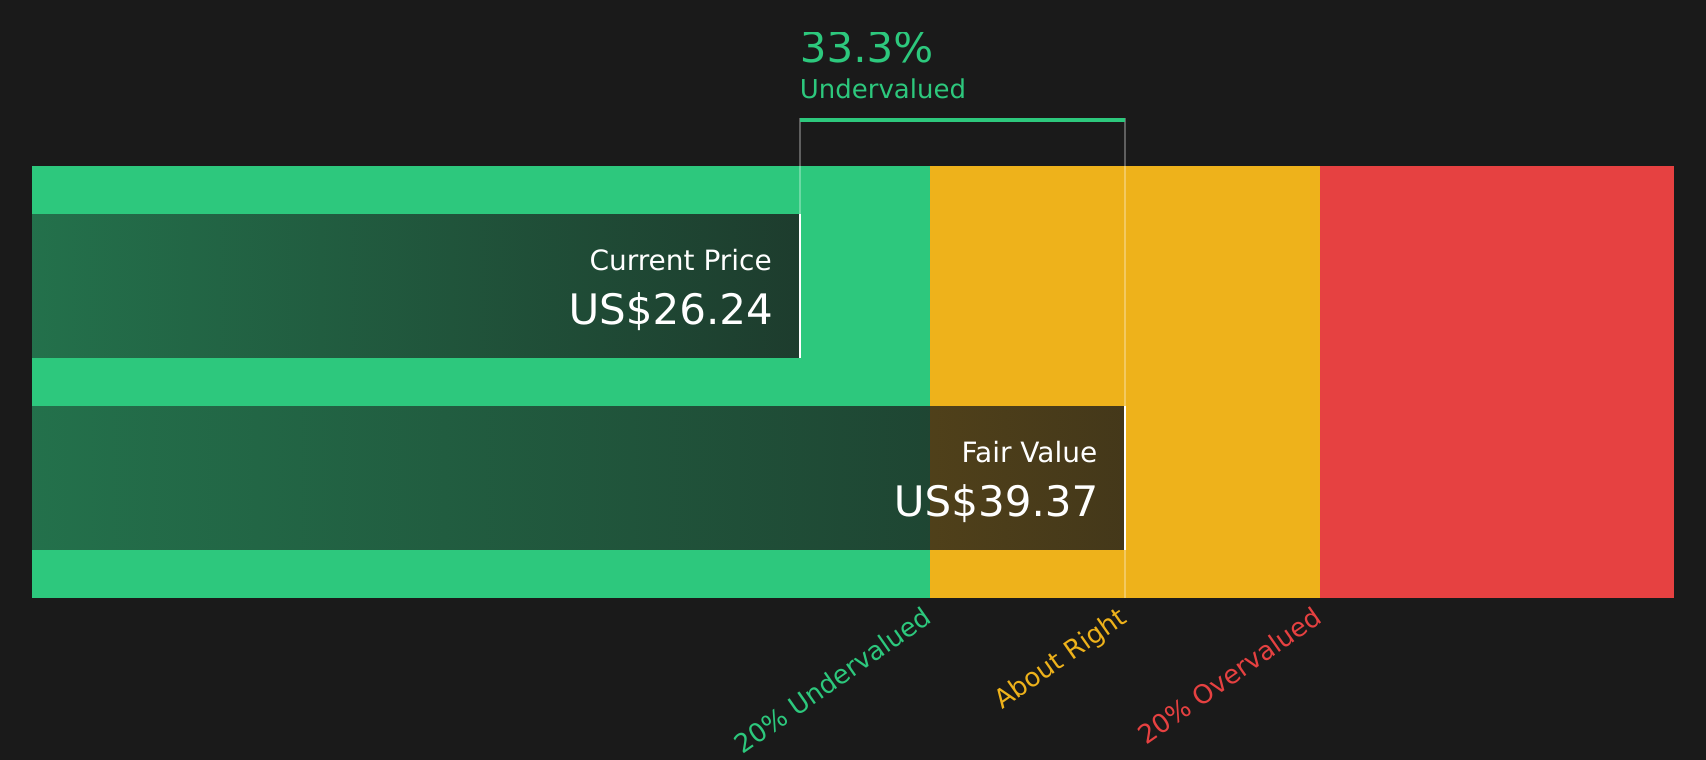
CI&T (CINT)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: CI&T is a global digital solutions provider specializing in computer services, with a market cap of $1.27 billion.
Operations: The company's revenue is primarily derived from computer services, totaling $541.02 million in recent data. Gross profit margin has shown a decreasing trend, reaching 31.16% recently. Operating expenses have been significant, with sales and marketing and general & administrative costs being notable components of these expenses.
PE: 10.3x
CI&T, a tech company with a focus on AI-driven business solutions, has been making strategic moves despite recent challenges like being dropped from the S&P Global BMI Index in September 2026. Their new unit, CI&T Business Builders, targets competitiveness and innovation across industries such as financial services and healthcare. The company expects significant revenue growth for 2026, projecting up to US$577.8 million. However, reliance on external borrowing poses funding risks while insider confidence remains unreported recently.
- Click here to discover the nuances of CI&T with our detailed analytical valuation report.
Gain insights into CI&T's historical performance by reviewing our past performance report.
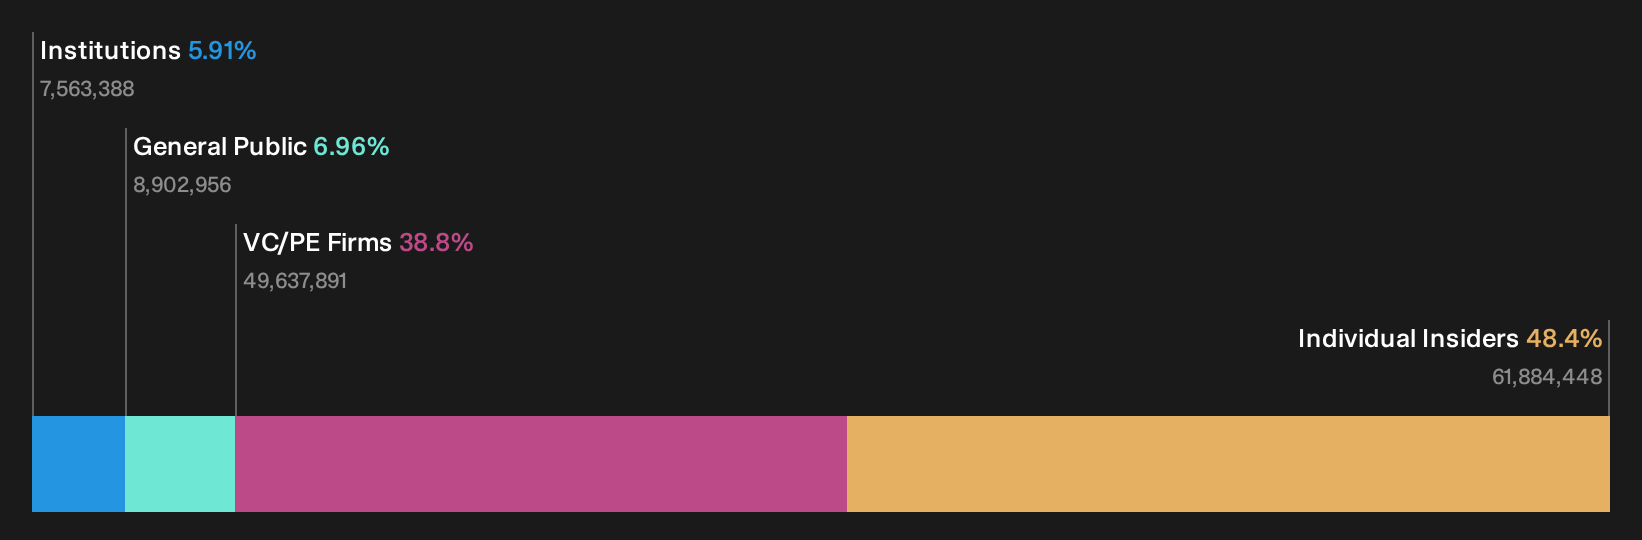
Summing It All Up
- Embark on your investment journey to our 70 Undervalued US Small Caps With Insider Buying selection here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com