


Haleon (LSE:HLN) is leaning into consumer engagement by unveiling Excedrin Rapid Relief alongside its My Little Headache digital pet and hosting a one day Haleon Health House wellness pop up in Toronto.
Recent marketing moves come against a backdrop of gradually improving momentum for Haleon, with a 7 day share price return of 6.26% and a 30 day gain of 10.65% from a latest share price of £3.77. Meanwhile, the 1 year total shareholder return of 9.52% and 3 year total shareholder return of 18.71% point to steadier progress over a longer horizon as new leadership in expert marketing and fresh brand campaigns shape sentiment.
Scan how Haleon’s marketing push compares with other consumer health plays by reviewing a curated set of list of solid balance sheet and fundamentals (9 results) that may also be leaning into brand driven momentum.
After a sharp 30 day swing to £3.77, Haleon now asks a simple question of new money: Do the current numbers still tilt the risk reward balance toward buyers or has the easy upside already been taken?
Most Popular Narrative: 22% Overvalued
Against a last close of £3.77, the most followed narrative for Haleon anchors on a fair value of £3.09. The current quote sits above what that framework suggests is reasonable and puts the burden of proof on future execution.
While the company’s simplification and AI enabled efficiency program has already delivered 140 basis points of gross margin expansion in the first half of 2026 and supports 8.2% adjusted operating profit growth at constant currency, the need to keep reinvesting some of the targeted £800m gross cost savings into marketing and capabilities raises the risk that future margin gains are smaller than expected and that net earnings fall short of prior expectations.
See why 2 investors see Haleon as 22% overvalued.
Result: Fair Value of £3.09 (OVERVALUED)
Still, if Haleon’s oral health strength and emerging market expansion lead to faster earnings progress, the current overvaluation story could appear too cautious.
Find out about the key risks to this Haleon narrative.
Another View: Haleon Through The P/E Lens
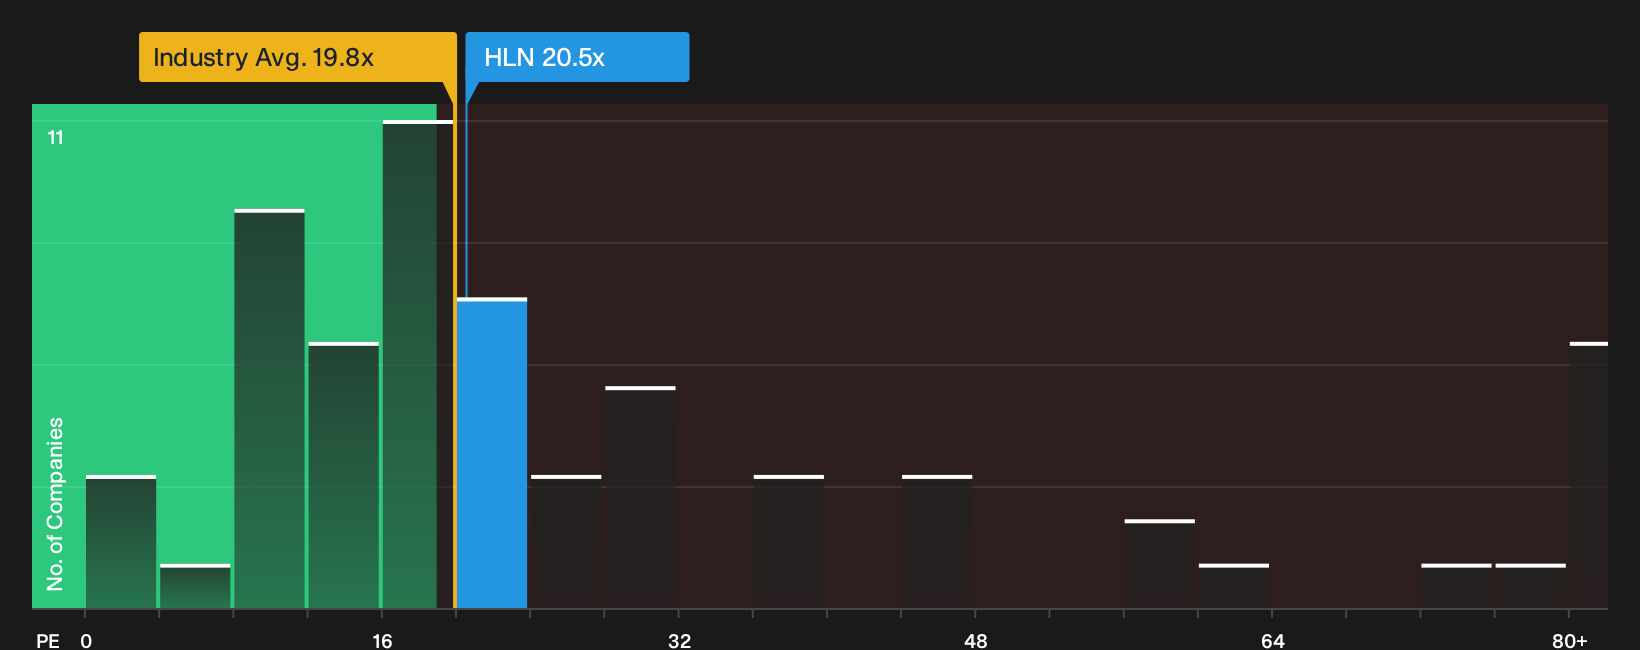
The bearish fair value of £3.09 leans on analyst forecasts and discounted cash flows. A different lens looks at Haleon’s current P/E of 20.5x against the European pharmaceuticals average of 19.6x and a fair ratio of 26.5x, which hints at both valuation risk and potential headroom. Which reference point do you treat as your anchor?
To weigh that trade off between today’s earnings multiple and the fair ratio the market could move toward, take a closer look at the detailed valuation workup in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or early inflection point. Either way, move fast enough to review the underlying data, weigh the 1+ risks against the 1+ potential rewards, and pressure test your view with the 3 key rewards and 1 important warning sign.
Looking for more Haleon sized investment ideas?
If Haleon has sharpened your appetite for deeper research, do not stop here. Broaden your watchlist now and avoid missing opportunities sitting in plain sight.
- Target quality at a discount by scanning a curated 8 high quality undervalued stocks that filters for strong fundamentals at prices that may still leave room for upside.
- Build a steadier income stream by reviewing a focused 4 dividend fortresses that highlights higher yield payouts backed by more robust financial profiles.
- Limit unpleasant surprises by zeroing in on a 4 resilient stocks with low risk scores that screens for sturdier balance sheets and calmer risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com