


Brown-Forman (BF.B) is back in focus after its latest quarter, where revenue topped analyst expectations and gross margins held firm, even as earnings per share fell short of forecasts.
Brown-Forman's latest report has come after a choppy stretch, with the share price falling 2.29% over the last day but showing a 7.96% year-to-date share price return. The 1-year total shareholder return of 0.93% sits against a much weaker 3-year total shareholder return, which has declined 44.68% and indicates that longer term momentum has been fading, even as recent quarterly numbers have rekindled interest in the stock.
Scan beyond Brown-Forman's latest quarter and compare it with other alcohol and consumer stocks showing resilient fundamentals in our hand-picked list of solid balance sheet and fundamentals (25 results).
Brown-Forman now trades only a fraction below the average analyst target, yet sits at a much steeper implied discount to intrinsic value. Is the market being sensibly cautious after a weak multi-year run or too skeptical?
Most Popular Narrative: 10% Undervalued
Brown-Forman's most followed valuation story pegs fair value at $28.26, almost level with the $28.22 last close but still pointing to a modest discount after factoring in a 7.24% discount rate.
The key requirement is that Brown-Forman expands in emerging markets and ready-to-drink products enough to offset weakness in developed markets, tequila trade-down, and the decline in used barrel sales, while also managing the upcoming gross margin headwind from higher-cost whiskey inventory.
See why 26 investors see Brown-Forman as 0% undervalued.
Result: Fair Value of $28.26 (UNDERVALUED)
Still, this narrative can break if weakness in developed international markets persists or if the drag from used barrel and bulk sales proves more prolonged.
Find out about the key risks to this Brown-Forman narrative.
Another View: Brown-Forman Through Earnings Multiples
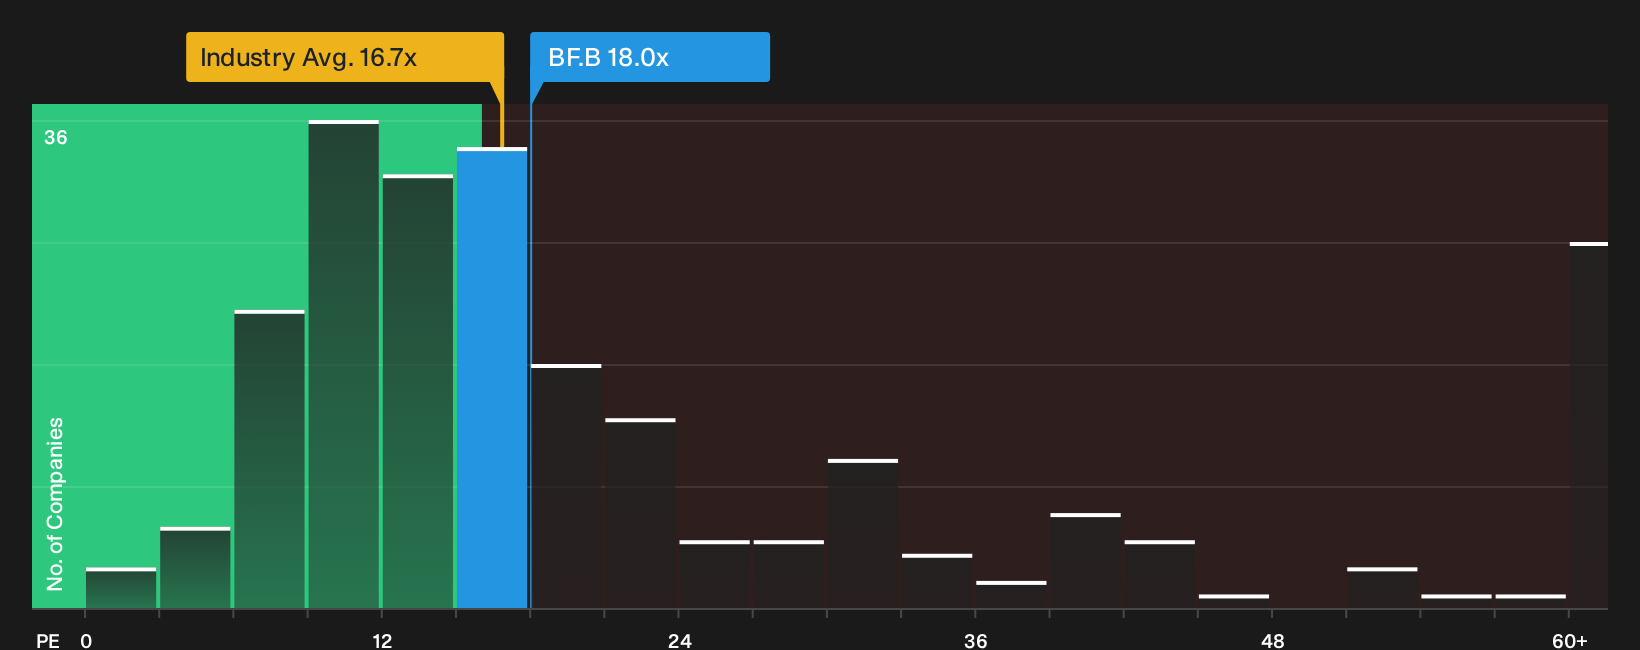
Our DCF-based fair value points to Brown-Forman trading at a 26.6% discount, yet the picture changes when earnings ratios are used instead. The current P/E is 18x, compared with a fair ratio of 16.7x and a Global Beverage industry average of 16.9x. This suggests investors are already paying a premium for this stock. If the market gravitates toward that lower fair ratio over time, how comfortable are you with the implied valuation risk?
To see how this price compares against the earnings multiple in more detail, including the gap to industry and peer benchmarks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Brown-Forman can be confusing, so do not wait for consensus to form before you look through the numbers yourself and reach a firm opinion. To balance the concerns against the potential upside in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more Brown-Forman investment ideas?
If Brown-Forman has your attention, do not stop here. Broaden your watchlist now so you are not reacting late to the next opportunity.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential value opportunities across the market with the 35 high quality undervalued stocks.
- Focus on income potential and cash returns by scanning the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com