


With the UK government backing a new Bradford Interchange as a key Northern Powerhouse Rail hub and sketching out a £45b funding cap for the wider programme, investors are watching more than just train timetables. Clearer long-term spending plans can reshape expectations for construction, engineering and materials stocks linked to rail and city regeneration. This article walks through three UK Transport Infrastructure & Construction screener stocks that appear closely tied to this story.
The stocks covered below are just a starting sample of this UK Transport Infrastructure & Construction idea, and the full screen surfaced 9 more companies with equally detailed narratives that are not included here. To identify and analyze your own highest-conviction angles on this theme, head straight into the UK Transport Infrastructure & Construction screener.
Kier Group (LSE:KIE)
Kier Group is the clearest pure play on the UK transport infrastructure theme in this screen, with its construction and infrastructure arms closely aligned to rail stations, lines and surrounding civils. This sets up a very specific question about the durability of its current work pipeline.
"Kier Group's record order book of £11 billion and its strong multiyear revenue visibility are driven by increasing contract wins, particularly in infrastructure. Delays in key infrastructure programs like Control Period 7 (CP7) and the Road Investment Strategy 3 (RIS 3) could negatively impact revenue and cash flow timing, especially if government spending profiles change unexpectedly."
What really matters for investors is how one unseen pressure in that pipeline eventually filters through to margins and cash conversion.
Kier Group is a £1.32b contractor. Its revenue base is heavily skewed to UK transport linked activity, with about £2.35b from Infrastructure Services and £1.99b from Construction. The smaller Property and Corporate segments contribute roughly £24 million and £40 million respectively.
That margin question is the real hinge, and the full narrative for Kier Group shows how Kier Group’s contract mix, risk controls and cash timing could be quietly decoupling from headline revenue.

Forterra (LSE:FORT)
Forterra plugs into the UK Transport Infrastructure & Construction theme as a core supplier of clay and concrete products that can feed everything from rail-linked regeneration to wider housing pipelines.
Forterra manufactures bricks, blocks and precast concrete products for UK building projects, with Bricks and Blocks generating about £292 million of revenue and Bespoke Products about £70 million, on a £316 million market cap.
"Although Forterra highlights mix benefits from stronger extruded brick demand and an 80% extruded weighting in non Fletton capacity, management expects 2026 performance to be only slightly ahead of 2025, with brick demand broadly flat and weighted to the second half."
What really moves the dial for Forterra now is how one quiet shift in where demand comes from ultimately feeds through to pricing power and margins.
When that shift in demand mix really matters, the full narrative for Forterra explains how flat volumes, pricing power and margin pressure could be interacting to set up the next leg for Forterra.

SigmaRoc (AIM:SRC)
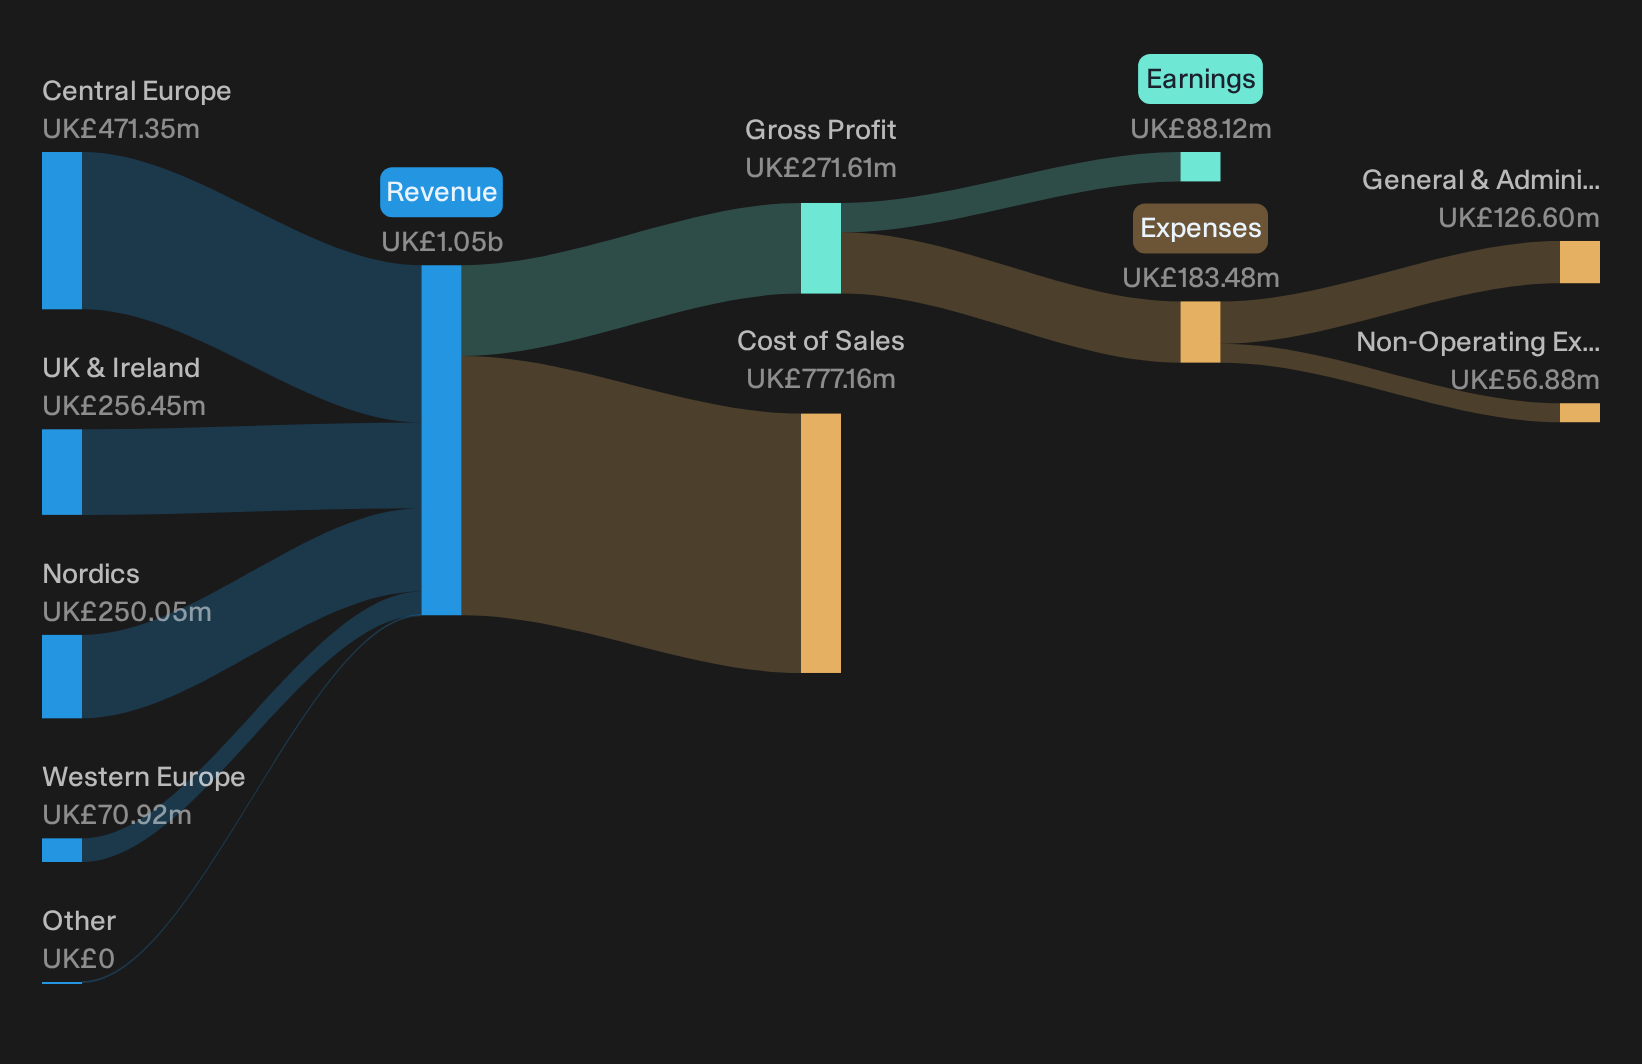
SigmaRoc plugs directly into the UK Transport Infrastructure & Construction theme as a quarried materials group supplying concrete, stone and precast elements for large rail and urban transit projects, generating about £1.05b from construction material products and services on a roughly £1.41b market value.
SigmaRoc taps into the same long-horizon rail and city regeneration spend as the contractors, but from the materials side, so what really matters is how effectively it reshapes its portfolio around the projects where demand and pricing look most resilient.
"The divestment program, which includes selling non-core assets like the concrete operations in the Benelux, is set to refocus the group's footprint on more profitable segments, potentially improving net margins and revenue quality."
The real test is how one pressure point in its funding and project mix ultimately feeds through to margins when infrastructure orders tighten or accelerate.
When that funding and project mix really matters, the full narrative for SigmaRoc shows where SigmaRoc’s reshaped footprint could turn today’s portfolio churn into faster earnings growth.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time every investor is chasing the same breakout, the best entry points can be gone. Scan these curated themes while it still matters and aim to act at an earlier stage.
- Identify under the radar quality before momentum really starts to build by running the 5 high quality undiscovered gems that filters for strong balance sheets and resilient fundamentals.
- Track where long term income strength could meet market hesitation by checking the curated 4 dividend fortresses before yields change in response to shifting demand.
- Review potential opportunities in automation by using the hand picked 92 robotics and automation stocks while expectations are still resetting.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com