


Recent debate around Sinotrans (SEHK:598) was sparked by fresh analyst commentary on its below industry P/E ratio, raising questions about whether the stock’s current valuation fairly reflects earnings power and external risk.
Recent trading has leaned against Sinotrans, with the share price down 7.55% over the past week and 9.48% year to date, while the 1 year total shareholder return has declined 14.17% even after very strong 3 and 5 year total shareholder returns of 97.94% and 153.89%. This pullback suggests investors are reassessing earnings prospects and risk, which helps explain why a below industry P/E ratio is drawing so much attention right now.
Compare Sinotrans with a hand picked 198 high quality undervalued stocks that also combines lower P/E ratios with solid fundamentals and recent share price pressure.
For Sinotrans, a weak recent chart sits against strong multi year gains and a lower P/E than peers. Do you lean into the current reset, or hold out for an even cheaper entry before the valuation stacks up for you?
Most Popular Narrative: 18% Undervalued
On the most followed view of Sinotrans, a fair value of HK$5.31 sits above the latest close of HK$4.35. This puts the spotlight on how future earnings quality and cash generation could bridge that gap.
Ongoing investment in digital transformation, such as CRM system deployment, smart warehouses, and successful commercial rollout of autonomous driving fleets (over 3 million km operated), is supporting operational efficiency gains and cost controls, which should translate into higher margins and improved net profit over time.
See why 5 investors see Sinotrans as 18% undervalued.
Result: Fair Value of HK$5.31 (UNDERVALUED)
Still, the Sinotrans narrative can be knocked off course if weaker domestic logistics demand lingers or if global trade shifts cut volumes and squeeze already thin margins.
Find out about the key risks to this Sinotrans narrative.
Another View On Sinotrans: Cash Flows Tell A Harsher Story
The 18% gap to HK$5.31 might look appealing, but the SWS DCF model points in a different direction. On this view, Sinotrans at HK$4.35 trades far above an estimated future cash flow value of just HK$0.02. Which lens do you trust more when earnings and cash tell such different stories?
For a closer look at how those cash assumptions are built, including growth, margins and discount rate choices, Look into how the SWS DCF model arrives at its fair value.
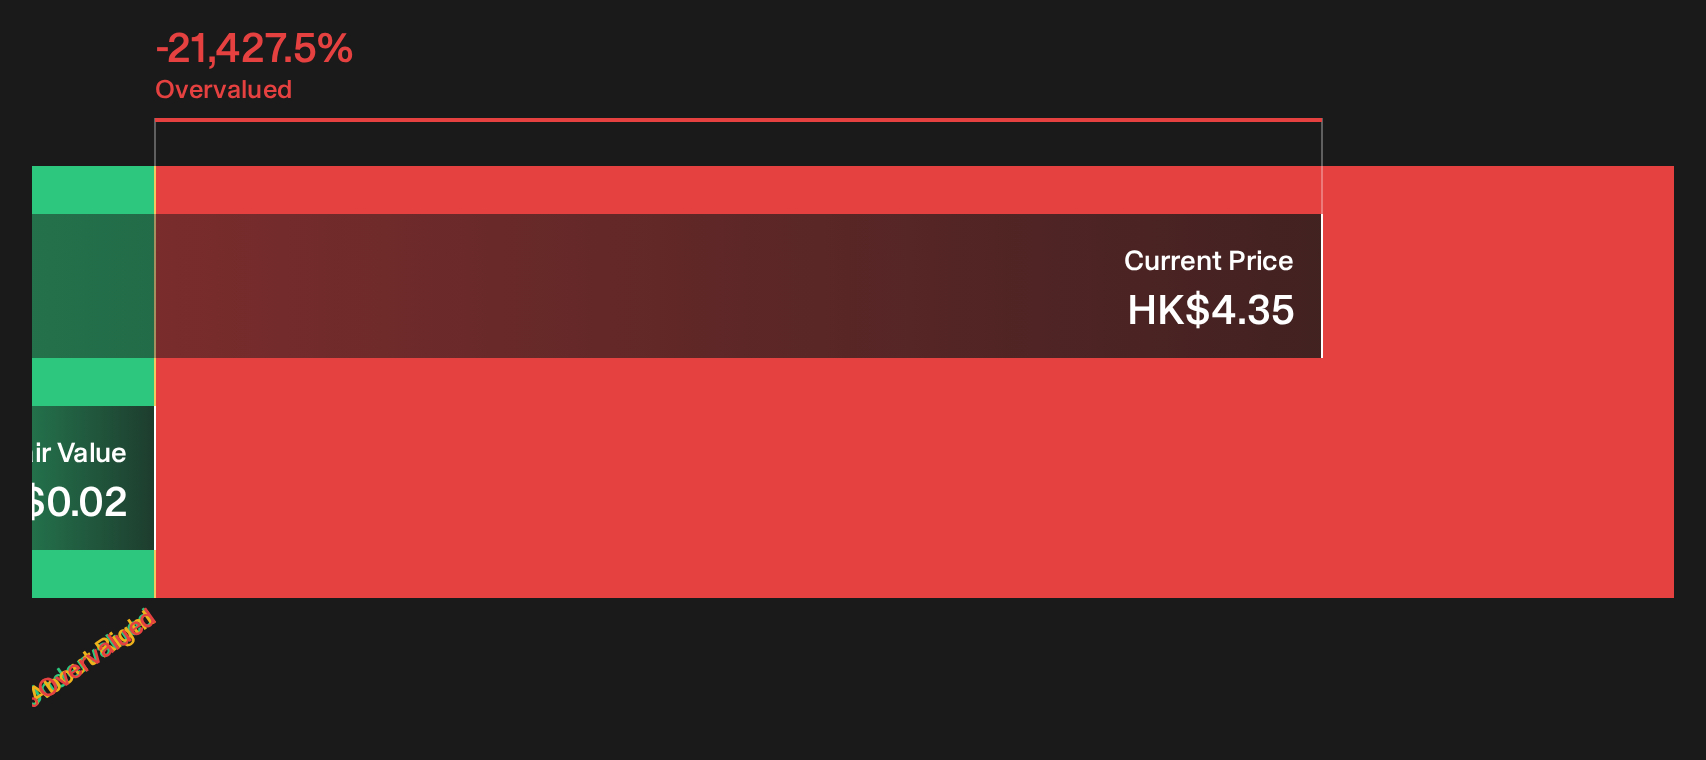
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sinotrans for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sinotrans can feel confusing, so consider acting promptly, reviewing the underlying data for yourself, and weighing both the upside and the downside outlined in our 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Sinotrans?
Sinotrans gives you one angle on value and risk. Do not stop there when the broader market holds other opportunities that may better match your approach.
- Target potential turnaround candidates by scanning the 131 elite penny stocks with strong financials that pair smaller market values with meaningful business foundations.
- Focus on quality at a discount by reviewing the 614 high quality undiscovered gems that combine solid fundamentals with less crowded shareholder registers.
- Protect your downside first and hunt among the 230 resilient stocks with low risk scores where resilient balance sheets and calmer price swings may suit a steadier plan.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com