


ASML Holding has delivered very strong multi year returns, and the question now is whether the current share price can still be explained by its earnings power. With fresh headlines around AI driven chip demand and a packed order book, the stock invites a closer look at what investors are paying for each euro of profit.
- Over the past 3 years the stock has gained 186.2%, which puts a lot of weight on whether its profit base can support that kind of re rating.
- Recent updates around AI focused chip equipment demand and a heavily booked pipeline can influence how durable ASML Holding's earnings and cash generation may be over the coming years.
- There is a second opinion on ASML Holding worth weighing. See what analysts think ASML Holding's shares could be worth.
The issue now is whether today's valuation for ASML Holding is adequately supported by what the business currently earns and is expected to earn.
For additional context beyond ASML Holding and its AI driven chip equipment story, a focused stock screen can be a useful next step, including 55 AI infrastructure stocks.
Does ASML Holding Look Fairly Valued on Earnings?
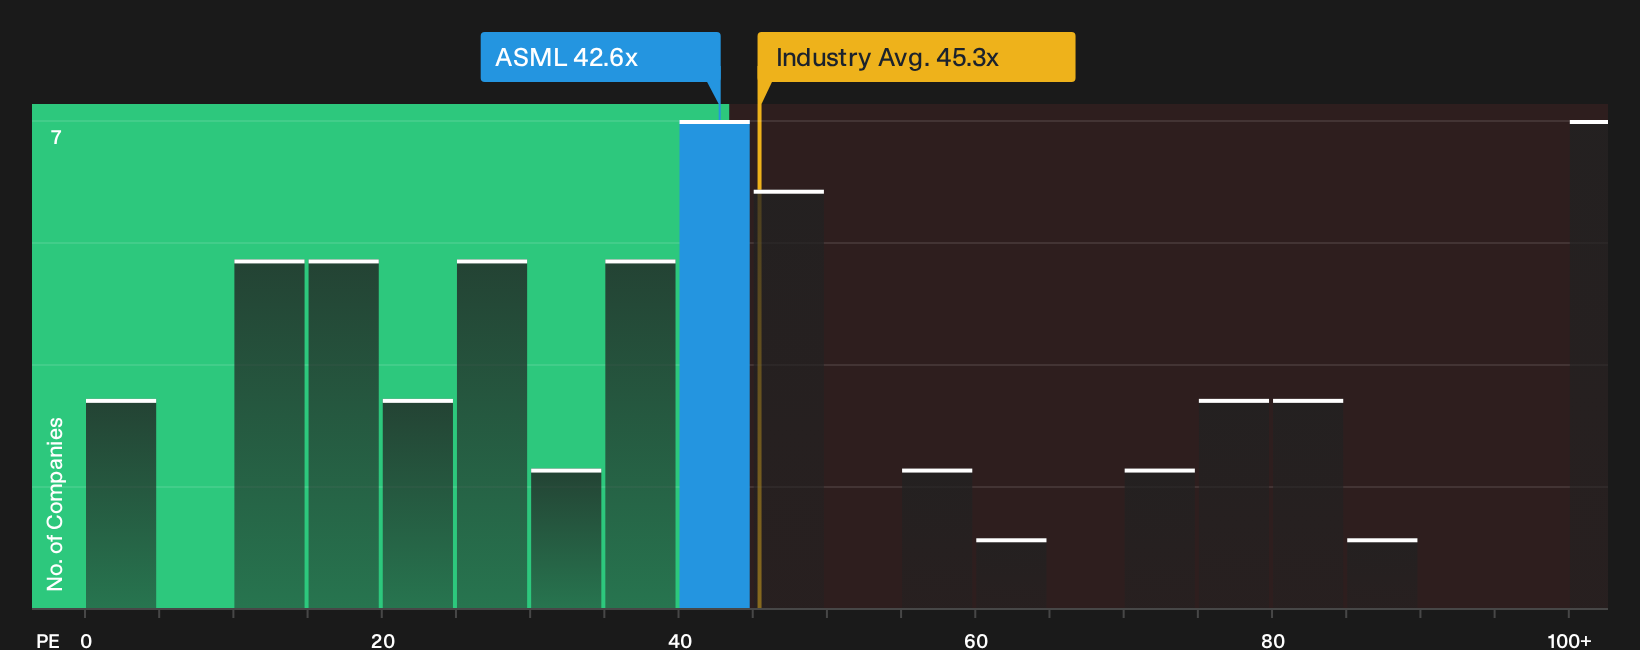
The P/E ratio fits ASML Holding because earnings remain the main yardstick investors watch for capital intensive hardware suppliers with long order cycles. ASML trades on a P/E of 42.6x, which is close to the semiconductor industry average of 45.3x and also very near the peer group on 43.2x. That keeps the stock in the same valuation ballpark as comparable chip equipment players rather than at a steep premium or discount.
The fair value framework, which adjusts for ASML Holding's margins, growth outlook, market size and risk profile, suggests a P/E level slightly below where the shares change hands now. Because recent headlines describe a packed EUV order book through 2027, the current multiple already bakes in a lot of confidence that this demand will translate into earnings power over time. For anyone tracking the stock, the key question is whether future results justify paying a P/E that sits just above this tailored fair value anchor. Explore the numbers behind ASML Holding's P/E valuation.
The ASML Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for ASML Holding pick up where the P/E debate leaves off and explain which growth, margin and earnings paths would need to occur for the stock to appear meaningfully under or over valued versus today's price on the Community page. Each scenario links ASML Holding's potential catalysts and key risks to its own fair value anchor, so you can track over time which storyline appears closer to reality.
One of the top community narratives on ASML Holding: 9% undervalued
"ASML builds the lithography machines that print circuit patterns onto silicon wafers, the most critical and most expensive step in chipmaking..."
Discover why this Narrative puts ASML Holding at 9% undervalued.
The share price is only one piece of the ASML Holding puzzle
Price multiples show what investors pay today, but the real curiosity sits in where professional forecasts see ASML Holding's profits and cash flows a few years down the road. Explore where analysts expect ASML Holding to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com