


Intapp (INTA) drew fresh attention after announcing that accounting firm Mauldin & Jenkins went live on its Employee Compliance platform, shifting from email-driven processes to a single automated system for personal independence monitoring.
Intapp’s recent client win comes amid strong momentum in the share price, with a 30 day share price return of 22.31% and a 90 day move of 57.62% contributing to a 1 year total shareholder return of 15.58%, indicating that sentiment has improved after a flatter year to date.
Scan other software players delivering real-world efficiency gains with our curated list of 35 high quality undervalued stocks, which pairs resilient cash flows with balance sheets built to support long-term client wins like Intapp’s.
After a sharp swing higher and a share price now above the average analyst target, Intapp presents a simple test for fresh capital: Does the current valuation still leave enough upside to justify the risk?
Most Popular Narrative: 6.5% Overvalued
Intapp closed at $44.29, while the most followed narrative pegs fair value at $41.57. This suggests a modest valuation gap based on detailed long term cash flow analysis.
Intapp's recent investments in AI capabilities, including the launch of Intapp DealCloud Activator and the transformed Intapp Time product, are designed to drive client engagement and operational efficiencies. These developments are intended to enhance product appeal and encourage cloud adoption among existing and potential clients.
See why 15 investors see Intapp as 7% overvalued.
Result: Fair Value of $41.57 (OVERVALUED)
Still, this story can break if partner-led delivery eats into profitability or if the shift to cloud causes client churn that undercuts those AI-driven ambitions.
Find out about the key risks to this Intapp narrative.
Another View: Intapp Through A Cash Flow Lens
Price targets and fair values do not agree. While the most popular narrative tags Intapp as 6.5% overvalued at $44.29 versus a $41.57 fair value, the Simply Wall St DCF model points to a future cash flow value of $60.63, which implies the shares trade at a discount instead.
The gap between a DCF that supports $60.63 and an analyst target of $41.57 puts the focus squarely on the assumptions behind future earnings, margins, and discount rates. Which set of expectations do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
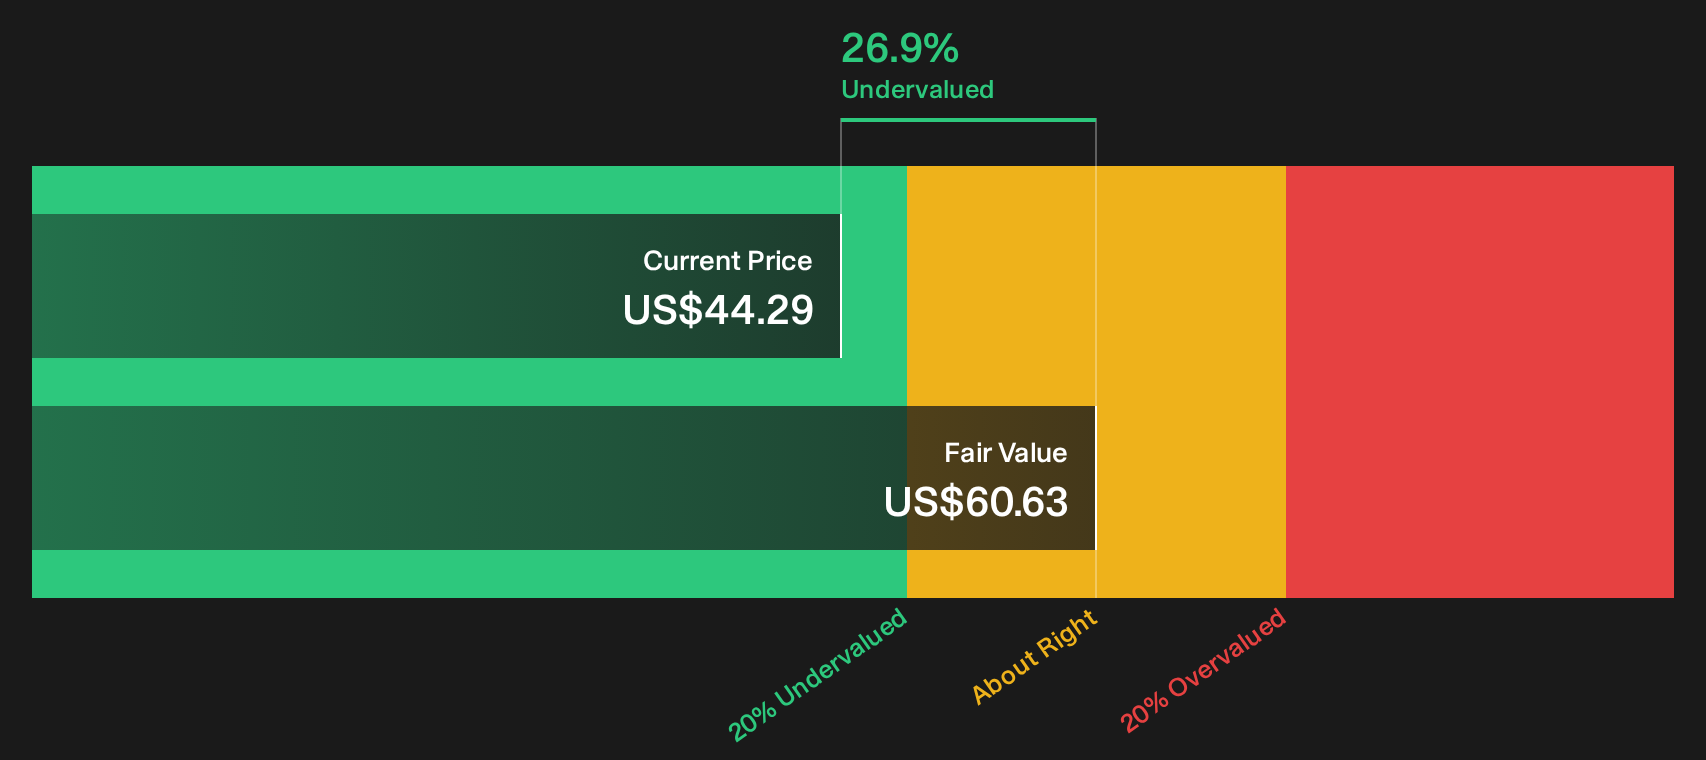
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Intapp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Intapp's value story are clear, so move quickly, scrutinise the assumptions, and decide where you stand by reviewing the 2 key rewards.
Looking for more investment ideas beyond Intapp?
Do not stop your research with Intapp. Broader context across different types of opportunities can sharpen your judgment and keep your watchlist ahead of the crowd.
- Explore smaller companies that already show financial strength by scanning the 12 elite penny stocks with strong financials.
- Focus on quality at a reasonable entry point by reviewing the 35 high quality undervalued stocks that combine stronger cash flow profiles with disciplined balance sheets.
- Build your income watchlist by concentrating on resilient payers through the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com