


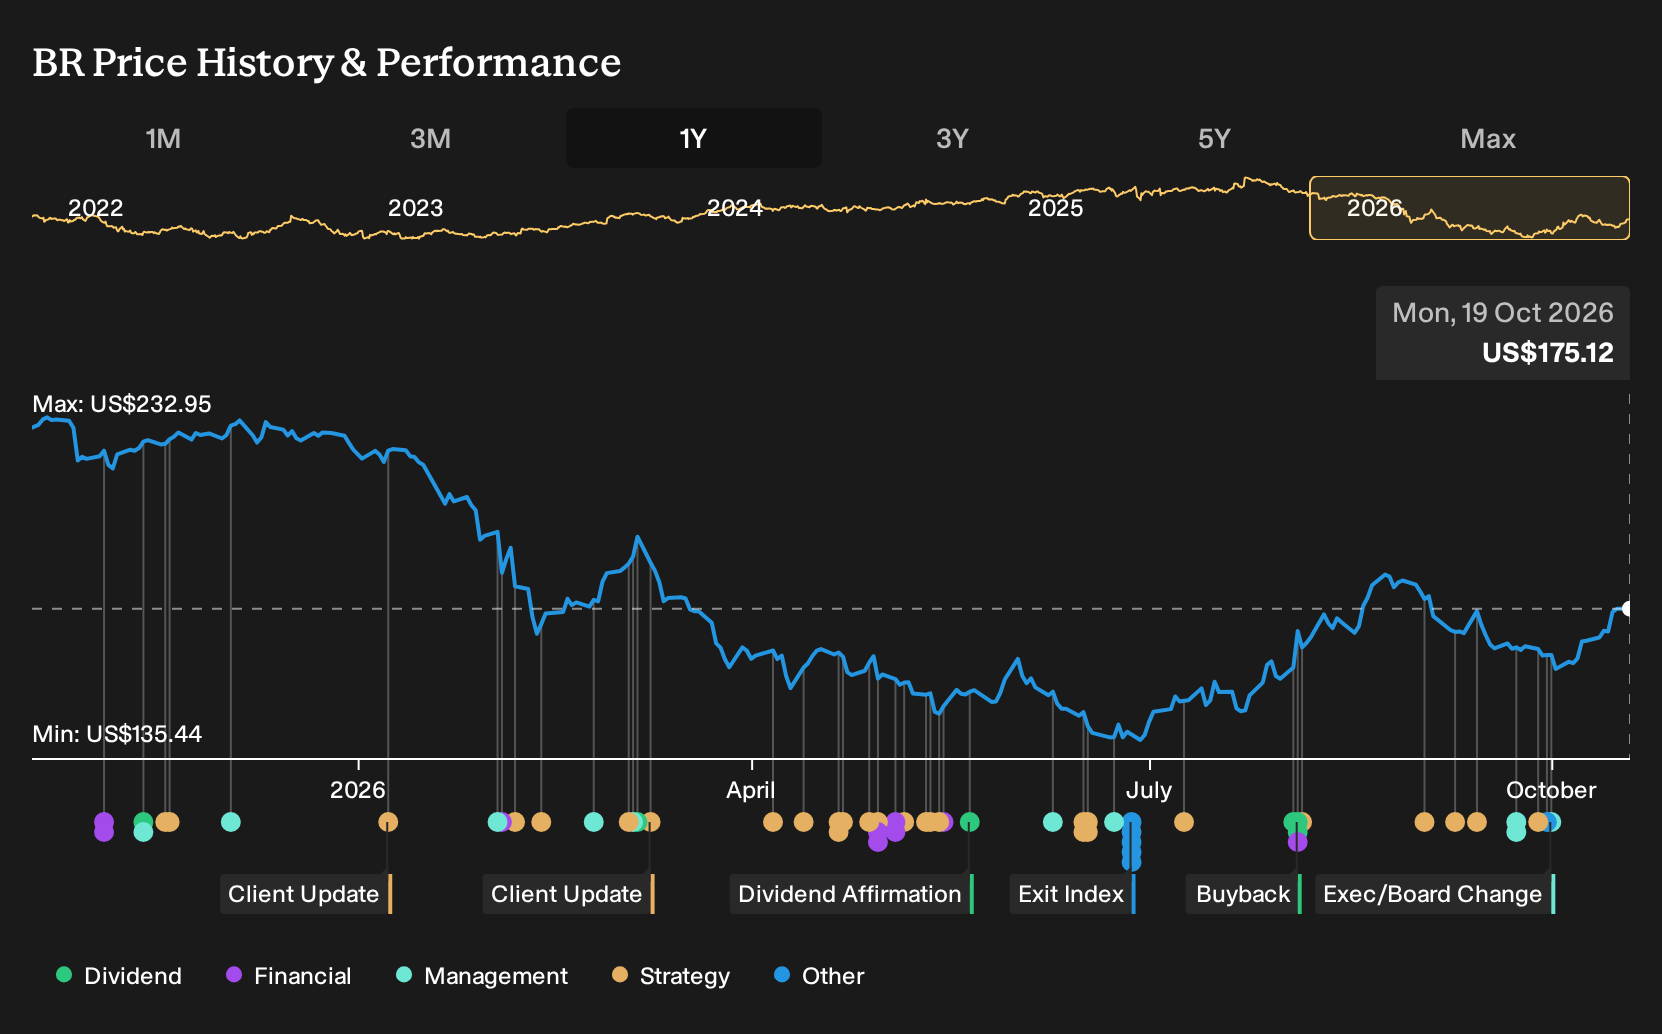
- Broadridge Financial Solutions reported fiscal 2026 revenue growth of 8% and adjusted EPS growth of 12%, paired with a 12% dividend increase and a focus on agentic AI to support its regulatory and communications platforms.
- The combination of higher earnings, a larger dividend, and accelerated AI driven digitization directly ties Broadridge Financial Solutions' operating performance to its long term push toward higher value recurring services.
- We will now assess how this earnings and dividend step up at Broadridge Financial Solutions could reshape the existing investment narrative.
Scan how Broadridge Financial Solutions' AI driven shift toward higher value recurring services compares with other stocks pursuing similar quality and income profiles in the 35 high quality undervalued stocks.
Broadridge Financial Solutions Investment Narrative Recap
To own Broadridge Financial Solutions, you need to believe its core model of outsourced regulatory communications and transaction technology remains essential as markets digitize. The recent 8% revenue and 12% adjusted EPS growth, alongside the dividend increase, reinforces that the existing platform is still pulling its weight despite concerns about disruption from digital trading and new rails.
The near term swing factor still looks like how event driven revenues normalize against that expanding base of recurring, AI supported services. The main operational risk is that moderation in those episodic fees and Broadridge Financial Solutions' high debt load tighten financial flexibility at the same time, especially if customer onboarding or digital communication volumes slow.
The clearest announcement tied to this earnings update is management’s emphasis on agentic AI across Broadridge Financial Solutions' regulatory and communications stack. This focus connects directly to the existing catalyst list, which already highlighted proxy digitalization near 95% for equities and 80% for funds and four years of double digit digital communications growth.
As AI tools move deeper into workflows, investors will likely watch three things: whether operational agents actually deliver the targeted US$25m productivity gains in fiscal 2027, whether BondGPT and other trading agents help win more Global Technology and Operations mandates, and whether these efficiencies offset any pressure from moderating event driven revenue.
Broadridge Financial Solutions' current revenue profile is tied to analyst expectations that revenues will reach US$8.7b and earnings will be about US$1.3b by 2029. This implies 5.1% yearly revenue growth and an earnings increase of roughly US$0.2b from about US$1.1b today.
Uncover why Broadridge Financial Solutions' fair value indicates a 22% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate angle on Broadridge Financial Solutions is the bullish view that tokenization could matter far more than consensus expects. Those optimistic analysts were modeling revenue of about US$8.7b and earnings near US$1.2b by 2029 with a 28.4x P/E. You can compare that pre news optimism with today’s AI and dividend update and decide whether those expectations still feel realistic.
Explore 5 other Broadridge Financial Solutions fair value estimates, including one that suggests as much as 107% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Broadridge Financial Solutions research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Broadridge Financial Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Broadridge Financial Solutions' overall financial health at a glance.
Looking for more Broadridge Financial Solutions style investment ideas?
If this Broadridge Financial Solutions update has you rethinking where dependable earnings, cash flow resilience, and income fit in your portfolio, it can help to scan a broader field of stocks that share some of these qualities but with very different risk and return profiles.
- If you want potential upside paired with stronger fundamentals, review a curated 20 high quality undiscovered gems that may not yet be widely followed by the market.
- For investors who care most about balance sheet strength and business durability, filter for companies through the list of solid balance sheet and fundamentals (25 results) to see which ones currently combine financial resilience with fundamental support.
- If capital preservation comes first for you, start with a 32 resilient stocks with low risk scores that focuses on businesses with lower risk scores and more stable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com