


Lake Success, New York-based Broadridge Financial Solutions, Inc. (BR) is a U.S.-based financial technology company that provides investor communications, securities processing, and technology solutions to banks, broker-dealers, asset managers, wealth management firms, and publicly traded companies. Its services include proxy voting and shareholder communications, regulatory reporting, trade processing, data analytics, and digital platforms that support capital markets and investment management. The company has a market cap of $19.8 billion currently.
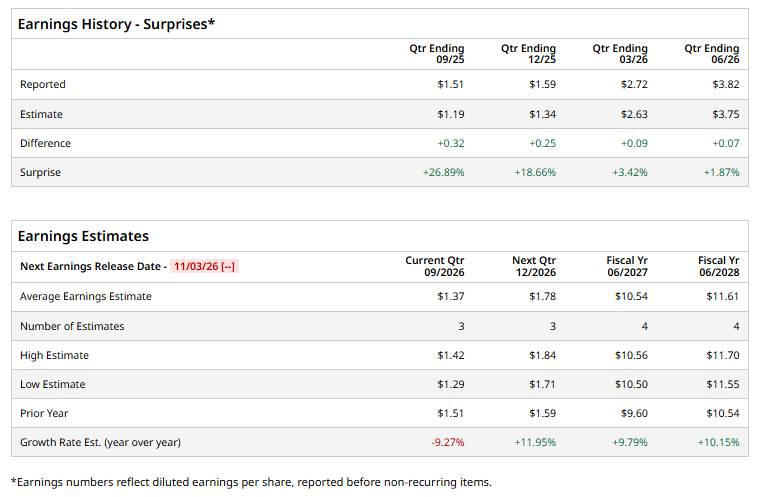
BR is expected to release its Q1 2027 earnings soon. Ahead of the event, analysts expect the company’s EPS to be $1.37 on a diluted basis, down 9.3% from $1.51 in the year-ago quarter. On the positive side, the company has exceeded Wall Street’s EPS estimates in each of its last four quarters.
For fiscal 2027, analysts project the company’s EPS to be $10.54, up 9.8% from $9.60 in fiscal 2025. Moreover, its EPS is expected to rise by 10.2% year over year to $11.61 in fiscal 2028.
BR stock has declined 23.5% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 15.4% rise and the State Street Technology Select Sector SPDR ETF’s (XLK) 30.5% rise during the same time frame.
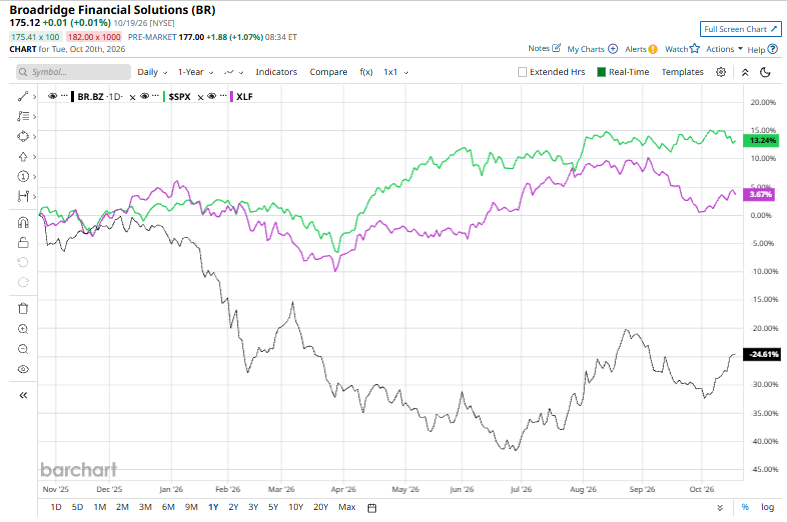
Broadridge Financial Solutions has struggled to keep pace with the broader market over the past year, as its steady but relatively modest growth has failed to excite investors amid the AI-driven rally in technology stocks. While the financial technology company continues to benefit from recurring revenue and growing demand for its investor communications and securities processing solutions, its measured growth outlook has done little to boost investor enthusiasm.
Analysts are moderately bullish about BR, with the stock having a “Moderate Buy” rating overall. Among the nine analysts covering the stock, one is recommending a “Strong Buy,” three suggest a “Moderate Buy,” and five suggest a “Hold.” BR’s average analyst price target of $203.50 offers a 16.2% upside potential.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.