


Without a clear single event driving headlines, interest in HASEKO (TSE:1808) today centers on how its share performance and current fundamentals line up for investors watching Japan’s real estate and construction sector.
HASEKO’s share price has slipped in the short term, with a 30 day share price return down 3.68% and year to date share price return down 15.19%. However, the 1 year total shareholder return of 9.27% and 5 year total shareholder return of 118.78% indicate momentum built over a longer holding period as investors reassess both growth prospects and risk around the current ¥2,632.5 level.
Compare HASEKO’s recent pullback with other companies that combine real estate exposure and construction strength by scanning our hand picked list of solid balance sheet and fundamentals (22 results) for your next watchlist candidate.
The recent slide in HASEKO’s share price could mirror shifting sentiment toward Japan’s condo cycle, or it could understate a business still posting revenue and net income growth. Which picture does the current valuation paint?
Price-to-Earnings of 11x: Is it justified?
On earnings, HASEKO trades on a P/E of 11x at the last close of ¥2,632.5, which puts the stock on a richer multiple than both its direct peers and the wider Consumer Durables sector.
The P/E ratio compares the current share price to net profit per share. For a real estate and construction focused group like HASEKO, it reflects what investors are willing to pay today for each unit of earnings given its condo development cycle, management and operation income, and overseas activity.
HASEKO’s current P/E of 11x screens as expensive against the JP Consumer Durables industry average of 9.8x and also above the peer average of 8.4x. That premium sits in sharp contrast to the estimated fair P/E of 16x, which signals the market is applying a more cautious earnings multiple than the level the fair ratio suggests it could move toward over time.
Explore the SWS fair ratio for HASEKO.
Result: Price-to-Earnings of 11x (ABOUT RIGHT)
Still, HASEKO’s condo-heavy exposure and reliance on construction-related revenue leave the share price vulnerable if project pipelines or buyer appetite weaken.
Find out about the key risks to this HASEKO narrative.
Another view on HASEKO’s value
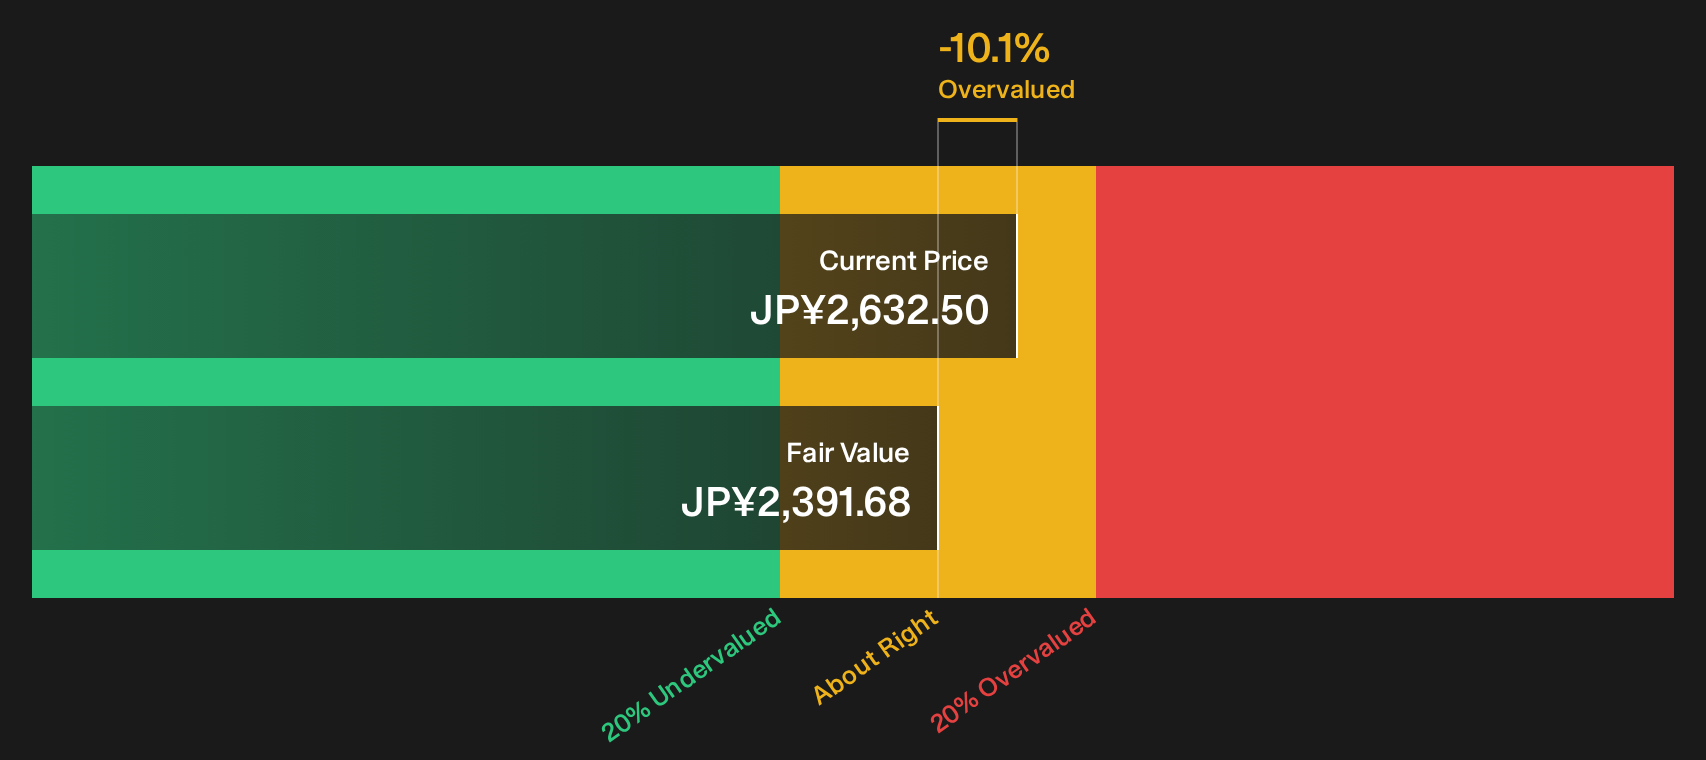
The P/E discussion points to HASEKO looking reasonably priced, yet the SWS DCF model tells a tougher story. On that framework, the estimated future cash flow value sits at ¥2,391.68 per share while the market trades at ¥2,632.5, which implies the stock is pricing in more optimism than the cash flow math supports. Which lens do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out HASEKO for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on HASEKO’s value story call for your own judgment. Move quickly through the numbers, weigh both sides, and then check the 4 key rewards and 1 important warning sign
Looking for more HASEKO style investment ideas?
Do not stop your research with HASEKO. Use the Simply Wall Street screener to spot fresh opportunities that fit the way you like to invest.
- Target companies that combine quality and a potential valuation gap by scanning our 13 high quality undervalued stocks for ideas that might deserve a closer look.
- Strengthen the defensive side of your portfolio by reviewing a 20 resilient stocks with low risk scores that focuses on resilience when conditions turn rough.
- Hunt for future leaders before they hit the headlines by running through the 73 high quality undiscovered gems that highlight strong fundamentals yet limited attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com