


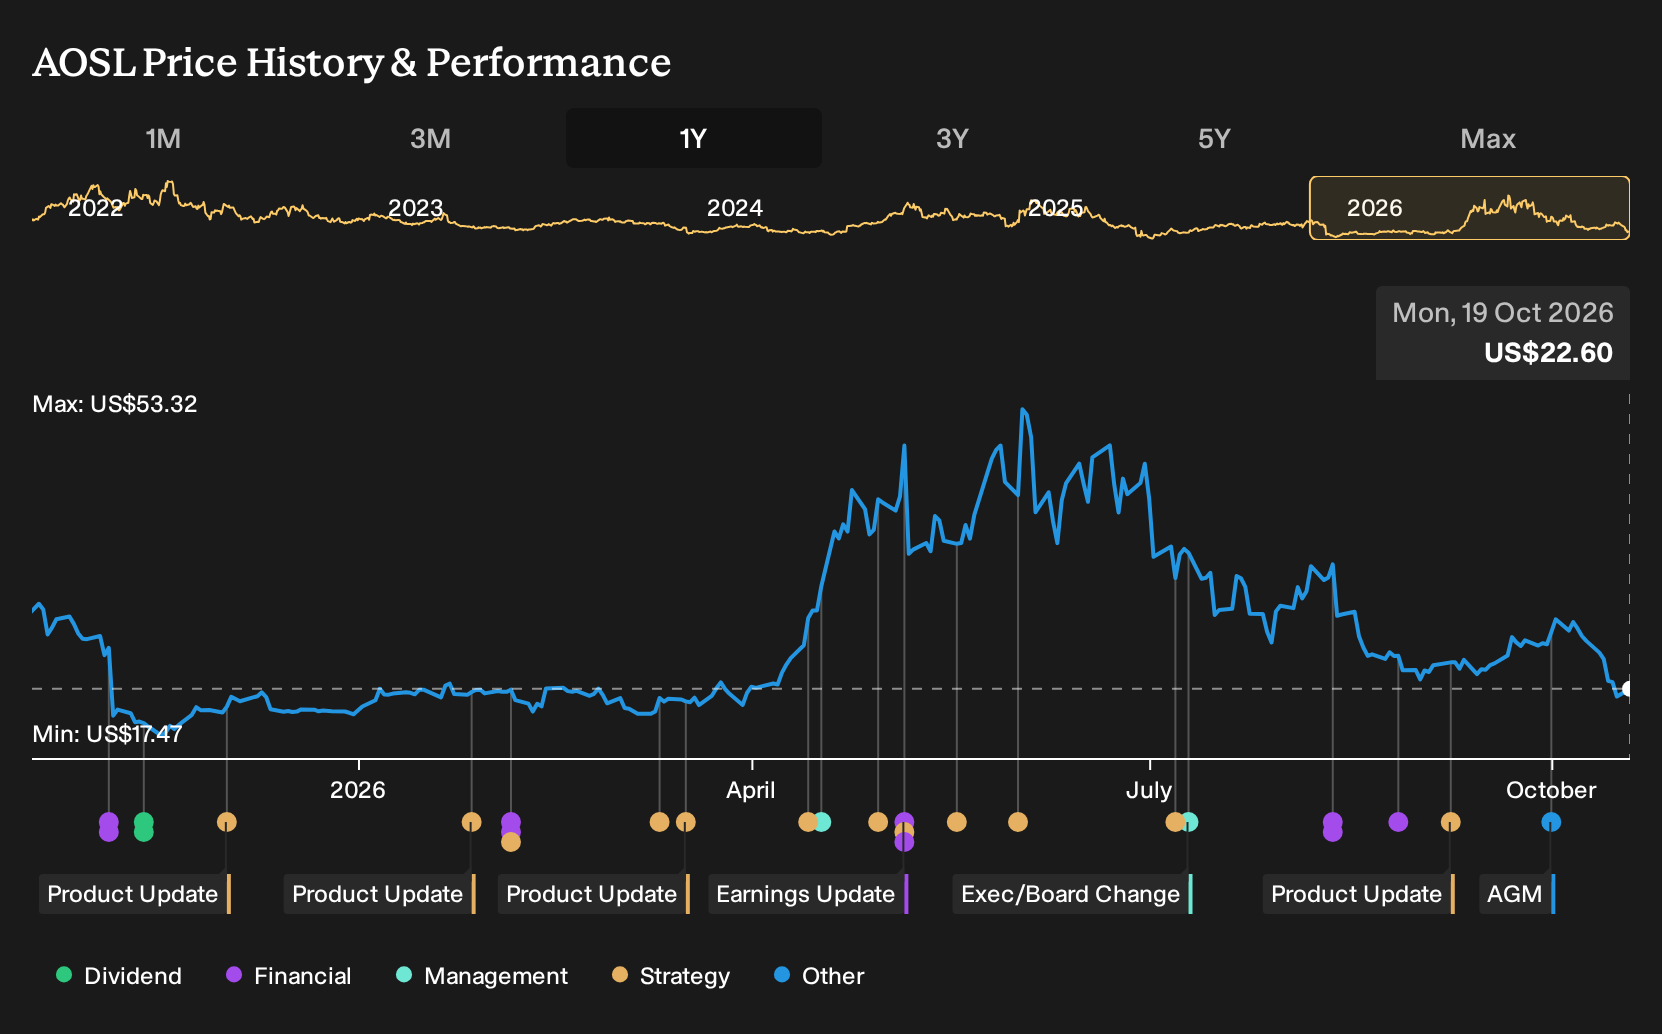
Alpha and Omega Semiconductor has just reported fiscal 2026 results that showed revenue lower than a year earlier while the net loss narrowed sharply, and AI-focused products featured heavily in recent announcements. Holding Alpha and Omega Semiconductor over the past year would have meant a 29.3% loss, including dividends. If you had weighed the bullish US$35 view against the bearish US$25 case back in October 2025, how would you now judge whether AI infrastructure upside offsets the China and margin risks?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Alpha and Omega Semiconductor is not the only name tied to this theme. Zero in on 55 AI infrastructure stocks and compare how each one is priced.
The Two Stories Investors Were Choosing Between On Alpha and Omega Semiconductor
The shares cost US$30.46 at the start of the period, and Alpha and Omega Semiconductor sat between two clear narratives about where the business might be heading.
The bullish case put Fair Value at US$35. That view leaned on 6.8% revenue growth assumptions and expected profit margins to move from a loss toward 14.1%, supported by demand related to AI, graphics, renewables and e-mobility.
The bearish side saw Fair Value at US$25. That scenario assumed 4.1% revenue growth and focused on geopolitical risk around China based supply chains, which could pressure margins even if profitability improved.
What The Results Changed In The Alpha and Omega Semiconductor Argument
Alpha and Omega Semiconductor leaned into AI infrastructure, with AI linked revenue more than doubling sequentially and rising over 40% year on year, which backed the bullish focus on advanced computing demand. The same period still showed pressure, as revenue slipped from US$176.484m in Q4 2025 to US$170.371m in Q4 2026 while the firm remained loss making.
Net income loss narrowed from US$77.059m to US$13.063m and net margin improved from a loss of 43.7% to a loss of 7.7%, so the profitability part of both narratives stayed unproven. The lesson is clear. When a story leans on margin recovery, it is important to keep checking the reported net margin alongside any segment growth headline.
What Alpha and Omega Semiconductor’s Drop Now Asks You To Believe
Today Alpha and Omega Semiconductor trades at US$22.6, and the selected Narrative’s Fair Value sits above the current price based on its own assumptions about the AI oriented product mix and future profitability.
The key question is whether a buyer now believes AI and advanced computing power solutions can eventually cover higher R&D, CapEx and recent cash flow strain enough for that mix shift to stick.
"The main thing that has to go right is that Alpha and Omega Semiconductor successfully shifts its mix toward higher value AI, server and premium device power solutions while absorbing higher R&D and CapEx so that margin improvements and design wins translate into sustained profitability."
The price and this Narrative do not agree. → Uncover what this Narrative says Alpha and Omega Semiconductor is actually worth
Looking Beyond Alpha and Omega
Alpha and Omega keeps you focused on AI hardware and power. It also quietly raises a bigger question about what all that computing actually needs.
Every new chip design still relies on reliable connections, storage access and traffic control between machines. One step away from device level components, another business concentrates on that glue layer.
Its hardware and software help move data, manage congestion and keep private infrastructure running. Think of it as plumbing for traffic, not the eye catching faucet.
As AI systems, cloud tools and enterprise software add complexity, that plumbing role matters more. The intriguing part is how digital infrastructure focus might reshape where you look next.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 95% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com