


S&T Bancorp has delivered a powerful share price run over the past few years, which naturally puts a spotlight on what the bank is actually earning on the capital it deploys. With the stock recently closing at US$48.49, the question is whether those returns on capital are strong enough to justify where the market is pricing the business today.
- Over the last 3 years the stock has returned about 116.3%, which raises the stakes on whether the bank's returns on its capital line up with that kind of share price performance.
- For a regional lender like S&T Bancorp, the key drivers of those returns are often its net interest margins, credit quality, and how efficiently it can turn its deposit base into profitable lending without stretching its balance sheet.
- Prefer to judge S&T Bancorp on earnings? See why S&T Bancorp's 12.2x P/E tells a different valuation story.
For investors, the debate is whether S&T Bancorp's recent share price level is properly supported by the returns it earns on its capital today and what that suggests about its intrinsic value estimate.
If you are weighing whether S&T Bancorp's returns on capital justify the current share price, it can help to compare that lens with a focused list of 35 high quality undervalued stocks.
Is S&T Bancorp a Bargain on Excess Returns?
The Excess Returns model looks at what S&T Bancorp earns above its cost of equity and capitalises that stream. For this bank, the framework starts with a Book Value of $39.81 per share and a Stable Book Value estimate of $42.29 per share based on inputs from 6 analysts. That equity base is paired with a Stable EPS figure of $4.15 per share. This implies the institution is expected to keep generating meaningful profits on its balance sheet rather than relying on rapid expansion.
The key hinge is the spread between what S&T Bancorp earns and what its shareholders require. The model uses a Cost of Equity of $3.06 per share and an Excess Return of $1.09 per share, supported by an Average Return on Equity of 9.80%. When those excess earnings are capitalised, the projections from the Excess Returns approach put the estimated intrinsic value substantially above the current share price of US$48.49. This is where investors may want to compare the trading price with the full valuation detail. Find out what S&T Bancorp could be worth using our Excess Returns estimate.
The S&T Bancorp Narrative: What Would Justify Today's Price?
S&T Bancorp's valuation debate naturally leads to Simply Wall St Narratives. These show what mix of future growth, margins and earnings paths would need to play out for the stock to be worth materially more or less than today's price on the Community page. Each scenario connects its number to a clear view on how S&T Bancorp's growth, profitability and risk profile might evolve, so you can return to that thesis as fresh information comes through.
One of the top community narratives on S&T Bancorp: 9% undervalued
"The thesis on S&T Bancorp has shifted from a focus on competitive and structural headwinds to a more constructive view that centers on deposit strength, disciplined margin management, capital return, and efficiency..."
Discover why this Narrative puts S&T Bancorp at 9% undervalued.
An unresolved piece of the S&T Bancorp story
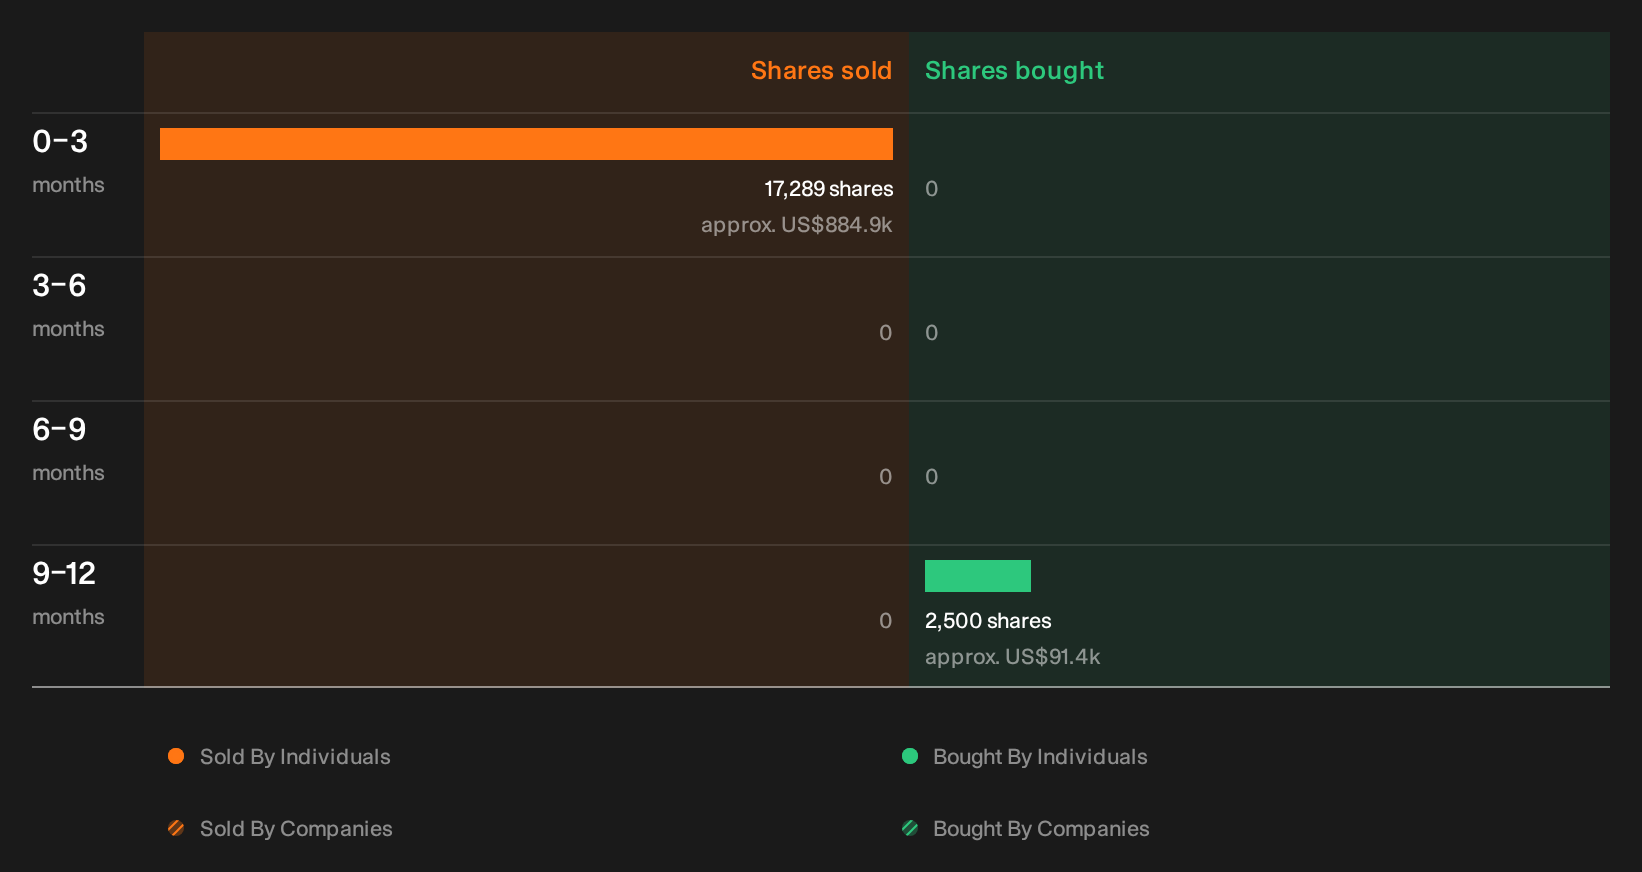
There is one thread in the S&T Bancorp picture that sits outside the valuation work so far, with our checks highlighting recent insider share disposals whose sellers, sizes and potential meaning are left for you to review. See the recent insider selling flagged for S&T Bancorp.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com