


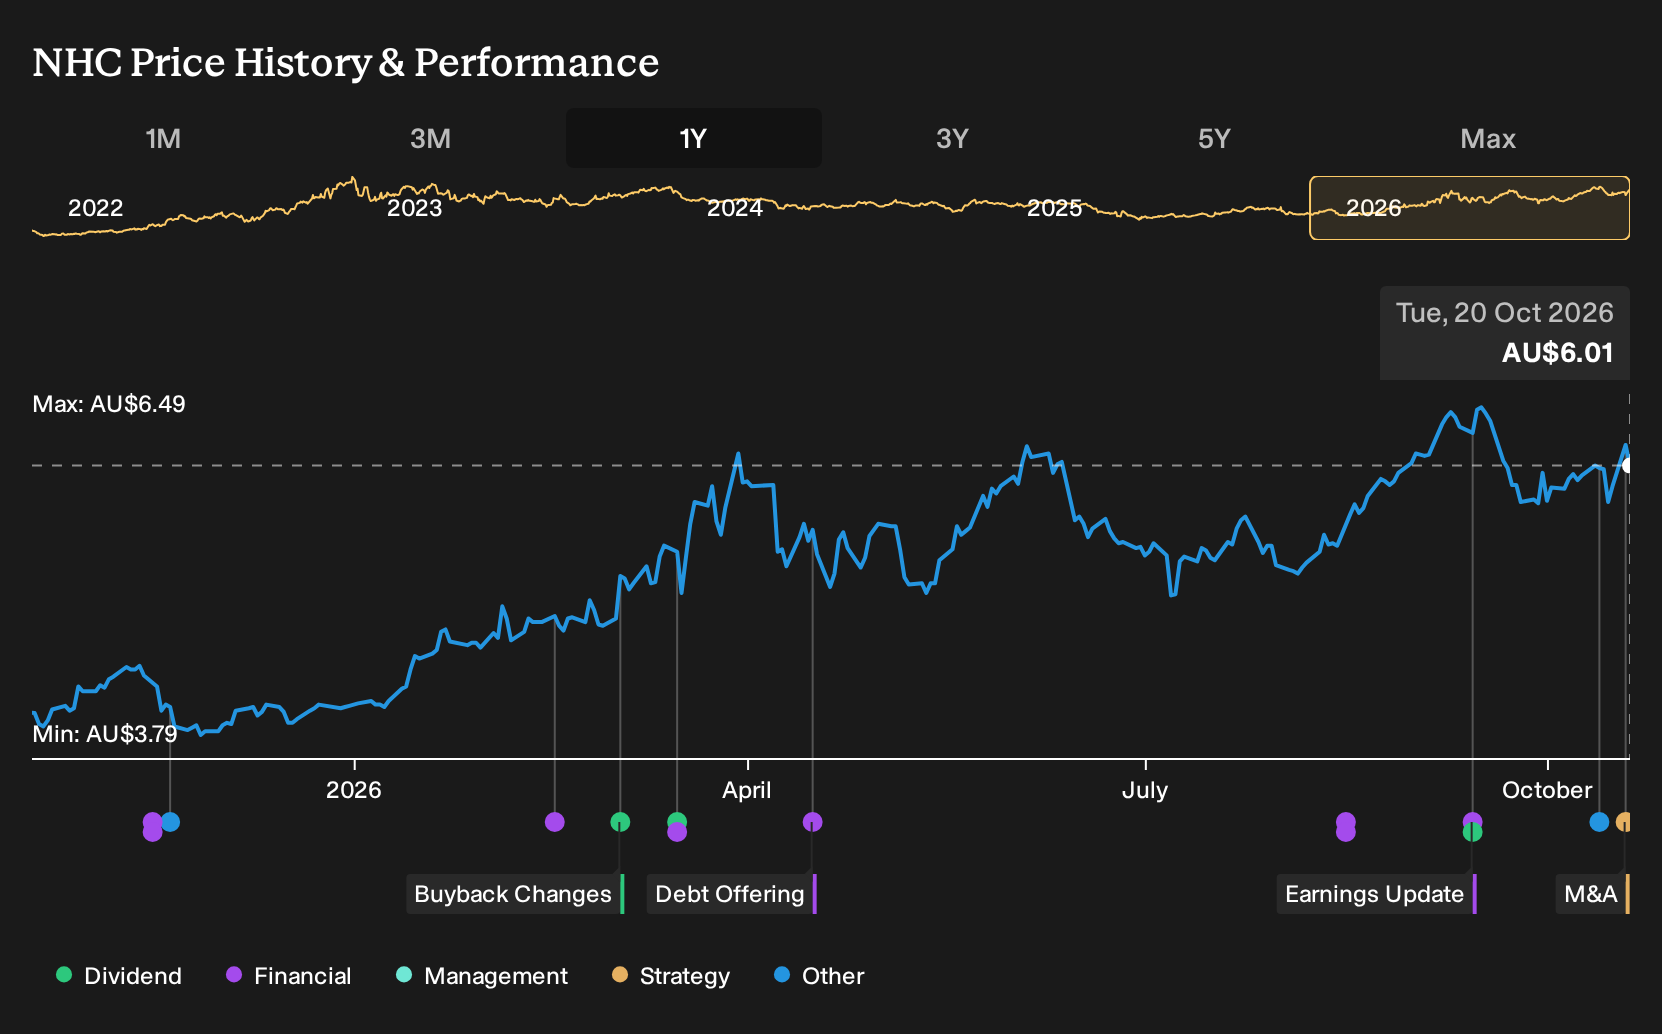
If you backed New Hope through a year of heated debate about coal’s future, the payoff has been hard to ignore. Investors who held New Hope over the past year are up 65.2%, including dividends. The question is what early buyers were really weighing on 20 October 2025. If urbanising Asian demand and port upgrades were on one side of the scales, and ESG pressure was on the other, which argument would have persuaded you to commit fresh capital?
This theme extends beyond New Hope. See which of 36 elite gold producer stocks may still merit a closer look.
The Two Stories Investors Were Debating On New Hope
The shares cost A$3.97 at the start of the period, and New Hope owners had to decide which story about coal and capital would guide their next move.
The bullish view pointed to a Fair Value of A$5.7, a notional target based on assumptions that revenue could rise 5.8% a year and profit margins reach around 27.3% with a future P/E of 9.2x.
The bearish camp used a Fair Value of A$2.8, built on the same 5.8% revenue growth assumption but with a future P/E of 4.5x and rising ESG pressure cited as a key risk to long term coal demand.
What The Results Changed For New Hope
New Hope’s later move to acquire the remaining stake in Malabar Resources for A$1.3b supported the bullish focus on export growth and long asset life. Reported numbers were more mixed. Revenue and profit in H2 2026 were higher than H2 2025, yet net margin slipped from 13.1% to 11.2%. The evidence cut both ways.
The swing factor here was profitability quality. When weighing similar stories elsewhere, focus on whether higher sales and earnings are backed by stable or improving margins, not just bigger headline figures.
What New Hope’s Price Already Assumes
New Hope now trades at A$6.01 after a 65.2% total return over the past year. The selected Narrative’s Fair Value sits below that level, which implies the current P/E already prices in a lot of optimism about future earnings power.
The Narrative leans on concerns about long term coal demand, financing access and regulation. For today’s price to hold up, a buyer has to believe profitability can withstand tighter ESG policies and cleaner energy alternatives without a meaningful squeeze on cash generation.
"Heavy dependence on coal and tightening ESG policies threaten long-term revenue stability, asset value, and access to affordable capital. Rising costs, regulatory pressures, and clean energy advances are expected to erode profitability and shrink the company's future market."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond New Hope
New Hope anchors one side of your energy exposure. The fuel is familiar and the cash profile clear.
Coal delivers income today, yet you may want exposure suited to tighter carbon rules.
One large integrated producer still drills for oil and gas, while expanding into electricity, biofuels and lower carbon gases.
Its mix aims for resilience if commodity prices move sharply or methane rules tighten further.
If New Hope covers one energy story for you, this other business sketches a very different one.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 24% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com