


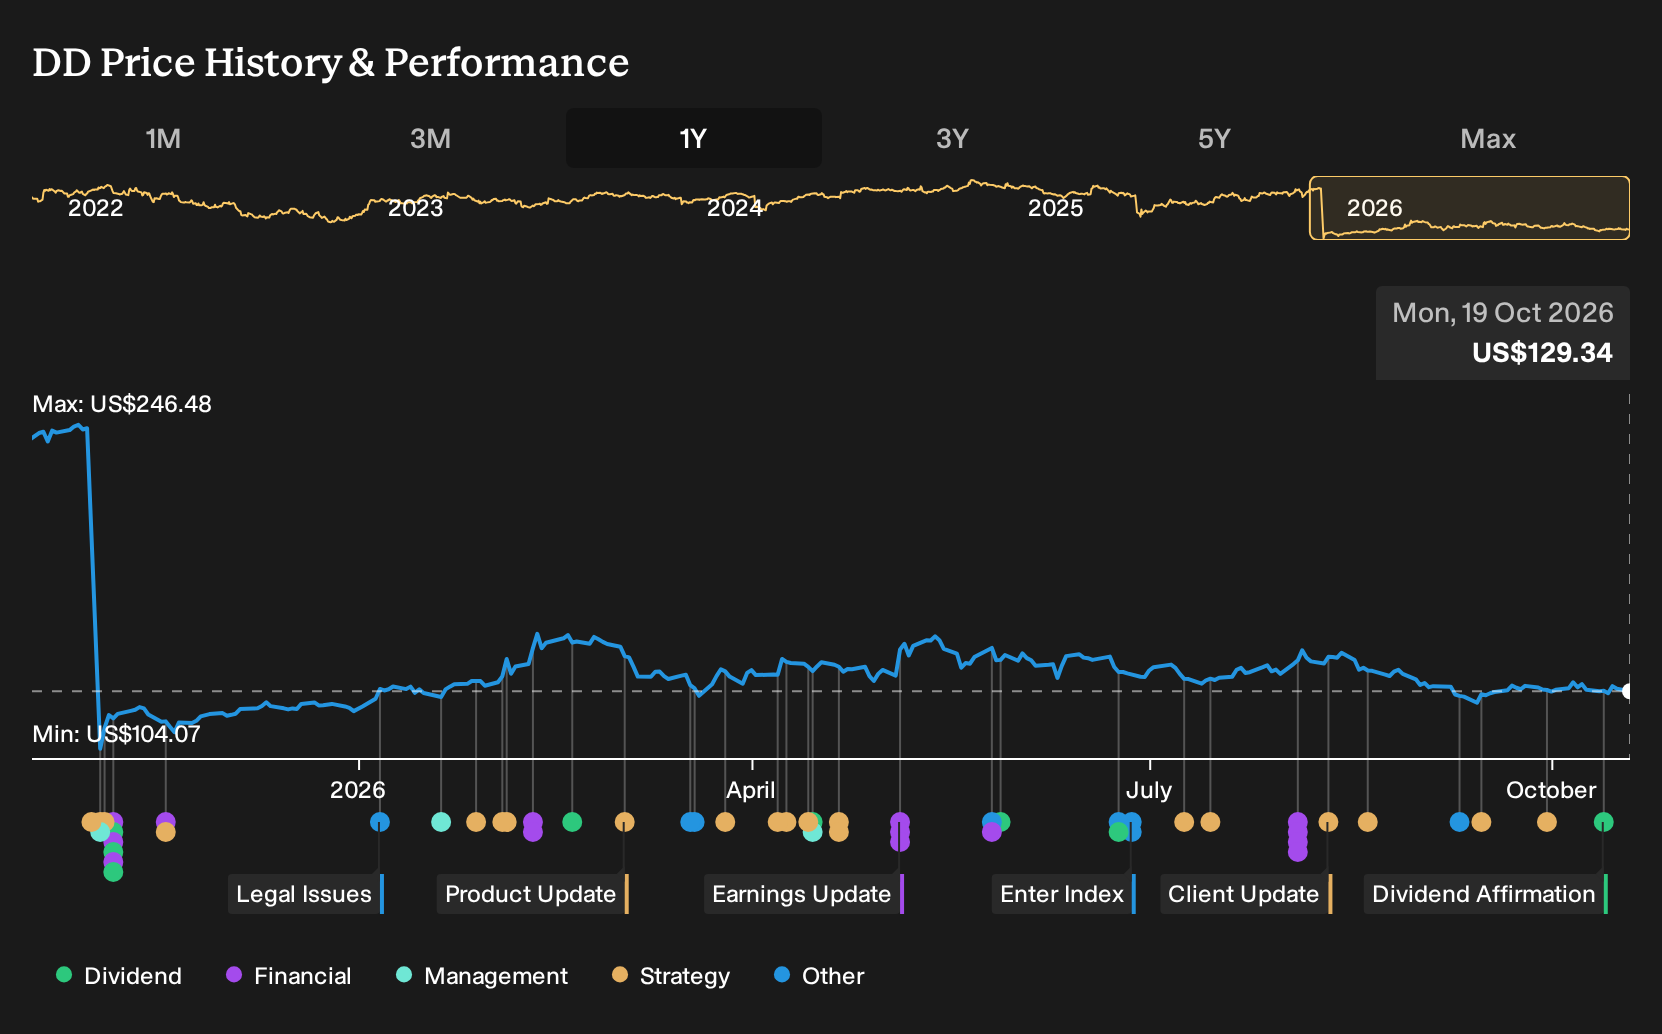
- DuPont de Nemours announced a 3-for-1 stock split, with the corporate action scheduled to be reflected across its listings on June 24, 2026, and previously confirmed a quarterly dividend of $0.60 per share payable on December 15, 2026 to holders of record on November 30, 2026.
- This combination of stock split and ongoing cash dividends highlights DuPont de Nemours' current approach to capital returns, along with its focus on a more concentrated industrial portfolio in healthcare, water, and diversified industrial markets.
- We will now examine how DuPont de Nemours' investment narrative could be influenced by the 3-for-1 stock split announcement.
Scan how DuPont de Nemours' stock split and dividend policy compare with other cash-return stories by reviewing the hand picked 8 dividend fortresses right now.
DuPont de Nemours Investment Narrative Recap
To be comfortable owning DuPont de Nemours, you need to believe the refocused portfolio in healthcare, water and diversified industrials can turn consistent execution on productivity and R&D into sturdier earnings, despite only moderate expected revenue growth. The most important short term swing factor is how effectively management converts its cost and quality programs into cleaner margins and cash generation.
The biggest risk right now sits in the background, not the headline. Environmental and PFAS related liabilities, plus input cost inflation and slower water project activity in parts of the Middle East, could absorb cash that might otherwise support reinvestment or shareholder returns. The latest stock split and dividend news does not materially change those operational drivers.
The dividend affirmation at US$0.60 per share, payable on December 15, 2026, is the most relevant announcement alongside the 3 for 1 split. Both decisions keep attention on DuPont de Nemours as a cash return story while the business focuses on healthcare, water technologies and diversified industrial customers worldwide.
For a shareholder or potential investor, the key question is whether ongoing dividends remain manageable while earnings quality improves from here. Analysts highlight that the payout is not well covered by current earnings and that one off items have affected results, so execution on productivity, PFAS cash outflows and input cost management will heavily influence how sustainable this dividend profile looks over time.
DuPont de Nemours' current analyst narrative points to revenues of US$7.9b and earnings of US$974.5 million by 2029, based on expected revenue growth of 4.4% per year and an earnings increase of about US$668.5 million from US$306.0 million today.
Uncover why DuPont de Nemours' fair value indicates a 29% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
Some of the lowest ranked analysts frame PFAS cash settlements as the real swing factor for DuPont de Nemours, not the 3 for 1 split or the US$0.60 dividend. They were pencilling in about US$7.8b of revenue and US$995.3 million of earnings by 2029, yet still set a US$145.0 target. That gap shows how far opinions can spread, and it gives you several contrasting forecasts to explore as fresh news lands.
Explore 3 other DuPont de Nemours fair value estimates, including one that suggests it could be worth just $145.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DuPont de Nemours research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DuPont de Nemours. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DuPont de Nemours' overall financial health at a glance.
Looking For More Investment Ideas Beyond DuPont de Nemours?
Once you have a handle on DuPont de Nemours, it can help to set it alongside other opportunities and see how the trade offs look in real time. The Simply Wall St screener lets you compare different types of businesses in a structured way, so you can stress test your thesis rather than rely on a single story.
- If you care most about robust fundamentals and balance sheet strength, start with this curated list of solid balance sheet and fundamentals (25 results) that can help you line up sturdier counterparts to DuPont de Nemours.
- If you prefer to keep risk contained and focus on steadier profiles, filter for companies with more resilient characteristics through a focused 32 resilient stocks with low risk scores that you can benchmark against your current holdings.
- If you enjoy hunting for underfollowed opportunities, widen your watchlist with a hand picked 20 high quality undiscovered gems that may sit off the usual radar but still clear your quality bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com