


The shares of CoreWeave (CRWV) rallied over 6% in premarket trading on Monday after investment banking major Goldman Sachs upgraded the AI cloud infrastructure company to “Buy” from “Neutral.” Gabriela Borges downgraded the price target from $129 to $106 but pointed out that the economics of the contracts of CoreWeave can turn out to be much better than anticipated by the market.
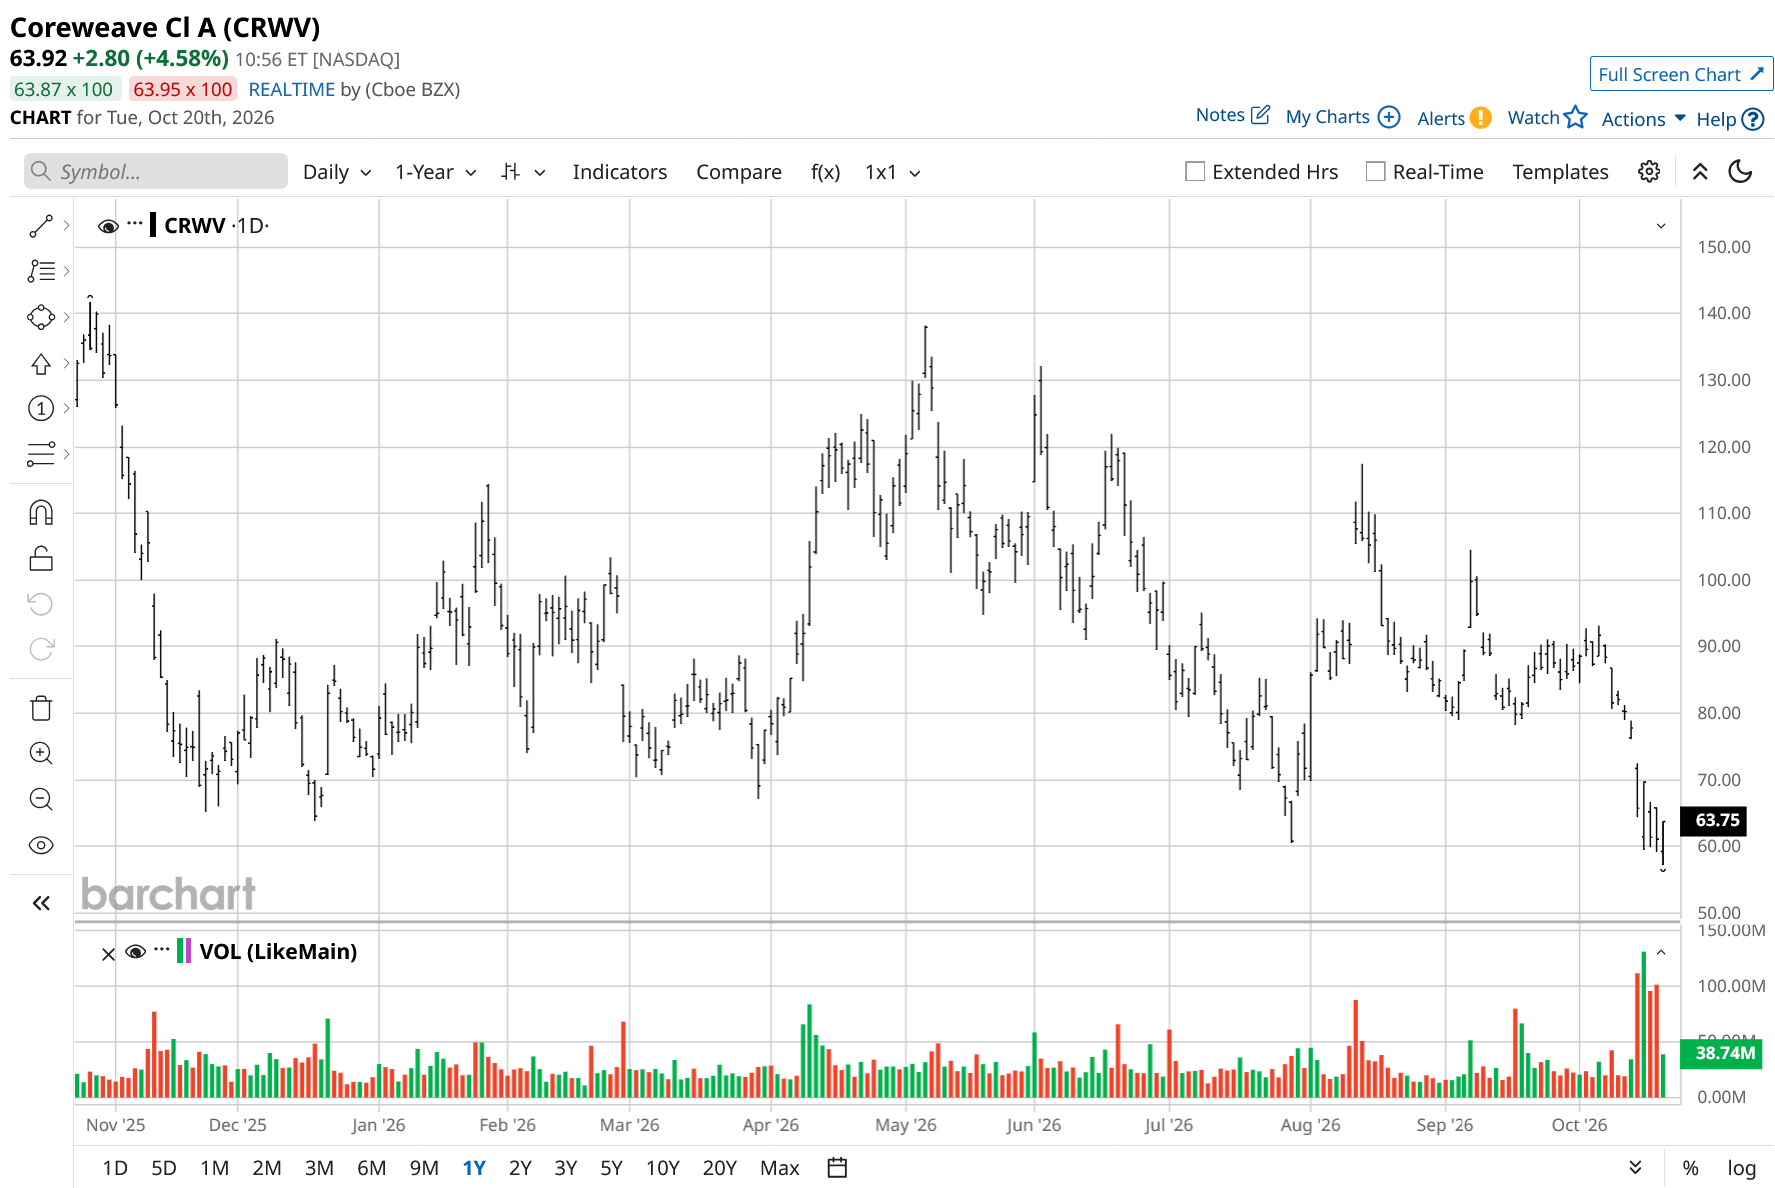
The upgrade has come at a very interesting stage for CRWV. Despite massive demand for AI infrastructure computing capacity, the stock has been under immense pressure recently, losing 21% over the last five trading days, and it notably still closed the day flat. The shares now trade near $64, well below their 52-week high of $141.79, which means more than 55% below the annual peak. This situation makes the upgrade of the analysts from Goldman Sachs very interesting indeed.
About CoreWeave Stock
Based in Livingston, New Jersey, CoreWeave owns a dedicated cloud infrastructure platform for artificial intelligence workloads. The company delivers GPU-accelerated computing infrastructure to the AI labs, enterprises, and other customers needing huge amounts of computing infrastructure. Currently, the market cap of CoreWeave is around $28 billion.
CRWV stock has seen an incredible turnaround from its highs. The shares have traded recently at $61.55, only slightly higher than their 52-week low of $59.51 and 56% lower than their 52-week high. What makes this very intriguing is that the demand for the infrastructure offered by the company is growing very fast right now.
The valuation is one of the most difficult aspects of CoreWeave. The company is not profitable on a GAAP basis, making any sort of price-to-earnings ratio irrelevant. CRWV is trading at a multiple of around 6.2 times sales and 18.6 times cash flows. These are fairly high multiples given the highly leveraged nature of the balance sheet of CoreWeave with a debt/equity ratio of 6.98.
Nevertheless, Goldman Sachs is confident that the market is focusing too much on financing risks while ignoring contract economics of CoreWeave. The investment bank expects rising annual recurring revenue per megawatt and unlevered internal rate of return of CoreWeave in the coming 24 months due to supply scarcity and CoreWeave’s performance/cost advantage.
Fast Revenue Growth but Remains Unprofitable
The numbers from the latest quarter from CoreWeave show how fast the AI infrastructure company is scaling. The revenue came in at $2.58 billion, jumping from $1.21 billion in the year-ago quarter, indicating an increase of 113%. However, the fast growth has not yet led to profitability of CoreWeave. The company posted a net loss of $626 million, or $1.14 per share, against a net loss of $290 million, or $0.60 per share, in the year-ago period.
There was more positive news beyond the headline number. The adjusted EBITDA of the company has more than doubled to $1.51 billion from $753 million while its adjusted EBITDA margin has slightly decreased to 59% from 62%. Meanwhile, CoreWeave ended the June quarter with a backlog of approximately $104 billion in revenues. This backlog does not include more than $25 billion of new customer commitments received in early Q3.
CoreWeave is building fast its capacity as well to meet this demand. The active power grew by almost 500 megawatts to 1.5 gigawatts, while total contracted power grew to around 3.7 GW. In addition, CoreWeave achieved the first bring-up and validation of Nvidia’s Vera Rubin NVL72 platform and developed partnerships with companies such as Databricks, Cognition, and Runway ML.
However, the problem is the cost of financing of this fast growth. The net interest expense of the company rose to $640 million from $267 million in the year-ago period. Goldman Sachs expects the blended cost of debt to increase by 100 to 200 basis points, but the increase is expected to be contained. If the return on contracts grows faster than financing costs, then the economics of CoreWeave could improve despite heavy investments into capacity.
What Do Analysts Expect for CRWV Stock?
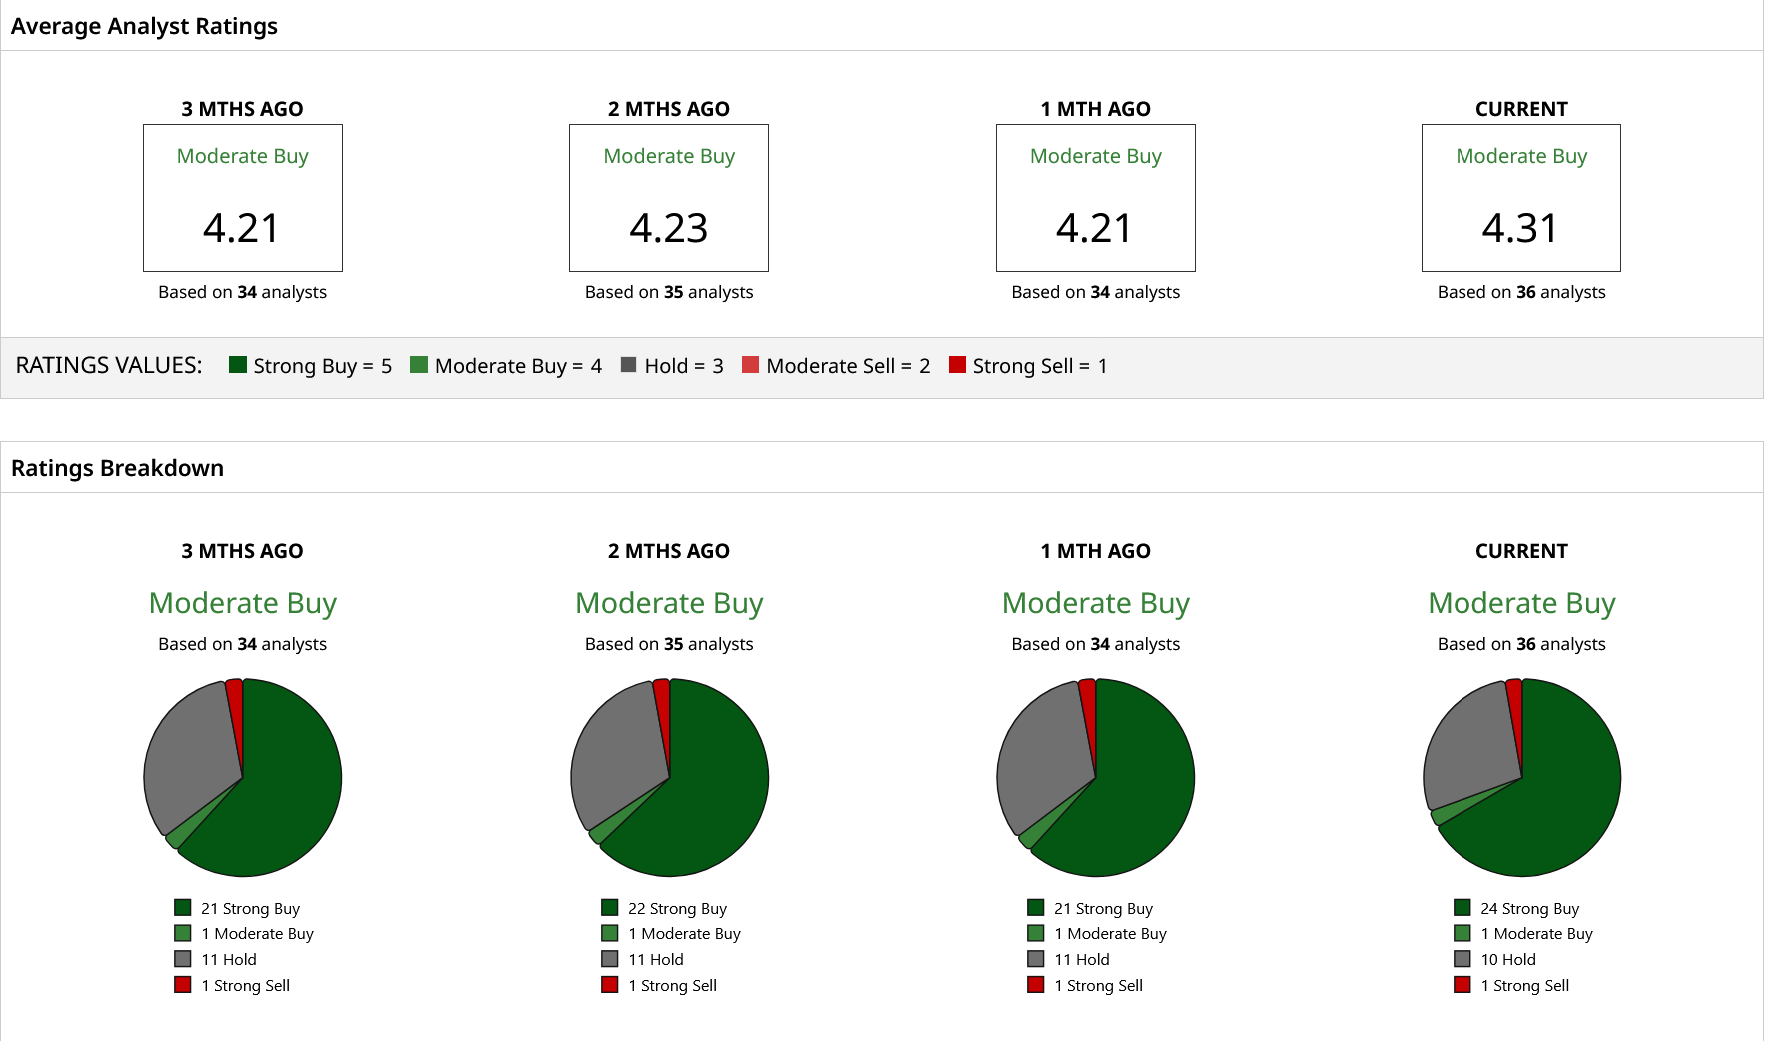
The Wall Street community is very positive toward CRWV stock despite its recent underperformance with a “Moderate Buy” rating consensus. Analysts estimate the average target price at $134.77, with the lowest estimate at $41 and the highest target at $250. In comparison with CRWV’s recent price of $64, the average target suggests a upside potential of around 111%. Even the newly lowered target of $106 from Goldman Sachs indicates an upside potential of about 66%. This upside is justified, but there is also high risk involved. CoreWeave has one of the largest contracted AI infrastructure backlogs in the market and is seeing more than double revenue growth. However, the company is unprofitable and highly leveraged at the same time, and a lot of capital is needed to build AI infrastructure.
On the date of publication, Yiannis Zourmpanos did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.