


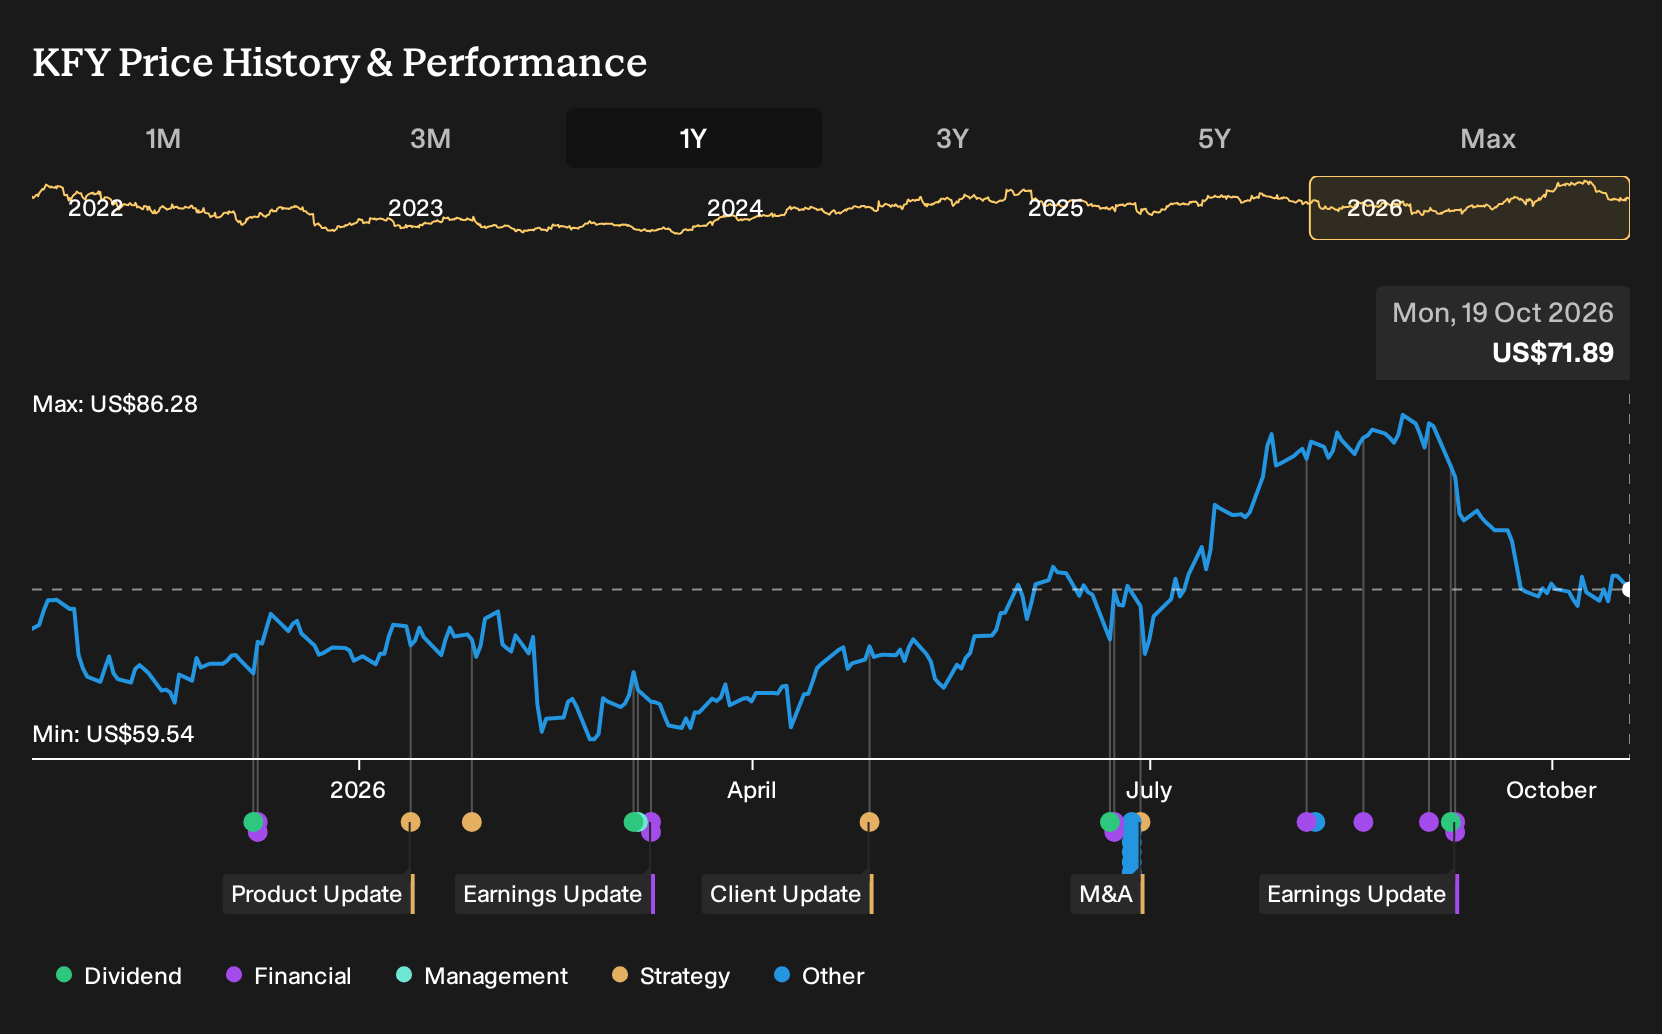
- Korn Ferry is currently paying a quarterly dividend of $0.55 per share with a 3.01% yield, alongside commentary on expected earnings and a history of multiple dividend increases over the past five years.
- AMS, a Korn Ferry company, reports that 81% of employers plan to increase early career hiring as AI reshapes entry level roles, highlighting how clients are rethinking junior talent pipelines and the work Korn Ferry can support around AI centric workforce design.
- We will look at how Korn Ferry’s investment narrative interacts with its competitive dividend profile and AI linked early career hiring trends.
Korn Ferry Investment Narrative Recap
To own Korn Ferry, you need to believe the shift toward recurring workforce solutions and digital HR tools can keep offsetting a choppy consulting cycle. The near term swing factor is how quickly the enlarged backlog, including AMS, turns into fee revenue and cash. The latest dividend news mainly reinforces that management still leans into a cash return story rather than changing that operational focus.
The biggest risk still sits in execution. Integrating AMS, managing more than US$1b of added debt and keeping large workforce projects on schedule all have to line up. Any delays converting signed AMS and RPO work into recognized revenue, especially if consulting demand softens again in EMEA or APAC, would pressure margins and near term earnings.
The AMS survey, showing 81% of employers expect to increase early career hiring as AI reshapes junior roles, is the announcement that most clearly links back to Korn Ferry’s thesis. It speaks directly to where new work could emerge across RPO, early career programs and AI centric workforce design. That sits in the middle of the Workforce Solutions build out.
For you as a shareholder, this matters less as a headline and more as a proof point that clients see early career and AI driven roles as a priority. If Korn Ferry converts that interest into contracted programs, it could help absorb macro softness in traditional search. If projects prove slow to scope or implement, the risk around backlog conversion and AMS integration remains front of mind.
What The Korn Ferry Numbers Assume
Korn Ferry's narrative projects $4.4 billion revenue and $388.9 million earnings by 2029. That aligns with analyst assumptions of 14.6% yearly revenue growth and implies an earnings increase of about $112.7 million from $276.2 million today.
Discover why Korn Ferry's fair value signals a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$62 to about US$183, so retail opinions on Korn Ferry’s worth are already wide even before the latest AI hiring and dividend news. When you then consider macro pressure on consulting demand and AMS integration risk, there are already many reasons to compare several viewpoints yourself.
Explore 2 other Korn Ferry fair value estimates, including one that suggests up to 155% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Korn Ferry research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Korn Ferry. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Korn Ferry's overall financial health at a glance.
Looking For More Ideas Beyond Korn Ferry?
If you want to stress test your Korn Ferry view against other opportunities, the Simply Wall St Screener can help you filter for very different types of businesses in a few clicks. Line up income, balance sheet strength and perceived mispricing side by side so you can see where Korn Ferry fits in your broader watchlist.
- For investors who care most about dependable income, compare Korn Ferry’s yield profile with a wider pool of stocks by scanning a curated set of 8 dividend fortresses.
- If capital preservation sits higher on your list than chasing maximum upside, filter for companies that appear more resilient through our 32 resilient stocks with low risk scores.
- When you want to hunt beyond the usual large caps, broaden your opportunity set by screening for 20 high quality undiscovered gems that share some of the quality traits you might like in Korn Ferry.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com