


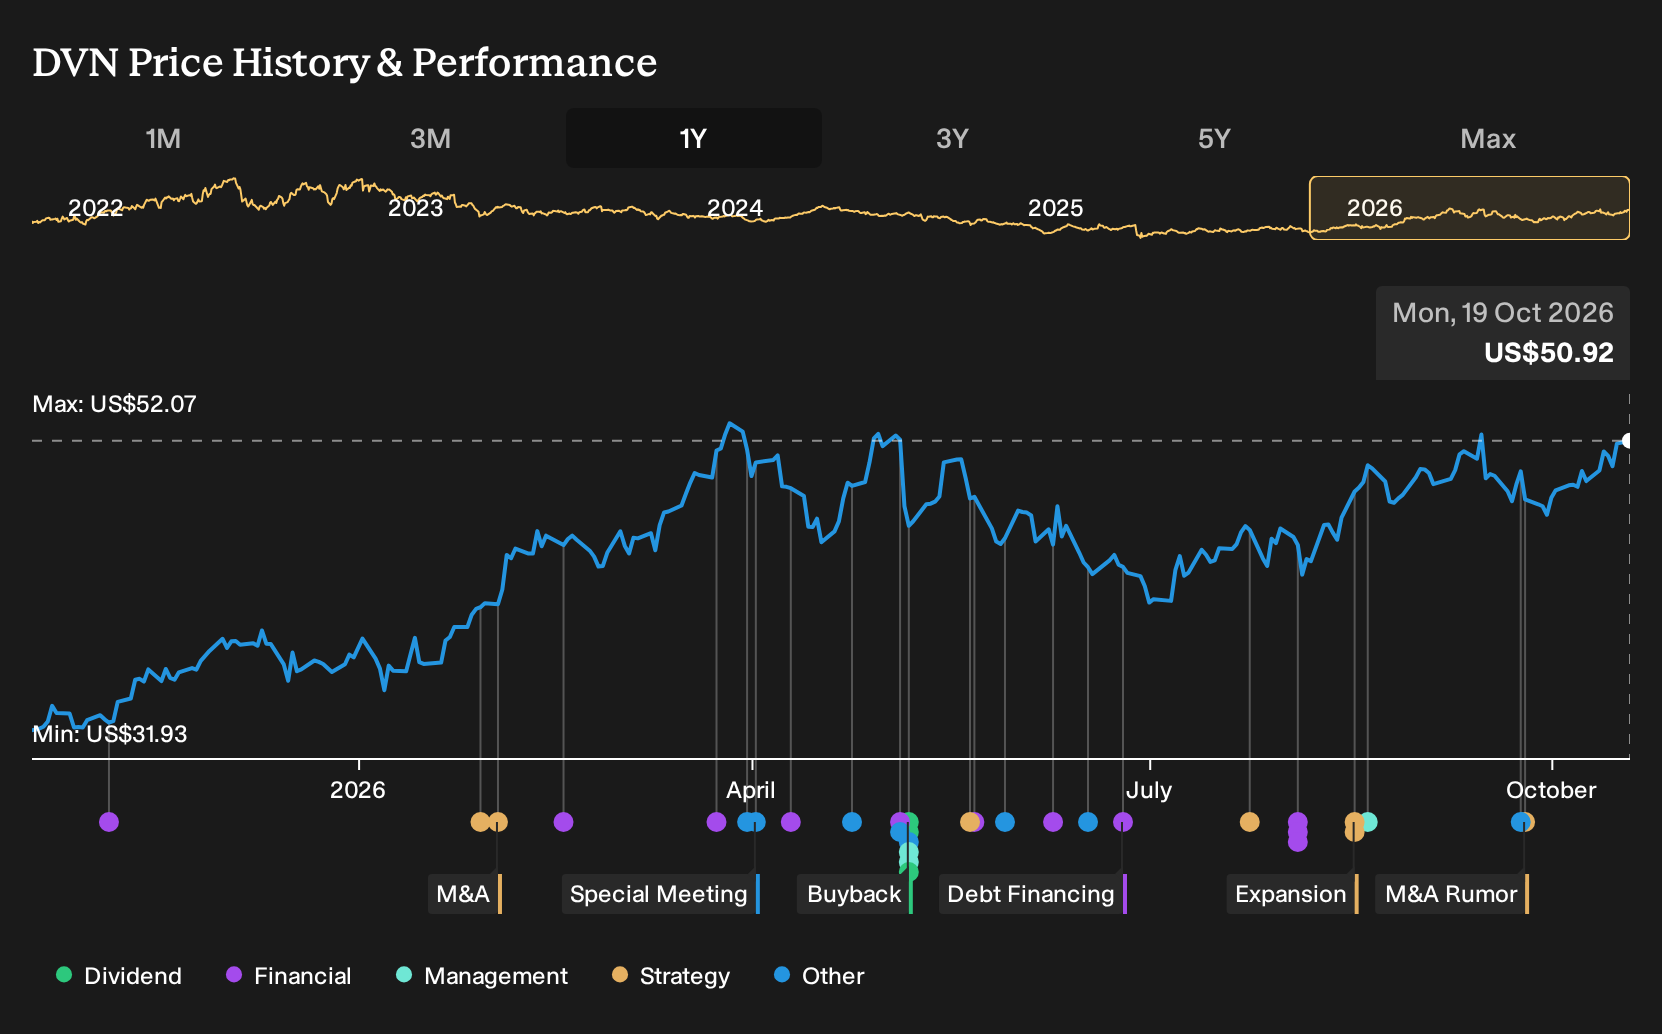
- Devon Energy recently reported a strong quarterly earnings result that exceeded prior expectations, supported by resilient U.S. shale production and disciplined capital spending.
- The earnings beat highlights how Devon Energy’s cost control and operating efficiency efforts are feeding through to profit quality, which in turn is drawing supportive analyst rankings and fresh revisions to earnings estimates.
- Attention now shifts to how Devon Energy’s stronger than expected earnings performance could reshape its investment narrative and perceived cash flow durability.
Scan how Devon Energy’s earnings surprise compares with other U.S. shale producers by jumping into a hand picked list of 35 high quality undervalued stocks.
Devon Energy Investment Narrative Recap
To own Devon Energy, you need to be comfortable with a concentrated U.S. shale portfolio that depends on drilling efficiency, AI driven optimization and careful capital allocation to keep production, costs and free cash flow in balance. The recent earnings beat reinforces that the operating plan is working for now, but it does not remove execution risk.
In the near term, the key swing factor is whether Devon Energy can keep offsetting natural decline rates without meaningfully higher sustaining capital. The biggest risk sits in gas exposure and midstream commitments. Any delays, cost overruns or weaker regional pricing could quickly tighten cash generation even if headline earnings look solid.
The fresh earnings surprise sits alongside a broader effort to use AI tools across more than 1,000 wells, extend those techniques to legacy Coterra assets and pursue at least US$1b of merger synergies by year end 2027. For you as a shareholder, the interesting part is how these programs could influence unit costs rather than just production volumes.
Devon Energy is also leaning on new midstream projects such as Blackcomb and the Solitude Pipeline System, plus firm transportation and hedging that already cover over 70% of Permian gas volumes. The current result gives the company a bit more room to execute on these plans, but the same projects remain a core operational risk if returns or pricing do not line up with expectations.
What The Current Forecasts Assume For Devon Energy
Devon Energy's analyst narrative points to revenues of US$25.4b and earnings of US$5.3b by 2029, based on a projected 10.6% yearly revenue growth rate and an earnings step up of about US$2.0b from US$3.3b today.
Uncover why Devon Energy's fair value indicates a 19% potential upside to its current price before that gap closes.
Exploring Other Perspectives
One alternate angle focuses on regulation risk rather than shale execution. The most cautious analysts were working off about US$22.6b of 2029 revenue and US$5.5b of earnings, and saw Devon Energy as roughly fairly priced. That is a more muted story than consensus, and the latest earnings surprise could push those views to shift.
Explore 6 other Devon Energy fair value estimates, including one that suggests it could be worth just $49.62.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Devon Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Devon Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Devon Energy's overall financial health at a glance.
Looking for more investment ideas beyond Devon Energy?
Once you have a view on Devon Energy, it can help to widen the field and compare it with other companies that match your preferred balance of quality, risk and income potential.
- If you want potential upside without abandoning financial discipline, scan a curated group of high quality opportunities through the 20 high quality undiscovered gems.
- For investors who care most about resilience and balance sheet strength, filter for companies with sturdier finances using the list of solid balance sheet and fundamentals (25 results).
- If dependable income is higher on your list, focus on businesses with stronger cash distribution profiles by reviewing the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com