


Marvell Technology, which trades on the Nasdaq under ticker MRVL and last closed at US$237.09, has delivered a very strong run over the past few years, so the live question now is whether that price can be squared with what its earnings support today. After such a move, valuation starts to hinge less on headlines and more on what the profit stream can reasonably justify.
- Over the past 3 years the stock has returned about 3.9x, which puts a lot of weight on whether the current earnings profile can support such a step up in market value.
- Recent product launches in high speed connectivity and memory expansion for AI data centers, along with higher long term revenue ambitions shared by Marvell, can feed into higher earnings expectations and influence how investors weigh today’s P/E and related multiples.
- Your read on Marvell Technology is one view; the desks covering it have another. See what analysts think Marvell Technology's shares could be worth.
The issue now is whether Marvell Technology's current share price is justified by its earnings when judged against the Fair Ratio benchmark.
To analyze the same earnings question you are asking about Marvell Technology across a broader group of AI infrastructure companies, review the data in 55 AI infrastructure stocks.
Has Marvell Technology Run Too Far on Earnings?
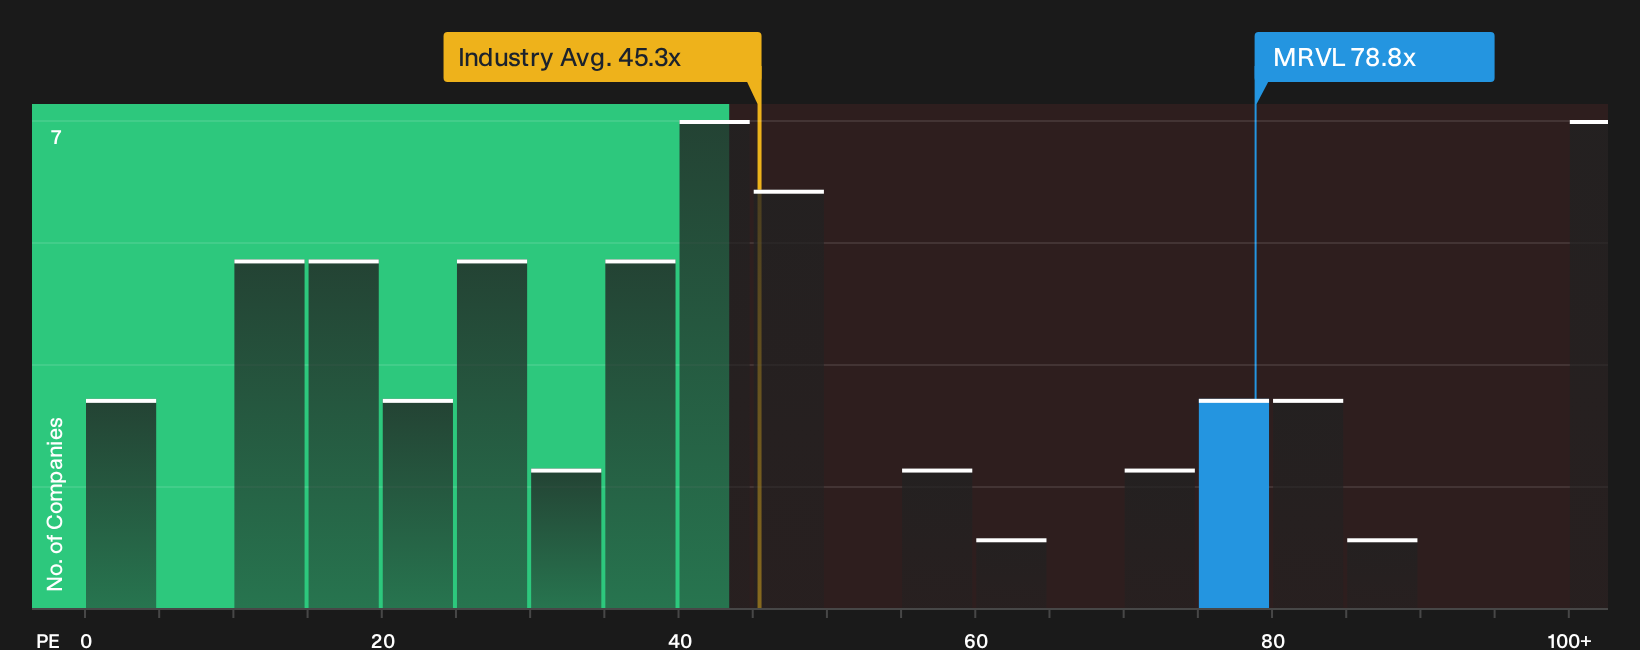
P/E fits Marvell Technology because earnings already matter to how investors frame its AI data center story. On this metric, the stock trades on a P/E of 78.8x, compared with a semiconductor sector average of 45.3x and a peer group near 46.2x, so you are paying a clear premium for each dollar of profit today.
Because Marvell screens above the Fair Ratio benchmark that blends its growth plans, margins, scale and risks into a tailored yardstick, the multiple currently prices the shares as overvalued on this framework rather than merely punchy. Despite management lifting long term revenue and EPS targets at its recent investor day, the gap between the live P/E and this Fair Ratio suggests expectations embedded in the stock already stretch well beyond what broad sector valuations imply. Explore the numbers behind Marvell Technology's P/E valuation.
The Marvell Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Marvell Technology sit between this valuation puzzle and the assumptions that would need to play out on growth, margins and earnings for the stock to be worth materially more or less than today’s price, and they live on the Community page. Rather than relying on a single multiple or model, each narrative lays out its own underlying drivers so you can compare those expectations with future results.
Community views on Marvell Technology are now split between a bullish AI build out story and a more cautious take on how much is already priced in.
Bull case: 30% undervalued
"The expanded commercial agreement with a major hyperscaler, which includes a warrant tied to up to US$120b of cumulative revenue over 6.5 years for TPU attached custom silicon…"
Discover why this Narrative puts Marvell Technology at 30% undervalued.
Bear case: 69% overvalued
"At approximately $134, the stock is priced for FY2028 execution. The investment thesis requires believing Marvell can deliver approximately $15B in FY2028 revenue…"
Explore why this Narrative puts Marvell Technology at 69% overvalued.
One more piece to weigh on Marvell Technology before you make a move
There is a separate lens you can use to cross check Marvell Technology against today’s share price, which is where professional coverage sees profits and revenue a few years from now. Explore where analysts expect Marvell Technology to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com