


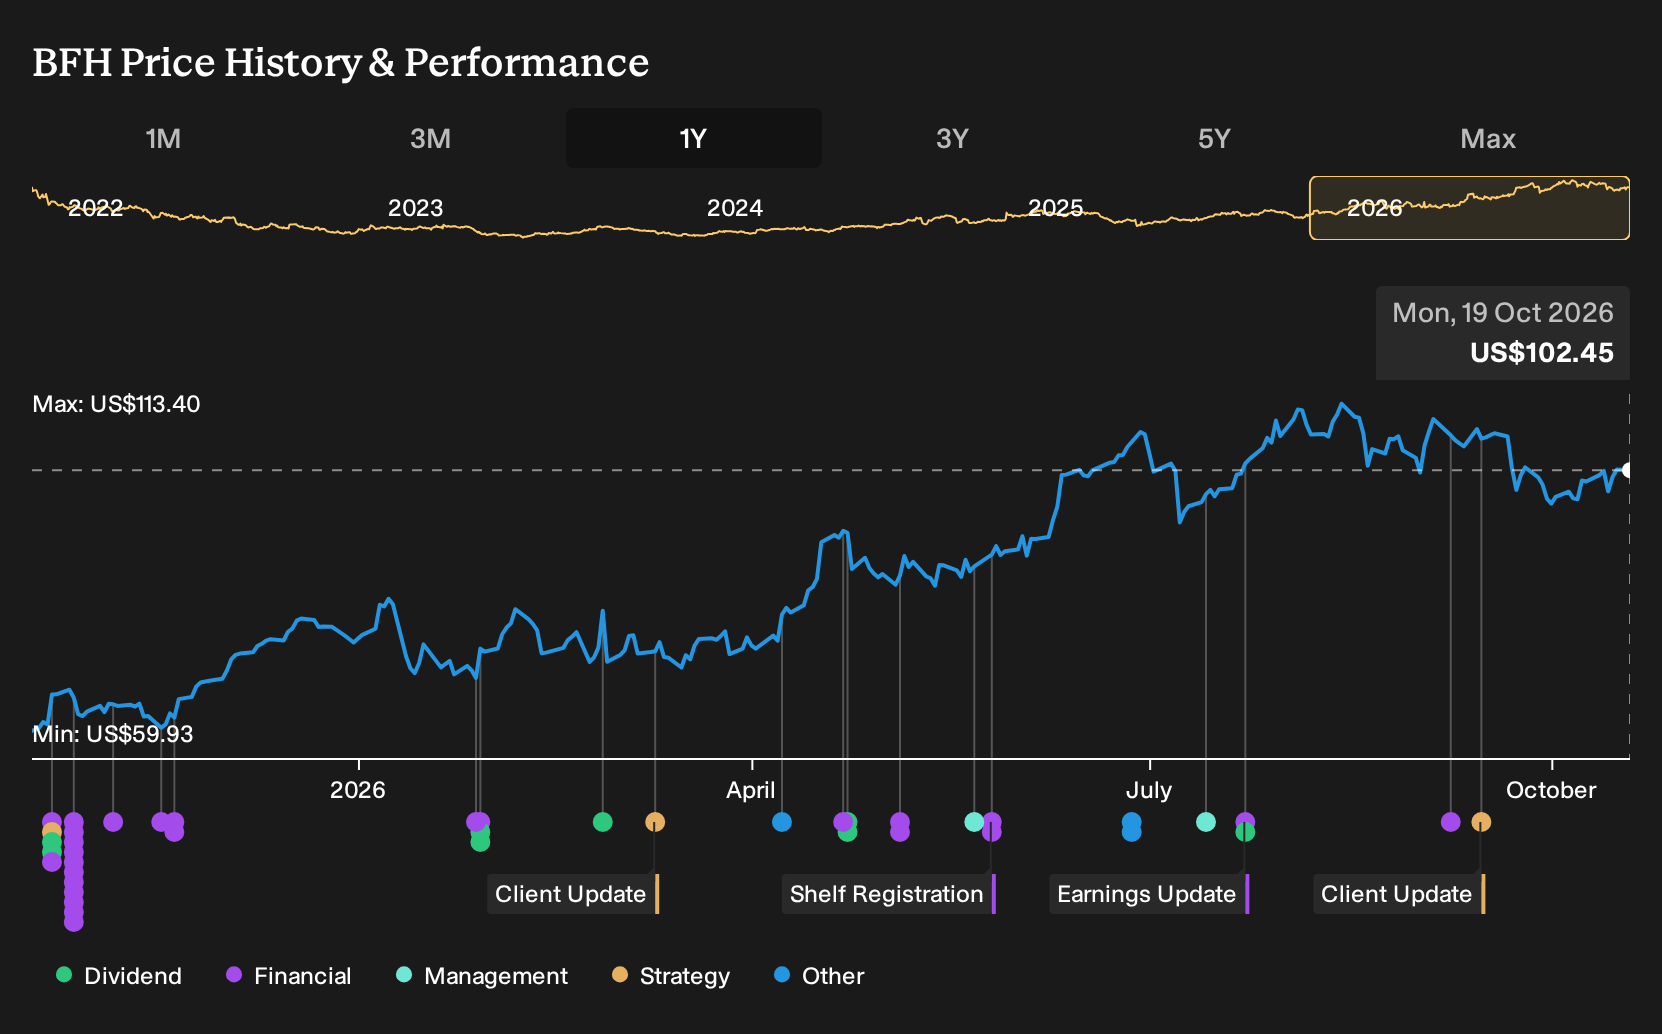
- Bread Financial Holdings is set to report September-quarter results with consensus EPS at $3.26, while recent years have brought flat sales and annual EPS pressure despite revenue growth.
- The combination of upward EPS revisions and an Earnings ESP of +1.20% against a track record of beating forecasts puts execution discipline and profitability under the microscope.
- We will look at how Bread Financial Holdings' investment narrative lines up with the upgraded EPS outlook ahead of the coming earnings release.
Bread Financial Holdings Investment Narrative Recap
Owning Bread Financial Holdings means believing the business can keep improving credit quality and efficiency while living with slower top line progress. In the near term, the story hinges on disciplined underwriting, the mix shift toward higher income customers and keeping loss rates around targets as inflation and fuel costs pressure lower income cardholders.
The upcoming September quarter earnings, with EPS expected at $3.26 and down year on year, puts that belief to the test but does not radically change it. The biggest swing factor remains credit performance and partner profit sharing, especially the roughly US$30 million step up in retailer payments in Q3 2026.
The most relevant piece of recent information for this setup is the combination of a 10.7% upward revision in the September quarter EPS estimate and Bread Financial Holdings' history of beating forecasts in the last four quarters. That pattern focuses attention squarely on whether recent efficiency gains and loan mix decisions are sticking.
If execution again lands ahead of expectations, the catalyst is straightforward. Confidence can build that technology investment, embedded financing partnerships and direct to consumer deposits are offsetting headwinds from higher partner sharing and elevated bad loans around 4.7%. If results slip, investors may refocus on forecast earnings declines over the next three years and the risk that credit costs absorb more of those gains.
Bread Financial Holdings' current analyst narrative points to US$4.4b in revenue and US$519.1 million in earnings by 2029, based on an assumed 18.0% yearly increase in revenue. This represents an earnings decline of about US$45.9 million from the US$565.0 million earned today.
Uncover why Bread Financial Holdings' fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Bread Financial Holdings leans heavily on capital returns as the key catalyst. The most optimistic analysts were modelling revenue of US$4.8b and earnings of US$593.3 million by 2029, compared with the bearish US$390.1 million. Those forecasts came before this earnings news, and opinions may shift as fresh information lands.
Explore another Bread Financial Holdings fair value estimate, including one that suggests up to 110% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Bread Financial Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bread Financial Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bread Financial Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Bread Financial Holdings?
Once you have a view on Bread Financial Holdings, it can help to compare that thesis with other opportunities that line up with your risk tolerance, time horizon and income needs using the Simply Wall St Screener.
- If capital preservation comes first, filter for companies that score well on financial strength and see the full list of solid balance sheet and fundamentals (25 results) that may handle shocks more comfortably.
- If income is the priority, scan for reliable payers and review a curated group of 8 dividend fortresses that could support a more yield focused approach.
- If you want ideas that the broader market might not be watching closely, start with a focused collection of 20 high quality undiscovered gems that pair quality fundamentals with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com