


Meta Platforms (META) shares are inching lower ahead of the giant’s fiscal Q3 earnings scheduled to be released after the market closes on Oct. 21. Consensus is for META to record $5.86 in earnings per share (EPS) for its third financial quarter, which would represent about a 19.17% decline on a year-over-year basis.
Despite recent declines, Meta stock sits comfortably in the green for the year, currently up about 5% versus the start of 2026.
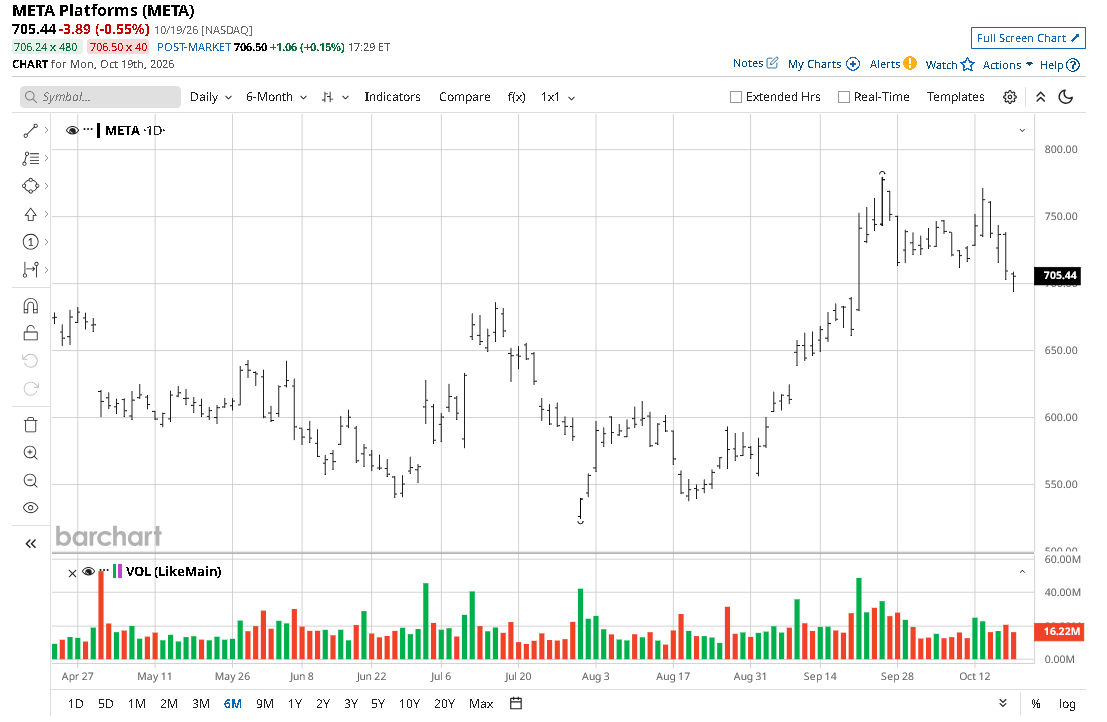
Options Sentiment Remains Bullish for META Stock
Despite the expected YOY decline in Q3 results, the derivatives market believes META shares will push higher after the earnings event.
According to Barchart, the put-to-call ratio on contracts expiring Oct. 23 sits at 0.41x currently, signaling a bullish skew (a reading below 1.00x is typically characterized as in favor of the bulls).
Data also pegs the upper price on those options contracts at about $747 as of this writing, indicating potential for a more than 6% near-term rally on the back of the quarterly print.
Meta Platforms has a history of gaining about 4.34% in November, a seasonal trend that makes it even more attractive ahead of the Q3 release.
What Might Pressure META’s Earnings in Q3?
META’s aggressive investment in artificial intelligence (AI) could explain the anticipated pressure on earnings.
Higher depreciation on servers, data-center operating costs, and third-party cloud spending can absorb more revenue before it reaches the bottom line.
The company expects total expenses of $165 billion to $169 billion in 2026, underscoring the scale of its investment push. Its previous quarter illustrated that squeeze: revenue rose 28%, but expenses climbed 55%, pulling operating margins down to 31% from 43%.
This means that advertising growth alone may struggle to offset the spending surge, potentially leaving quarterly earnings lower even as Meta’s business continues to expand.
What’s the Consensus Rating on Meta Platforms?
Wall Street firms, nonetheless, recommend long-term investors look beyond AI capex concerns and near-term earnings noise.
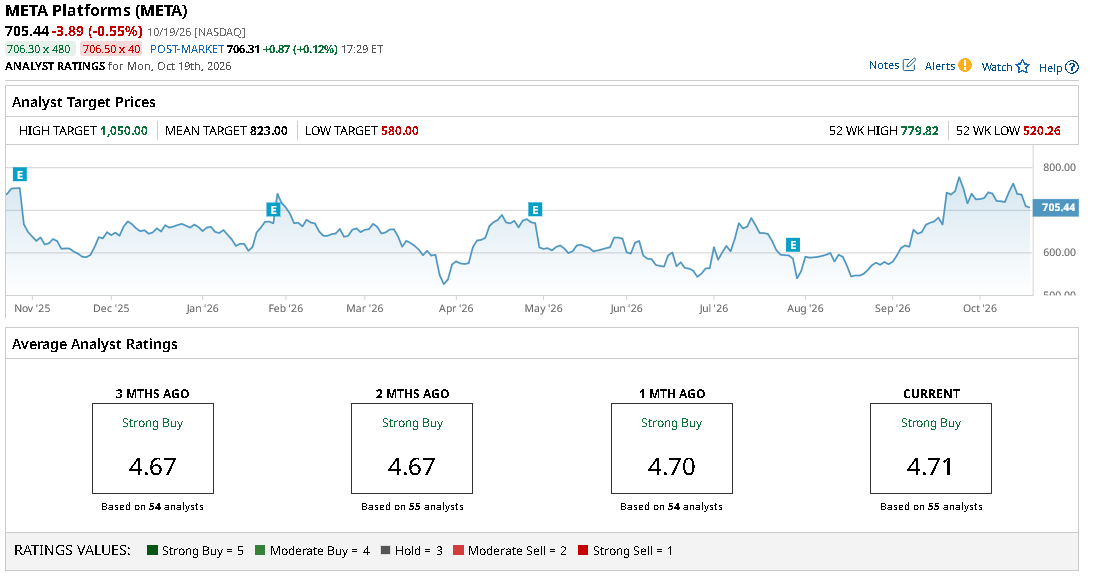
The consensus rating on META shares currently sits at “Strong Buy,” with the mean price target of about $823 indicating potential upside of about 18% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.