


Tesla (TSLA) shares have already staged a meaningful comeback in recent months, but the options market indicates a further extension is possible after the company’s earnings on Oct. 21. Consensus is for the electric vehicle (EV) maker to record $0.22 a share of earnings (EPS) for its fiscal third quarter, which would actually represent a 40.54% decline on a year-over-year basis.
Heading into the quarterly print, Tesla stock trades more than 25% above its year-to-date low from late July.
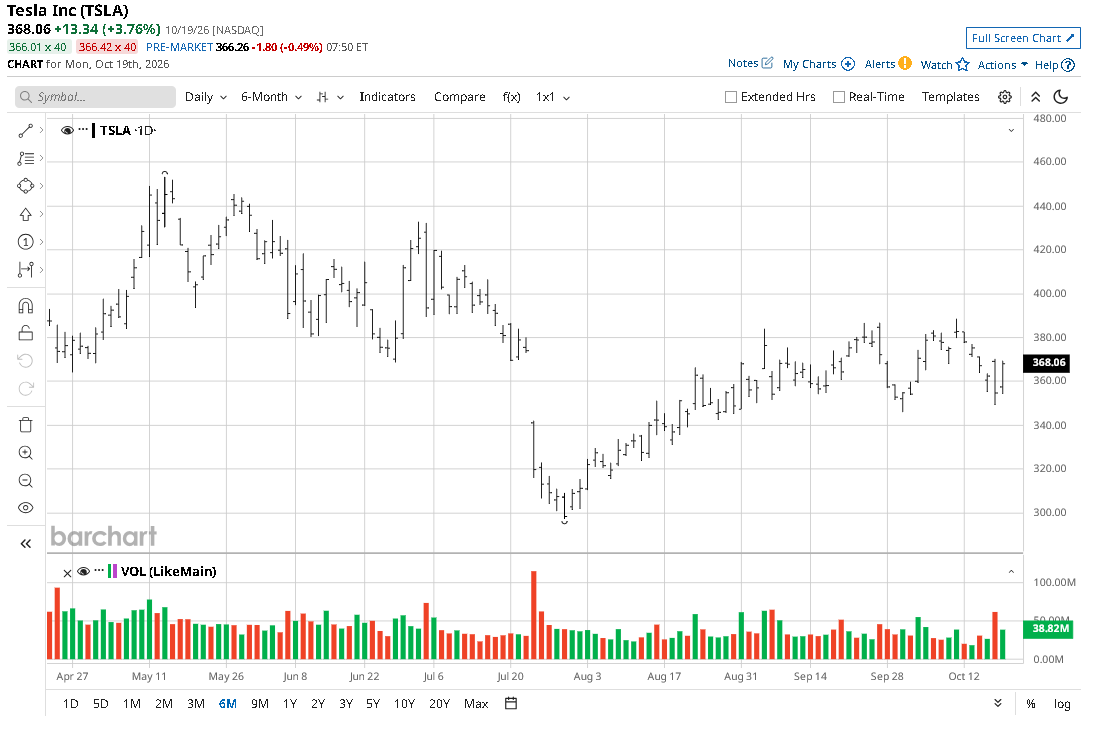
Where Options Data Suggests Tesla Stock Is Headed
The expected earnings decline isn't deterring options traders, who are increasingly betting on a post-earnings surge in TSLA shares.
According to Barchart data, the put-to-call ratio on contracts expiring Oct. 23 sits at 0.73x as of this writing, indicating a fairly strong bearish skew. In the derivatives market, a reading below 1.00x is typically treated as bearish.
Data also pegs the upper price on those option contracts at about $388 currently, signaling potential for another 5.45% rally through the end of this week.
Plus, the EV maker has a history of gaining over 10% on average in November, a seasonal pattern that further lifts its near-term appeal.
Why Are Options Traders Bullish on TSLA Shares
Options traders remain bullish despite the near-term earnings noise because Tesla shares’ bull case now rests primarily on what management says about its next growth phase.
While the company’s recent launch of Roadster has brought the core EV business back in focus, its outlook for robotaxis and autonomous driving remains central to the broader growth story, where tangible progress could strengthen expectations for future revenue.
A plausible explanation for the call-heavy positioning is that traders expect reassuring guidance on that front to outweigh weaker historical results.
That said, Barchart itself holds a “72% SELL” opinion on TSLA, indicating technical momentum is not in its favor, at least for the near term.
How Wall Street Recommends Playing Tesla
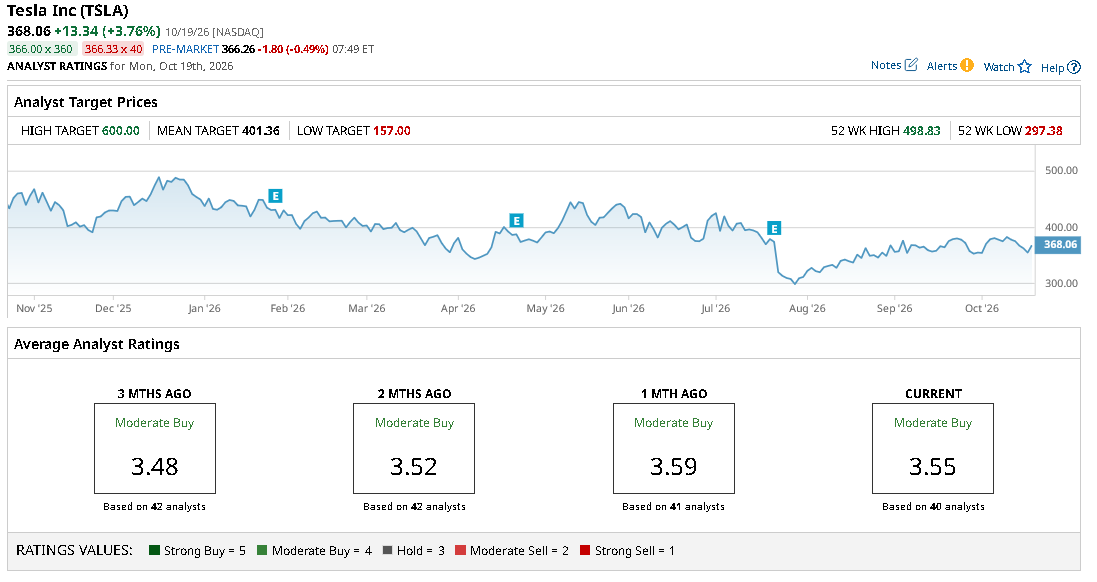
Wall Street analysts agree with the options market sentiment, recommending buying TSLA stock heading into 2027.
The consensus rating on Tesla sits at “Moderate Buy” currently, with the mean price objective of about $401 indicating potential upside of about 10% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.