


- Kratos Defense & Security Solutions recently broke ground on new Helios and AN/SPY-1 facilities in Indiana, advanced its turbojet engine testing, expanded OpenSpace 5G satellite connectivity, and recorded a key U740 Valkyrie flight milestone with Airbus in Europe.
- These moves deepen Kratos Defense & Security Solutions’ role in radar sustainment, hypersonic and directed energy testing, and high volume propulsion, which could influence how its capacity investments convert into longer term programs and production scale.
- We will now look at how Kratos’ Indiana radar and hypersonic test build out might influence the broader investment narrative around the business.
Scan how Kratos Defense & Security Solutions fits into the broader defense and aerospace theme by comparing it against a curated set of list of solid balance sheet and fundamentals (25 results)
Kratos Defense & Security Solutions Investment Narrative Recap
Owning Kratos Defense & Security Solutions stock largely means believing its heavy spend on hypersonics, propulsion, unmanned systems and software defined space will turn into durable production programs rather than just project work. The Indiana radar and HELIOS build out points to deeper involvement in radars and hypersonic material testing, but on its own does not change that broader thesis.
The more immediate swing factor remains execution on high growth while working capital and capex stay elevated, and while FX and fixed price contract pressure weigh on margins. The biggest risk is that these investments take longer than expected to translate into stronger free cash flow and higher profitability.
The Indiana HELIOS facility is closely tied to Kratos Defense & Security Solutions’ hypersonic ambitions, but the recent turbojet progress around the TDI J85 and Spartan engines may be more directly linked to near term catalysts. Those engines sit at the center of the high volume propulsion story that analysts focus on for future scale and margin relief.
Successful J85 testing across multiple launch concepts shows the propulsion franchise moving from design into broader operational validation, which matters as Kratos commits capital to capacity and long lead parts. If engine programs ramp smoothly, they can help offset FX and contract headwinds. If they stumble or orders lag, cash strain and low return on equity concerns stay front and center.
Kratos Defense & Security Solutions is modeled to reach revenues of US$2.9b and earnings of US$180.6m by 2029, which aligns with analyst assumptions of 24.5% yearly revenue growth and an earnings increase of about US$149.7m from US$30.9m today.
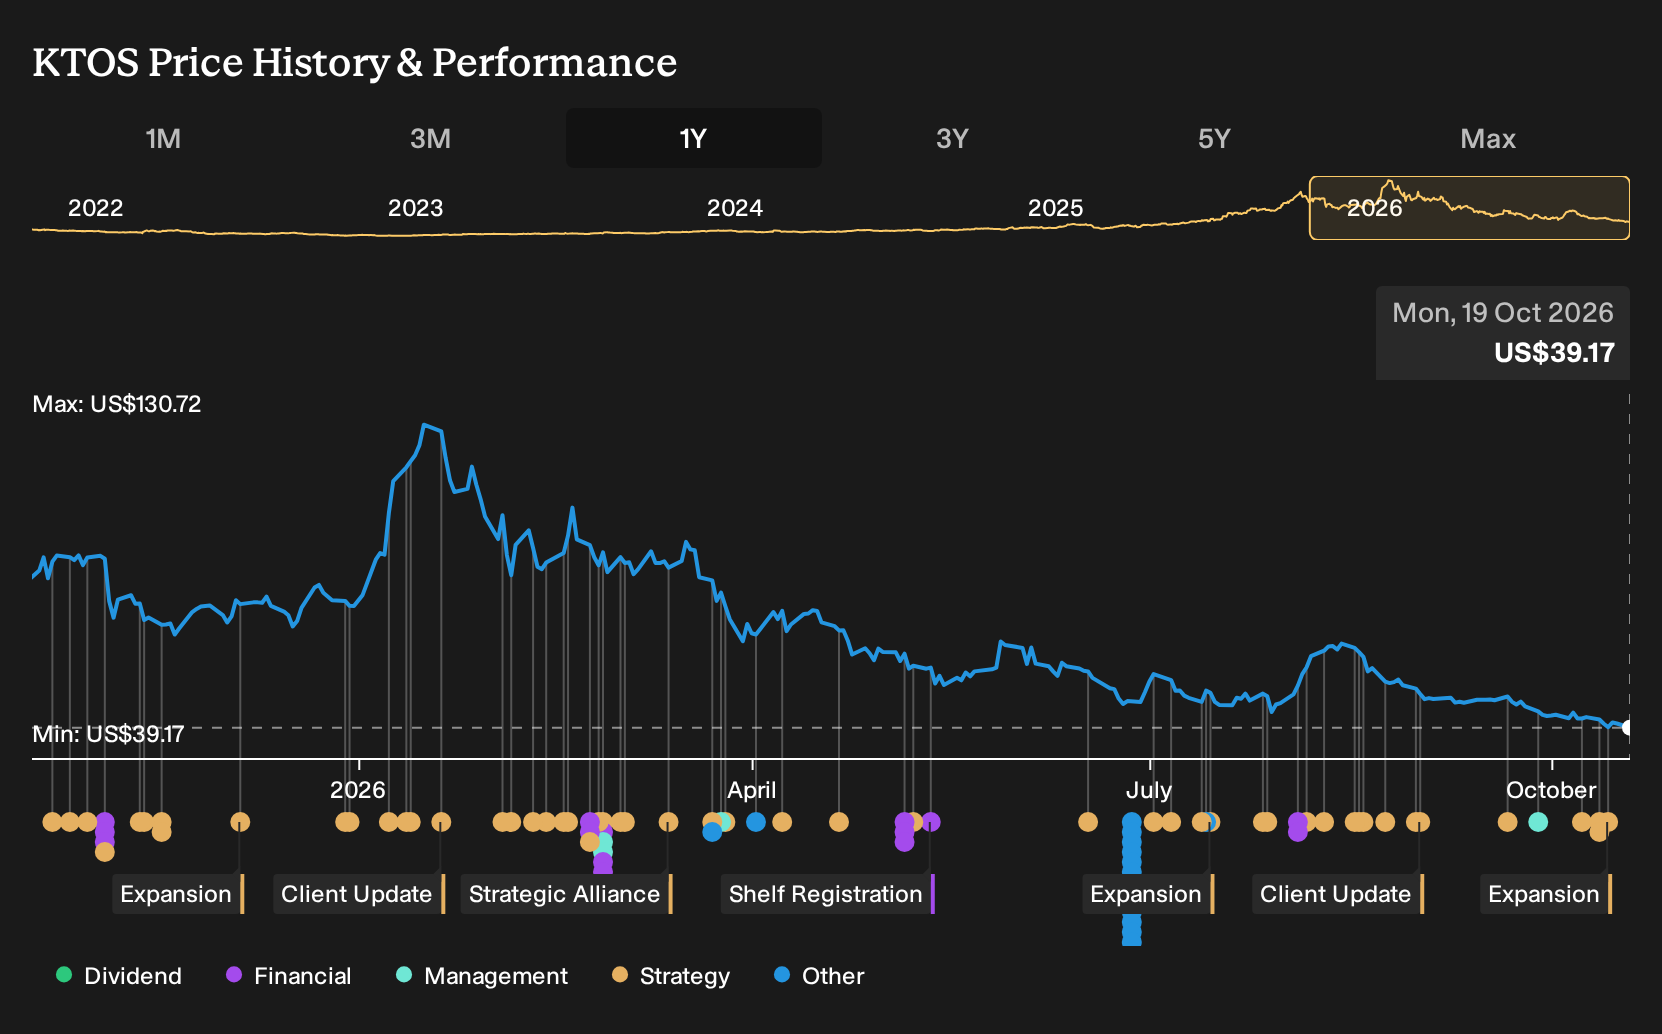
Uncover how Kratos Defense & Security Solutions' fair value indicates a 154% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Some bearish analysts focus less on hypersonics and more on cash strain. Before this news, the lowest forecasts pointed to 20.6% yearly revenue growth and earnings of about US$118.3m by 2029, well below the US$180.6m consensus. That gap shows how far opinions on Kratos Defense & Security Solutions can stretch and why fresh data like the Indiana build out could shift expectations.
Explore 5 other Kratos Defense & Security Solutions fair value estimates, including one that suggests it could be worth just $44.40.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Kratos Defense & Security Solutions research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kratos Defense & Security Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Kratos Defense & Security Solutions' overall financial position at a glance.
Looking for more investment ideas beyond Kratos Defense & Security Solutions?
If you want to stress test your thesis on Kratos Defense & Security Solutions and keep a broader watch on opportunities, it helps to scan a wider group of businesses that match different risk and income profiles.
- If capital preservation and smoother ride potential matter most to you, start by checking companies screened as 32 resilient stocks with low risk scores that may better align with a cautious approach.
- For investors who care about quality at a sensible entry point, compare Kratos against a 35 high quality undervalued stocks that filters for fundamentals as well as pricing.
- If you prefer backing resilient balance sheets over headline stories, review a list of solid balance sheet and fundamentals (25 results) to spot firms where debt levels and liquidity are a central strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com