


Exponent (EXPO) drew fresh attention after Zacks assigned the stock a Rank #2 rating, highlighting recent outperformance compared with a weaker Business Services sector and an increased full year earnings consensus.
Recent trading has leaned positive, with a 19.11% 90 day share price return and a 5.78% 30 day share price return lifting Exponent to US$72.25. However, a 6.51% 1 year total shareholder return contrasts with weaker 3 and 5 year total shareholder returns, suggesting that momentum has picked up only in the shorter term as investors reassess its earnings outlook and risk profile.
Scan how Exponent's recent momentum compares with peers by reviewing our curated list of 35 high quality undervalued stocks that combine earnings strength with disciplined balance sheets.
Recent gains hint either at stronger conviction in Exponent's consulting engine or a short burst of enthusiasm around upgraded earnings expectations. To test which story fits, the valuation picture is the next place to look.
Most Popular Narrative: 14% Undervalued
Exponent’s most followed narrative sets a fair value of $84, which sits above the recent $72.25 close, so the gap between price and implied worth is front and center for investors.
The capital light consulting model, with 2026 capex guided to only US$12 million to US$14 million and management expecting over US$100 million of free cash flow in the second half of 2026 after already returning US$272 million to shareholders over the prior 12 months, gives Exponent scope to continue dividends and buybacks while still funding growth initiatives. This can influence per share earnings and support net margin resilience.
See why 6 investors see Exponent as 14% undervalued.
Result: Fair Value of $84 (UNDERVALUED)
Still, if operating costs stay elevated or AI tools start replacing some higher value consulting work, the Exponent narrative could look very different.
Find out about the key risks to this Exponent narrative.
Another View: What Exponent’s P/E Is Telling You
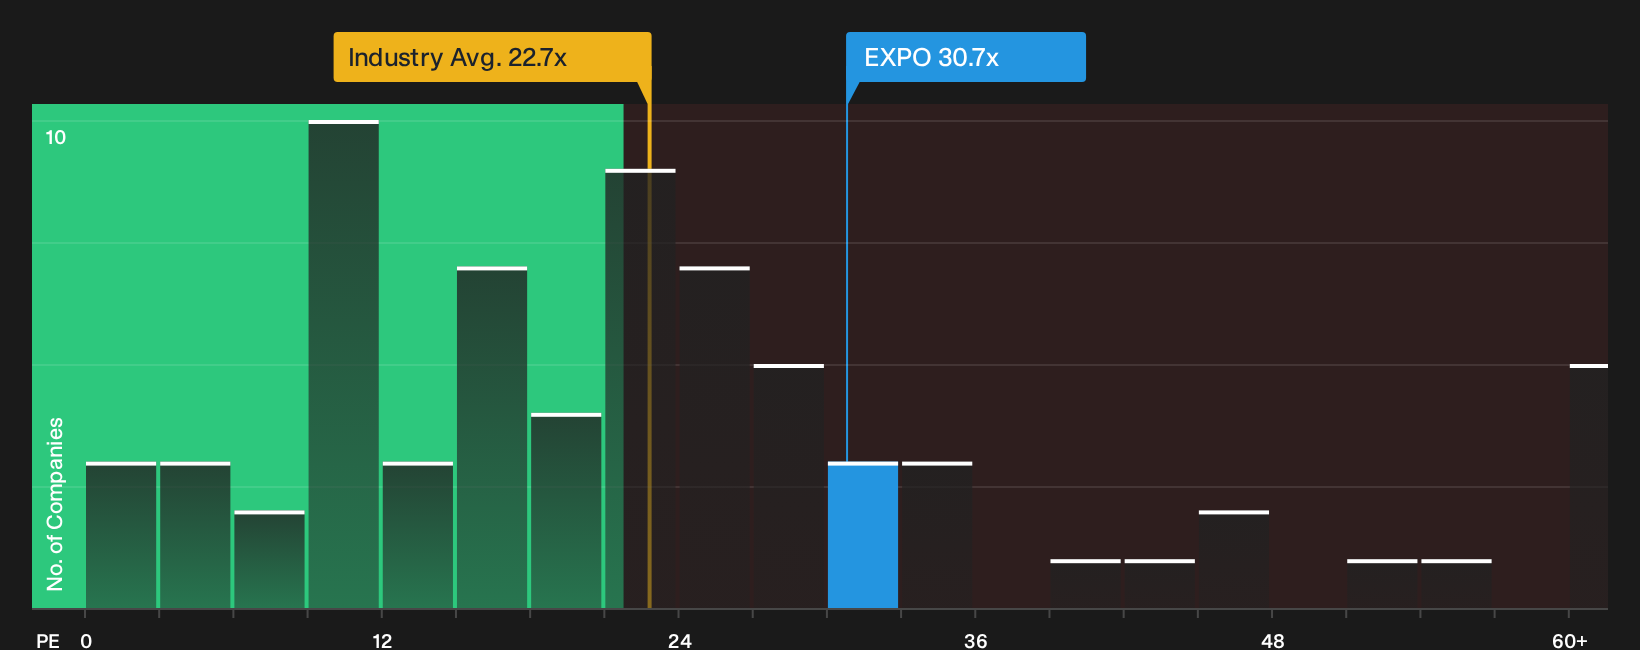
The 14% gap between Exponent’s share price and the US$84 fair value rests on optimistic earnings assumptions. On simple P/E math, the picture looks very different. EXPO trades on 30.7x earnings compared with 22.7x for the US Professional Services industry and a fair ratio of 16.7x, so investors are already paying a premium. The key question is whether this premium represents a safety margin or a risk if expectations change.
Before relying heavily on either the multiples-based signal or the narrative-driven fair value estimate, it helps to look at what the numbers imply for valuation risk in more detail. You can then decide whether that premium aligns with your own expectations for Exponent’s earnings power. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Exponent story so far feels mixed on value, that is the point. You are meant to pressure test it yourself. Start by weighing the optimistic signals that others are focused on, and then decide how much they matter for your own thesis with the 4 key rewards.
Looking for more Exponent and market-wide ideas?
If Exponent has sharpened your focus on quality and price, do not stop here. Broader idea hunting with targeted screeners can surface opportunities you would otherwise miss.
- Target resilient cash generators by reviewing a list of solid balance sheet and fundamentals (25 results) that can support operations through different business conditions.
- Hunt for mispriced quality and see which companies currently appear attractively valued through a 35 high quality undervalued stocks.
- Stack potential portfolio income by scanning a 8 dividend fortresses that screens for yields of 5% or more.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com