


BRP (TSX:DOO) has drawn investor attention after a recent share price pullback, with the stock closing at CA$77.01. The move comes as the powersports and marine manufacturer reports annual revenue of CA$9.34b and net income of CA$115.0m.
Recent trading tells a cautious story for BRP. The 7 day share price return has inched up 1.87%, yet the 30 day move is down 5.32% and the year to date share price return has declined 21.83%. Meanwhile, the 1 year total shareholder return is down 16.32%, pointing to fading momentum as investors reassess both growth prospects and risk.
Scan how BRP stacks up against other pullback candidates with solid fundamentals using our curated 5 high quality undervalued stocks.
After a CA$77 share price and a year where returns have retreated, the puzzle is simple: Is most of BRP’s rerating already behind it, or does the valuation still point to meaningful upside left on the table?
Most Popular Narrative: 24.6% Undervalued
Against a last close of CA$77.01, the most followed BRP narrative points to a fair value of about CA$102.19, implying the recent pullback may already overshoot what the underlying business case suggests.
The rapid expansion of BRP's electric vehicle lineup, including products such as the Outlander electric ATV and electric motorcycle, continues to frame an opportunity for incremental revenue and margin improvement as this portfolio is built out. This may support topline growth and earnings over time. Ongoing international growth focus, with management aiming for roughly US$2.5b of international revenue and continuing to add dealers outside North America, keeps open a path for BRP to increase geographic diversification and support revenue growth and earnings resilience.
See why 22 investors see BRP as 25% undervalued.
Result: Fair Value of CA$102.19 (UNDERVALUED)
Still, this BRP narrative leans heavily on tariff relief and manageable input costs. As a result, prolonged trade penalties or persistent cost inflation could quickly challenge that view.
Find out about the key risks to this BRP narrative.
Another View: What BRP’s P/E Is Telling You
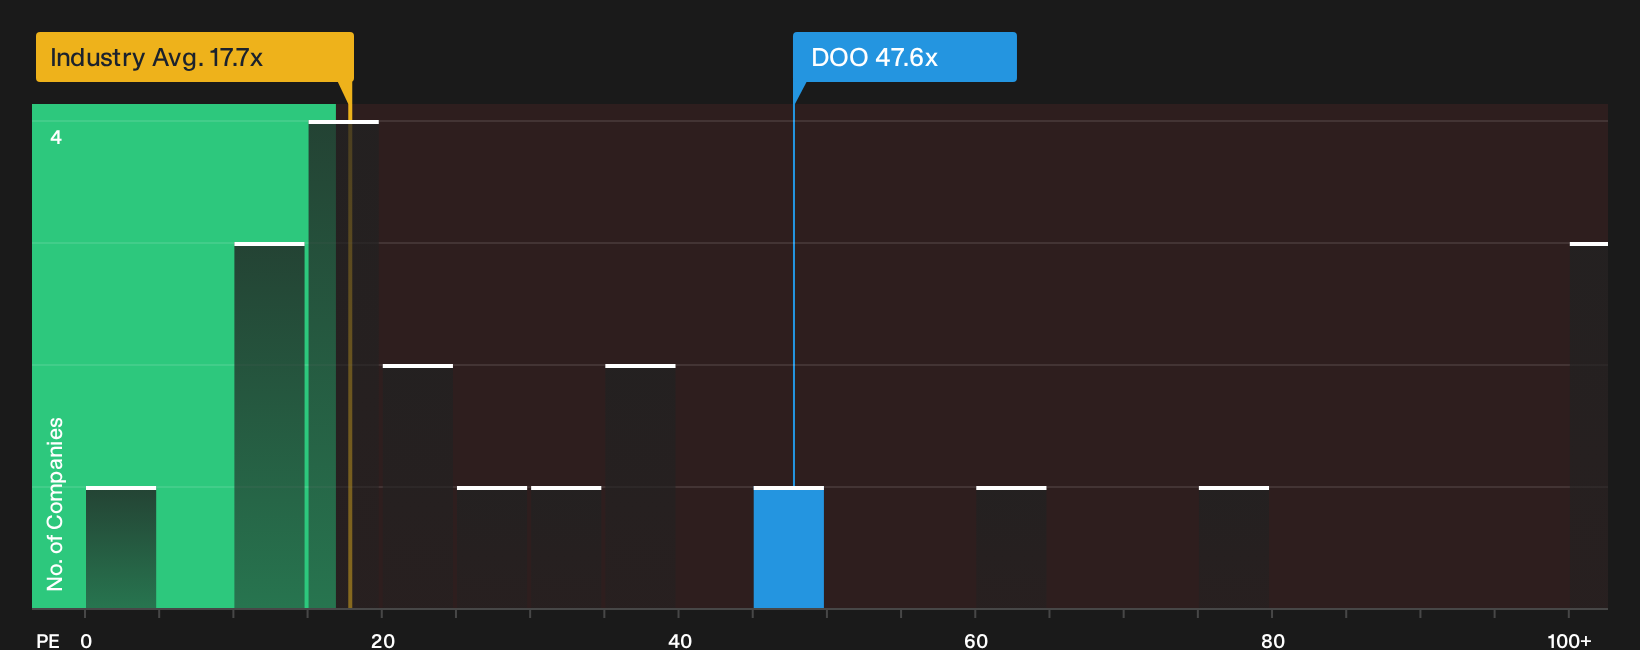
The first narrative leans on fair value estimates around CA$102.19, yet BRP’s current P/E of 47.6x tells a different story. The multiple is higher than both the Global Leisure average at 17.7x and the fair ratio of 42.6x, which tilts the picture toward valuation risk.
A gap that wide means you are paying a richer price than both peers and the level the fair ratio suggests the market could move toward over time. The key question is whether BRP’s expected earnings growth and forecasts justify staying above those benchmarks, or if the multiple eventually compresses toward them.
To stress test that view against earnings based valuation, review how the numbers stack up in our detailed breakdown. Then decide which story you place more weight on: the cash flow model or the earnings multiple driven view, with the help of See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages across BRP’s valuation and earnings profile create a real fork in the road for investors weighing risk against potential upside. Act while the data is fresh and pressure test both sides of the story by reviewing the 3 key rewards and 3 important warning signs.
Looking for more BRP investment ideas?
Do not stop with a single ticker. Use the Simply Wall St screener to surface fresh angles, compare quality, and pressure test every idea against better candidates.
- Target stability by reviewing companies that show consistent fundamentals in our list of solid balance sheet and fundamentals (7 results).
- Hunt for value by scanning the 5 high quality undervalued stocks that pair quality financials with prices that may not fully reflect them.
- Prioritize resilience by checking out 8 resilient stocks with low risk scores that score well on balance sheet strength and business risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com