


Recent commentary around Omnicom Group (OMC) has focused on projected third quarter earnings of $2.67 per share and revenue of $6.22 billion, with attention on profitability, market share, and client spending signals.
Omnicom Group’s recent share price has edged up, with a 7 day share price return of 3.08% and a 30 day gain of 3.75%. However, the year to date share price is down 2.31%, while the 1 year total shareholder return of 5.81% points to steadier long term momentum, as investors weigh leadership changes and optimism around AI driven marketing demand against valuation and earnings risk.
Scan how Omnicom Group compares with peers riding similar advertising and media themes by reviewing the hand picked 20 high quality undiscovered gems poised around brand, data, and digital demand.
Omnicom Group trades at a steep discount to both analyst targets and intrinsic estimates, even after the recent share price uptick. Is the market prudently discounting earnings risk, or mispricing a quality advertising platform on AI driven upside potential?
Most Popular Narrative: 22% Undervalued
Against a last close of $79.44, the most followed narrative puts Omnicom Group’s fair value at $102.00. This frames the current discount as a question of integration delivery and balance sheet risk rather than market apathy.
The expanded cost reduction and portfolio pruning program, which now targets disposals of about US$3.5b to US$3.6b of largely lower growth revenue and gross cost synergies of US$1.5b by mid 2028, is designed to support higher Core Operations margins and EBITA growth as remaining businesses scale.
See why 43 investors see Omnicom Group as 22% undervalued.
Result: Fair Value of $102 (UNDERVALUED)
Still, this Omnicom Group narrative depends on integration and cost savings landing as planned, while higher interest expenses could weaken any earnings progress that is achieved.
Find out about the key risks to this Omnicom Group narrative.
Another View: Omnicom Group On Earnings Multiples
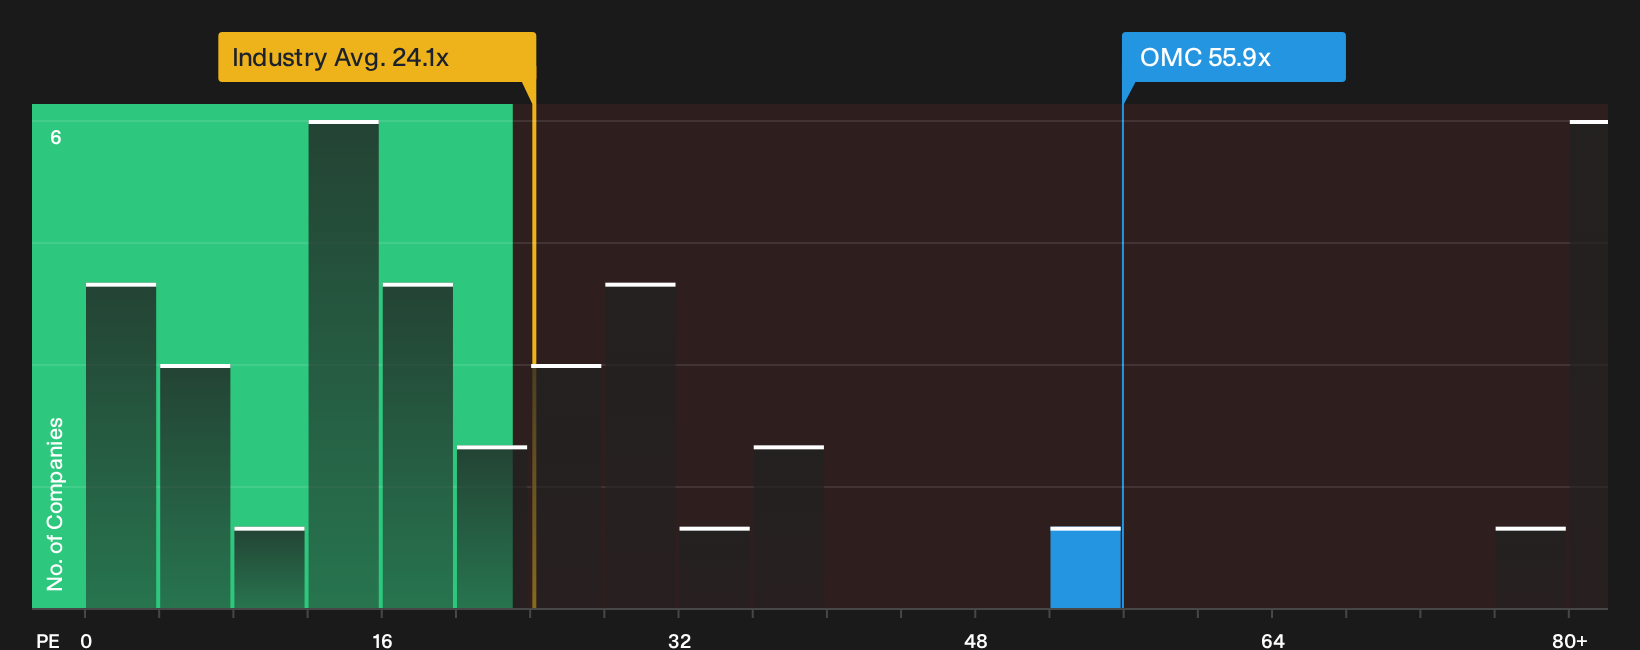
Omnicom Group screens very differently when you shift from future cash flows to current earnings. The stock trades on a P/E of 55.9x, which is well above the US Media industry on 25.3x and peers on 33x, and also above a fair ratio of 28x suggested by regression analysis.
That kind of gap can point to meaningful downside risk if sentiment cools, or simply reflect how much investors are already paying up for the integration and AI story. How comfortable are you with paying a rich multiple for a business still working through earnings volatility and one off items?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Omnicom Group are clear, so move quickly, review the data for yourself, and weigh both sides of the story using the 2 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Omnicom Group?
Do not stop with Omnicom Group. Broaden your watchlist with ideas built from hard numbers so you always have alternatives when sentiment shifts.
- Target resilient compounding potential by scanning a curated pool of companies that look mispriced on quality and value using the 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that pair higher yields with robust fundamentals through the 8 dividend fortresses.
- Prioritise resilience by filtering for companies with cleaner balance sheets and sturdier fundamentals via the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com