


Cosmo (SWX:CMHC) drew fresh attention after reporting positive Phase 2 topline data for its rifamycin 1% gel in distal ulcerative colitis and ulcerative proctitis, meeting the primary clinical remission endpoint versus placebo.
That clinical update comes after a volatile stretch for Cosmo’s equity, with the share price up 2.92% over one day and 7.96% over seven days, yet still showing a year-to-date share price decline of 49.81%. The three-year total shareholder return of 62.22% points to earlier momentum that has recently faded.
Scan how other under-pressure biopharma stocks with fresh trial data are setting up for their next move with a hand picked set of 615 high quality undiscovered gems.
Cosmo now trades well below analyst targets after a sharp year to date fall and a short term rebound on rifamycin data. Does that reset position the risk reward in favour of new buyers or signal a potential value trap ahead?
Most Popular Narrative: 47% Undervalued
Cosmo last closed at CHF52.90, while the most followed valuation narrative assigns a fair value of CHF100. The gap between those two numbers frames the current bull case far more than the short term share price swings.
Catalysts
Preliminary Unaudited Revenue and Cash• Revenue: €266.8 million, representing a year-on-year increase of 188% compared to €92.8 million in 2023. This includes significant project-based revenues from GI Genius™ and Winlevi® of €190.2 million.
• Operating profit for fiscal year 2024 was €148.9 million, compared to a restated operating loss of €1.9 million in 2023.
• Gross operating profit (EBITDA) increased by a very large percentage year-on-year to €161.2 million.
• Cash, equivalents and investments increased by 239% to €170.4 million, compared to €50.3 million in 2023, with zero debts.
Financial Guide for 2025
The company's forecasts for 2025 are minimal, as it is negotiating licensing agreements and does not want to give revenue projections based on advanced projects.
Total revenue: €102 to €107 million, of which recurring revenue (royalties and manufacturing revenue) is €85 million to €90 million, and project revenues are €17 million.
Core business EBITDA: €40 to €42 million, including cost of sales and selling, general and administrative expenses.
Strategic investment in research and development: €40 million, focusing on late- and early-stage assets and AI-driven innovations.
Overall EBITDA, including investments in research and development, is expected to be between €1 million and €3 million.
Cash, equivalents and investments are expected to remain above €110 million.
The market has responded to these forecasts with a sharp correction in the share price.
See why 84 investors see Cosmo as 47% undervalued.
Result: Fair Value of CHF100 (UNDERVALUED)
Still, Cosmo’s narrative leans heavily on successful licensing talks and clinical execution, so setbacks on partnerships or trial outcomes could quickly erode that 47% upside argument.
Find out about the key risks to this Cosmo narrative.
Another View: Cosmo On Sales-Based Valuation
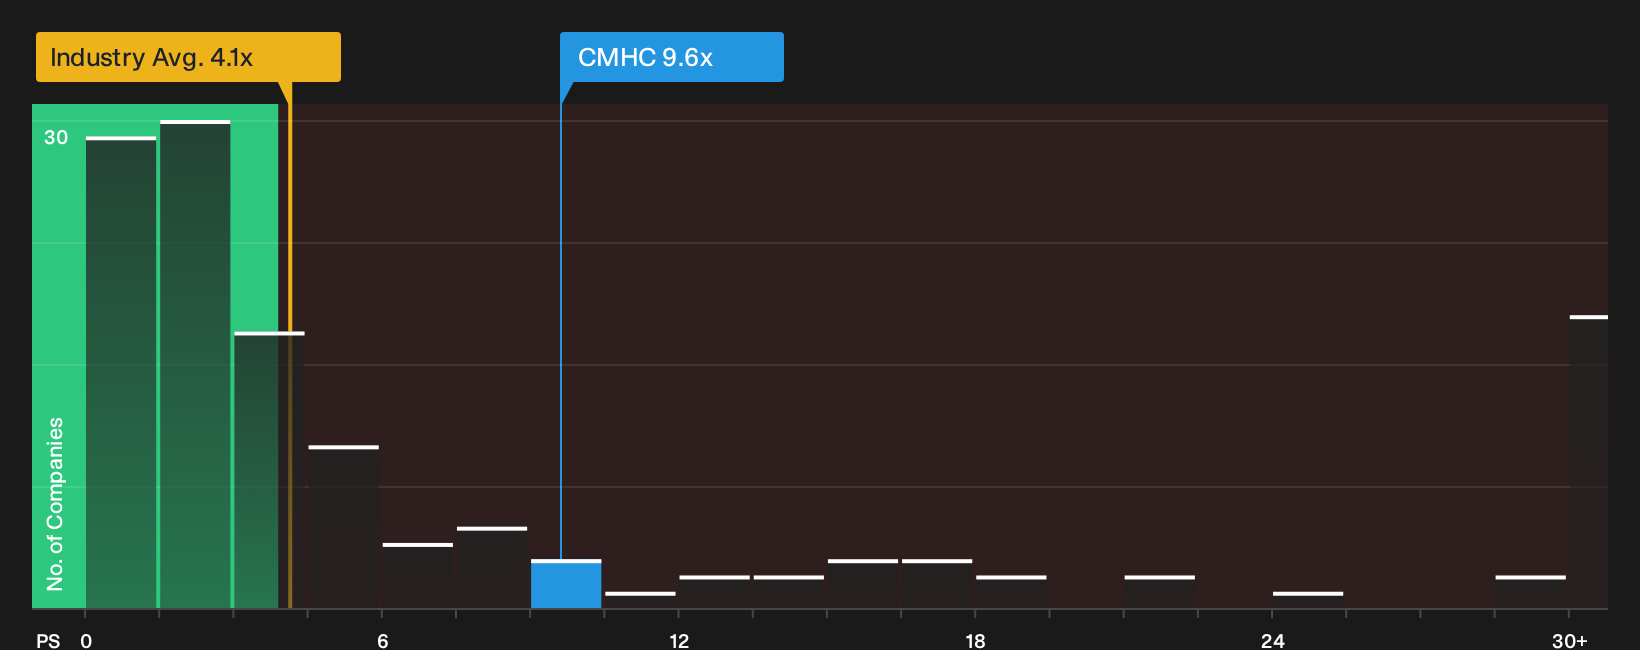
There is a very different read on Cosmo when you shift from fair value estimates to a simple P/S check. The stock trades on a 9.6x P/S ratio, while the fair ratio sits at 6.7x and the wider European pharmaceuticals group averages 4.1x.
Peers on this metric cluster closer to that 4.1x level, so anyone leaning on sales multiples alone sees far less upside and more risk that sentiment could move the ratio back toward the fair ratio over time. Which approach feels more useful for how you size a position: a cash flow story or this earnings multiple snapshot?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Cosmo is clearly split, so move fast, review the full data set yourself, and decide what really matters to your thesis with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Cosmo?
If Cosmo has sharpened your focus on pricing gaps and risk, do not stop here. Broader opportunities often sit just outside the stocks already on your radar.
- Target strong upside potential with 192 high quality undervalued stocks that pair quality fundamentals with prices that lag behind underlying business strength.
- Strengthen your income foundation by scanning 222 dividend fortresses built around resilient cash flows and higher yielding payouts.
- Reduce portfolio stress by focusing on 229 resilient stocks with low risk scores that aim to keep balance sheets and volatility on a tighter leash.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com