


Key Points
Apple's stock is nearing its highest valuation in the past decade.
Apple is facing a crisis in the memory chip market.
Apple (NASDAQ: AAPL) stock has had a phenomenal year, up about 26% while the S&P 500 (SNPINDEX: ^GSPC) is up around 12%. That's solid outperformance and impressive, considering that Apple really doesn't have much in the way of artificial intelligence tailwinds, unlike some of its big tech peers.
However, great stock performance doesn't always equate to strong business performance in the short term. It usually does over the long term. The reality is that some of the stock's gains to date may prove in vain, as Apple hasn't done enough to sustain these returns over the long term.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
In fact, I think a reality check could be coming shortly as Apple reports Q1 fiscal year 2027 results on Nov. 2. December-quarter guidance will be the first look at how much of the memory cost increase Apple is absorbing.
November's correction could come as a shock to some investors, but those paying attention know how difficult Apple's business environment is getting.
Image source: The Motley Fool.
Apple has become a safe haven for AI investors
Not everyone is sold on the notion that AI is the future. Many investors believe the big tech companies are investing far too much capital in this technology and would rather back a company that's taking a more modest approach, like Apple.
Instead of spending hundreds of billions on AI computing equipment, it's choosing to use Alphabet's Google Gemini as its base model and pay a fee each time it uses it. Over the long term, this could prove a bad decision, but with AI not making these companies a ton of money right now, it looks prudent in the short term.
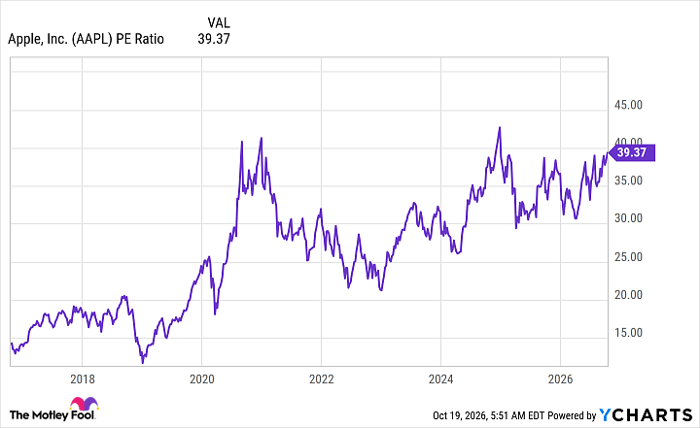
As a result of Apple not investing heavily in AI, it has attracted many investors, as it is viewed as a non-AI investment compared with its peers. This has caused its stock price to swell during 2026, and its valuation has followed suit. Apple now trades at some of its highest valuations seen in the past decade.
AAPL PE Ratio data by YCharts
Now, if Apple had returned to its previous valuation highs, posting jaw-dropping growth and excellent results, I would think differently. And while it's true Apple's results have been improving (its Q4 FY 2026 growth rate was 16%, the best since 2021), it's still nothing compared to what some of its peers are delivering.
Take AI powerhouse Nvidia (NASDAQ: NVDA), for example. Nvidia trades at a mere 27 times trailing earnings and is growing revenue at 106%. Furthermore, management estimates next year's revenue growth to be 70%. It's hard to convince me that a stock like Apple should be valued at a premium to that growth, but that's the case.
The bearish outlook on AI has gotten a bit out of hand in the market, and it could contribute to Apple's stock selling off in the last quarter of 2026 if investors rotate back into AI stocks. But there's also another issue for Apple unfolding.
Apple's margins could come under pressure
One of the biggest stories in the tech world during 2026 was the spring's memory chip price surge. Every company, from Nvidia to Apple, is facing the same problem, which is causing Apple to pay more for memory chips used in its devices. Apple has two choices: Raise prices or eat the cost. While Apple has marginally raised prices on some of its products, it may ultimately have to eat the costs of rising chip prices, which could harm margins.
Slimmer margins will exaggerate Apple's valuation and make it look even more expensive than it already is. Prior to departing from his CEO role, Tim Cook called this a 100-year flood for memory chip prices.
One of the largest memory chip suppliers in the industry, Micron Technology (NASDAQ: MU), told investors that memory market conditions will worsen in 2027 and 2028 compared to 2026. That doesn't bode well for Apple's future and could spur a sell-off in Apple's stock.
Apple, as a company, faces many factors it can't control. Regardless, I think there are far better investments out there, and now may be the time to take some gains and roll into some beaten-down alternative AI stocks.
Keithen Drury has positions in Alphabet, Micron Technology, and Nvidia. The Motley Fool has positions in and recommends Alphabet, Apple, Micron Technology, and Nvidia. The Motley Fool has a disclosure policy.